Home Blog Page 2257

Subaru Outback vs Nissan Pathfinder: a close competition

The Nissan Pathfinder was introduced in 1985. The vehicle has improved over the years from SUV to CUV. It is a perfect fit with its size between Murano and Patrol. The first generation was based on Nissan D21 Pickup Platform with the last one being the Nissan D platform. Over the generations it has not only improved in mechanics but also in overall body structure.

Subaru Cars were first introduced in 1954 that improved over the years for good. The Subaru Outback came in market in 1994. It is basically derived from two Subaru Brands of Subaru Legacy and Subaru Impreza hatchback.

Design

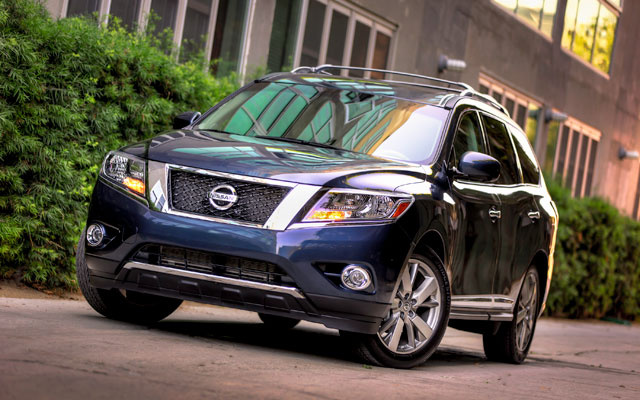
SUBARU LEGACY OUTBACKThe nissan pathfinder comes with a built in class, whether it is the towing capacity or the seating system all happens to the refined level in this vehicle. The colors available range from the light ones of white, beige and silver to dark range of black, blue and grey, so a variety of choices are in hand of customers at the time of purchase. The inside gives panoramic view of outside, so whether it is mountains, highway or city you feel walking along side it enjoying every moment.

The Subaru Outback has symmetrical all wheel drive giving optimal balance and even power for stability and efficiency feeling. The flexible space with integration of roof rail is a positive in itself with 60/49 split for better cargo room. The moon roof is also there though the heated seats, mirrors and windshield gives comfort in weather as harsh as winter.

Technology

The around view monitor in the latest Nissan Pathfinder confirms minute details like line around the parking space, the adjacent object with blind spot detection and much more for ease in parking and driving. The entertainment is further refined from single screen TV and navigation to tri-zone entertainment through the two screens at the back of front seats. The heated steering wheel is a technology that gives driver comfort to drive for long without physical fatigue, while Nissan intelligent key unlock all four doors and open power lift gate without the need of key.

The Subaru Outback brings with it eyesight driver assist with two cameras on the rear view mirror that react to condition smartly before you do. The alert sound with visual warnings keeps you inform of danger before it happens. The Bluetooth technology makes phone and audio system managed by voice with GPS navigation also working on voice command.


Safety

The 50 standard features in latest Nissan Pathfinder makes the security magnified. Aside from the standard anti-lock braking system and traction control that brings in wheel lock prevention with power wastage reduction for traction optimization; there is more to offer. The bake assist with electronic brake force distribution detects how hard the brake is needed and applies maximum brake force to rear brakes. The Subaru Outback comes with smart braking system where anti-lock braking system and electronic brake force distribution work on smartly managing vehicle. The advance protection system and roll over sensors further makes the airbag deployment with other few things happen with efficiency.

The vehicles have cut throat competition, with features of each other to counter.
Equity Bank wins court battle to roll out thin sim card

0

After a year-long court battle, Equity Bank can finally go ahead and roll-out its thin Sim technology in Kenya.

The suit dismissed by the High Court Thursday was filed by businessman Bernard Murage. Mr Murage had argued that Equity Bank had not given proper assurance to its clients concerning the safety of their personal data.

However, High Court Judge Isaac Lenaola ruled that since the Communication Authority and Central Bank of Kenya having approved the roll-out, the court has no reason to interfere “with the merit of a decision clearly falling within the relevant statutory agency without allegations of any irregularities on its part.”

TRIAL BASIS

Last year, Communication Authority of Kenya allowed Equity Bank, through its subsidiary, Finserve Africa Limited, to implement the new technology but on one-year trial basis.

However, a number of cases filed by individuals and organisation have been stalling the roll-out but yesterday’s ruling is likely to form a precedent for the go ahead.

“I am convinced to find that the alleged innovation will enhance competition in the provision of services and will be beneficial to those who subscribe to it. I therefore do not see why this court should intervene and block the roll out of the technology, the subject of this petition,” Mr Justice Lenaola added.

The new Sim card is paper-thin and carries an embedded chip. Users overlay it on their primary SIM regardless of their network and can then use services from two providers, thus increasing competition.

MPESA SYSTEM

Mr Murage had sued FinServe, Equity Bank, the Communications Authority as well as the Central Bank but the judge declined to order the regulator and CBK to stop the project as requested by him.

The judge also declined to rule on request made by the petitioner to consider the concerns of telco Safaricom regarding the technology.

Last year, Safaricom raised objection to the introduction of the service saying the technology will compromise security of M-Pesa system exposing its 19 million money transfer service subscribers to fraud.

“My answer to that submission is simple; I do not have those concerns on record and even if I had, Safaricom is not a party to this petition and it would be against the law for it to agitate its case through third parties or agents without saying so,” Mr Lenaola said.

“I therefore find that the alleged threat to right of privacy has not been proven and the petitioner’s complaints in that regard are dismissed,” the judge concluded.

Reasons why your cow fails to conceive

A cow exhibiting signs of heat is considered of utmost importance to a farmer.

This could be the beginning of a new life that will, upon successful conception, be brought forth in nine months. The average estrus cycle of a cow is approximately 21 days, though sometimes may vary between 18 to 24 days.

Most farmers have indicated that some of the typical signs associated with a cow in heat include increased nervousness/restlessness, mounting, head mounting, chin resting, standing to be mounted and a swollen vulva, amongst others.

Farmers must be vigilant and know what to watch out for in relation to how cows will behave in estrus, know which cows to watch by keeping good reproduction records, know how to make good use of heat detection kits such as marking crayons (often applied on the rump of the animal and will be wiped off or smeared if the animal is mounted); pressure-sensitive pads often glued to the rump of the animal emitting some red liquid when pressure is applied and heat-mount detectors amongst others. It is also recommended that farmers adjust their management regime to improve estrus detection. This can be realised by taking advantage of the “hot spots and times”.

Observation of behaviour in the “hot spots” is critical, as is the establishment of the “hot time” to detect cows in estrus often in the mornings or evenings before milking is key.

However, there have been numerous cases where the farmer seeks the services of an artificial inseminator and the services yield naught. This could either be due to poor heat detection or that the animal is not in heat. The latter is not a strange phenomenon as often farmers have indicated that some cows within the herd do not exhibit estrus behaviour.

This phenomenon is commonly referred to as anestrus, a condition defined as the lack or absence of the expression of estrus. This should not be confused with silent estrus, where no clear signs or estrus can be detected in an animal despite the ovarian changes taking place.

In dairy cattle, anestrus has been known to be associated with various factors. These factors affect the demonstration of estrus and knowledge of them is highly informative to dairy farmers and herein are possible solutions to these problems upon diagnosis.

ENVIRONMENTAL

These are issues that are associated with the surroundings and possibly management. Cows that have not been turned out, a situation whereby the cows are kept for long periods within the housing environment as opposed to being left to graze periodically in open fields, have a tendency to not display estrus.

It has been observed that movement from enclosed areas to open fields stimulates estrus. In addition, the type of housing affects the display of estrus behaviour.

The predisposing factor is slippery floor surfaces. It has been documented that on average, animals that have access to a grooved or non-cemented surface exhibit a longer duration of heat as opposed to those that have access to slippery floors.

It has also been observed that mounting occurs more frequently when cows are on a grooved or non-cemented surface.

It is thus recommended that floors should be either grooved to provide firm ground on which to stand. Good footing is very critical.

Heat stress is also a contributing factor. Some cows exhibit estrus behaviour better in cooler temperatures.

Another minor but relatively important issue is the number of animals in the herd. Sometimes, overcrowding may result to poor estrus detection but also small animal herds have been reported to affect the exhibition of estrus behaviour due to the reduced interactions between the animals.

DISEASES

The occurrence of some diseases such as ovarian cysts and leptospirosis has also been associated with anestrus. It is reported that approximately 70 percent of cows with ovarian cysts are anestrus.

It is thus recommended that cows diagnosed with this condition be treated immediately by a veterinarian. Cows that have sole lesions or poor structural conformation or any form of lameness have delayed estrus.

This is a common cause of anestrus and can be treated through following a prescribed hormonal programme such as progesterone supplementation. This treatment can also be used to reduce the incidence of ovarian cysts.

NUTRITION
Poor nutrition has also been known to contribute significantly to non-cycling. There has been an observed lack of exhibition of estrus behaviour in cows that have lost weight after calving as opposed to their mates in the herd who have minimal weight loss.

In addition, nutritional deficiencies such as low dietary phosphorous and vitamin A have been reported to cause anestrus. Anaemia due to iron deficiency or high levels of intestinal parasites could also cause cows to be anestrus.

Farmers are advised to put in place the necessary corrective measures such as introducing supplements and following a well-balanced feed program.

POT-PARTUM

Often after calving, cows experience postpartum anestrus. This period is a natural occurrence and cannot be avoided. It could be termed as a form of biological shut down by the dam for protection of both itself and its offspring. This can also be treated through hormonal and management strategies.

Indeed, as farmers grapple with inability to detect estrus, some of the above mentioned issues should be looked into and resolved before a farmer concludes that the animal is unproductive and thus opt to cull it.

Safaricom now to run fertilizer distribution system

Safaricom has been contracted to pilot an electronic-based fertiliser distribution system that will avail the farm input to farmers early and help eliminate corruption from the subsidy scheme.

The ministry of Agriculture has said that ‘E-fertilizer Subsidy Management System’ will enable it to issue electronic vouchers directly to farmers through their mobile phones.

“Our solution, should the pilot be successful, will allow us to increase transparency in the allocation of fertiliser to over 3.5 million smallholder farmers across the country using mobile phones,” said Agriculture principal secretary, Ms Sicily Kariuki.

The system works using data and SMS services to manage the issuance, redemption and reconciliation of vouchers from farmers; it is managed by Safaricom.

Ms Kariuki said that existing agro dealers and fertiliser providers are being signed up into the system by the ministry.

Collected information will be used to verify and vet farmers. The farmers can request, redeem and reconcile vouchers through their handsets.

The piloting begins in Uasin Gishu, Trans Nzoia and Bungoma counties in preparation for the next season of subsidy fertiliser distribution.

“Mobile technology has the ability to revolutionise traditional distribution models. This turn-key solution is just one of several that Safaricom hopes will transform the operations of businesses across Kenya,” said Safaricom CEO Bob Collymore.

Farmers will then use the vouchers like cash to purchase the inputs from agro-dealers. This will help get rid of middlemen.

It will also ease the distribution and avail fertiliser to farmers before the planting season starts.

“As at the beginning of May, a total of 510,000 tonnes of various types of fertilisers had been imported against an estimated demand of 490,000 tonnes,” said Ms Kariuki.

Chris Kirubi defends Haco staff over profit manipulation, blames poor morale for sales dip

0

Directors of Haco Tiger Brands have defended their company on allegations of financial impropriety, saying the dip in sales was as a result of low staff morale.
Releasing financial results last week for Tiger Brands, which is listed on the Johannesburg Stock Exchange, the chief executive officer, Mr Peter Matlare, singled out Kenya and Nigeria for the drop in profitability.
He said that drop in profitability in its Kenyan arm was caused by the need to re-adjust overstated performance in previous years.
Mr Matlare told investors that the irregularities in the financials was carried out by top executives “in a number of ways that we would not ordinarily expect them to”.
However, the South Africa executives and businessman Chris Kirubi changed this narrative Thursday.
“The investigation involving the accounting practices lowered staff morale, which led to a slump in sales of our goods,” said Mr Kirubi, who owns a 49 per cent stake in the joint venture.

DID NOT STEAL MONEY
“Staff did not steal from the company. Neither money nor goods were taken from the company. There was a mishap in invoicing where goods were ordered in advance in one accounting period but invoiced in another. Staff were able to backdate future sales, which led to the error,” he said.

Tiger Brands, which has controlling majority in the company, had noted that the Kenyan executives led by sacked managing director, Mr Geoffrey Kiarie, altered financial statements and engaged in pre-invoicing to reach their performance targets.
Overstated profits
Stock that was yet to be sold was moved to third party warehouses to make it look like performance targets had been hit. As result, the team is said to have overstated operating profits by over Sh879 million.
“There were no major financial irregularities involved and we have improved internal invoicing procedures to ensure such errors do not occur in the future. The governance of the company is in fine form and we will ensure that our accounting practices adhere to international standards,” Mr Matlare noted.
The Institute of Certified Public Accountants of Kenya said on Tuesday that it had opened investigations into any accounting fraud that might have occurred at Haco Tiger company.

What awaits Equity Bank in DR Congo

0

The following opinion feature by investment analyst George Bodo was first published in the Business Daily.

Equity Bank’s purchase of a 79 per cent stake in ProCredit Bank DRC marks the end of ProCredit Holding’s presence in Sub-Saharan Africa (SSA). The Frankfurt-based financial holding group has now exited all its five African businesses.

In 2008, its Angolan business was sold to Banco de Investimentos. In May 2010, Ecobank Transnational Incorporated (ETI) acquired ProCredit’s business in Sierra Leone. In April 2014, ProCredit Holding sold all of its shares in Banco ProCredit Mozambique to ETI.

In October 2014, ProCredit Holding disposed of its shares in ProCredit Savings and Loans Company Ltd Ghana, representing 96 per cent of total capital, to Fidelity Bank Ghana Ltd.

It seems the business of providing loans to micro-enterprises in Africa is no longer a priority for the German financial conglomerate (however, the jury is still out on the real reasons why it is exiting SSA).

With the acquisition, Equity Bank now becomes the first Kenyan bank to open shop in the DRC. However, it is not a unique phenomenon to the DRC’s banking sector, which is already dominated by foreign banks.

Out of the 18 commercial banks currently operating in the country, only two are locally owned: Banque Commerciale du Congo or BCDC, which is majority-owned by the State, and Trust Merchant Bank—which is majority-owned by a local investor.

The remaining 16 banks are foreign majority-owned. Additionally, Equity now becomes the 10th pan-African financial group to establish operations in the DRC.

So just how viable is this acquisition? It will prove viable, only if Equity’s shareholders are willing to wait just a little longer. It’s definitely going to be the proverbial ‘fly trying to move the dung uphill’ story.

The DRC is a tough terrain and Equity is going to be navigating four unique and difficult variables.

First, the DRC is an informal economy and back-of-the-envelope calculations suggest that up to 80 per cent of the money supply is held outside the formal banking system.

Financial literacy levels remain very low and only four per cent of adults have a bank account with a formal financial institution. Equity’s own success story in Kenya has been driven by (i) a well financially informed bankable population; and (ii) a regulatory driven financial inclusion agenda. The Central Bank of Kenya has been very open to new innovations in the alternative delivery channels space.

Cleary, these two conditions aren’t entirely present in the DRC. Additionally, mobile money in the DRC is proving to be a hard nut to crack.

World Bank statistics show that in 2013 mobile cellular penetration rate in the DRC was 42 per cent, well below the SSA rate of 65 per cent.

There is clearly an opportunity here, but don’t be fooled; the telecommunications sector continues to suffer from poor infrastructure and high operational costs to the extent that the cost of sending money through mobile phones would be slightly higher than sending through money transfer organisations.

A study launched by GSMA in July 2013 showed 53 per cent of households sent or received remittances. It will take massive investments by telecoms operators for mobile money to be acceptable in the DRC. By contrast, in Kenya, the infrastructure is there and mobile money is highly acceptable.

Second, the DRC is a foreign currency-driven market, both on the funding and asset side. On the funding front, banks’ foreign currency deposit liabilities constitute an aggregate 86 per cent of their total deposit liabilities while on the asset side, 95 per cent of lending is in foreign currency, with US dollar (USD) lending constituting nearly the entire foreign currency loans basket.

It’s not yet clear how long it will take for Equity to fully rebrand all ProCredit outlets but as and when it does so, the excruciating battle to grow the retail deposit franchise afresh (and be able to attract low-cost USD deposits) will begin.

Back in Kenya, the market is local currency-driven and the bank has one of the strongest retail franchises.

Third, ProCredit’s profitability has been on a decline with return on shareholders’ equity declining from nine per cent in 2012 to five per cent in 2014 (mainly as a result of the increase in equity).

To reverse this trend, topline has to grow by double-digits and, to achieve such a growth quantum, Equity will have to strengthen its value proposition in the DRC that will include balance sheet strengthening, products update, systems upgrade and people alignment—all of which take some time and cost a lot of money (you just need to look at Uganda and Tanzania businesses).

Another reason why strengthening value proposition in the DRC will be important is because of the significant concentration levels: the top five banks control nearly 70 per cent of both assets and deposits.

Finally, the monster of non-performing loans. There is no national identification system in the DRC—neither is there robust credit referencing.

There is only one credit bureau, which apparently is housed inside the central bank and whose operations are still largely manual and widely viewed as ineffective, where only relatively few clients and mainly corporate clients with large loans are being included. In Kenya, all these are available.

Aga Khan Hospital to pay woman Sh. 4.3 million child support after failed birth control

A hospital has been ordered to fund the upbringing of a child who was conceived after a long-term contraceptive implant on her mother failed.

The High Court directed Aga Khan University Hospital family planning clinic to pay the woman (name withheld) Sh4.3 million to cater for the unplanned child.

Justice Hatari Waweru also ordered the hospital to pay the woman a further Sh500,000 for pain and loss of her comfort.

“This sum (Sh4.3 million), if wisely invested, should bring in an annual income that will go a long way in maintaining and educating the child without the necessity of delving into the principal sum,” Waweru ruled.

The court heard that the now mother of three visited the clinic for a long-term birth control as she did not want to have more children.

The woman said the reason she did not want a third child was because she and her husband were already struggling to bring up their two children.

She told the court that on July 4, 2011, the hospital advised her that implanon was the most appropriate contraceptive method for her.

Implanon is a flexible plastic rod about the size of a matchstick that contains a progestin hormone called etonogestre. It is inserted just under the skin of the inner side of the upper arm.

The court also heard after going through the medical procedure, she was assured that it would be safe to have sex with her husband without using any protection.

She was assured that the implant would secure her from pregnancy for at least three years.

But she soon had the shock of her life when she realised that her periods had failed. She did a home pregnancy test and confirmed that that she, indeed, was pregnant.

She rushed to the same hospital, which also confirmed she was pregnant. Other tests confirmed that the contraceptive had been implanted in her arm.

Poultry farmer who developed kit to test egg fertility

A local agricultural innovator developed a kit for poultry farmers to use in checking egg fertility and assess progress during incubation. Called ‘Candling box,’ farmers can use the kit to know which hens lay eggs that can’t hatch, and are due for culling.

According to Mr Geoffrey Kago, the inventor, he is selling about 50 of the candlers a month compared to 10 this time last year. He came up with the concept after he encountered the challenges in his own poultry farming in selecting between eggs to put into the incubator and those to leave out. The candler helps “assess the defects in an egg and check its progress, like nutrition,” says Mr Kago.

The candler is rectangular in shape and slightly bigger than a brick and has a hole on one side designed to fit the pointed side of the egg.

Inside, it is hollow with a lighting fixture. To check the egg’s condition, the farmer places its pointed side in the hole and lights the candler in a dark room.

If the farmer notices the air sac in the less pointed side is sagging and big, then it’s a sign the egg has stayed for too long and thus dehydrated. Therefore, it can’t be placed in an incubator to hatch, since it has lost 15 per cent of the water in it.

Ideally, according to Mr Kago, to select an egg for hatching it must be less than seven days old. “As the egg ages, the air space becomes bigger,” he says. Where the farmer sees two yolks in an egg, it is also unsuitable for incubation.

Mr Kago also advises farmers to check the outward physical appearance of eggs and ensure that they are of uniform colour and size for that particular bird breed.

Eggs with blotches, wrinkles, bumps or multiple colours may not hatch if incubated, as it’s a sign of deficient nutrients in the hen that laid the eggs.

Besides checking the egg before it’s placed in the incubator, the candler helps farmers to gauge the progress of eggs waiting to hatch in the incubator. Thus, a farmer is able to isolate spoilt eggs and tell the number of chicks one is likely to get.

By checking the progress of eggs, a farmer could also tell which of the hens lay fertile eggs, as well as which cocks are old and inactive with the hens. That way, farmers can pick chicken for slaughter or sale and retain the most productive.

Mr Kago advises poultry farmers that prior to checking the eggs in the incubator, they should wash their hands to avoid contaminating eggs.

When an egg is progressing to hatch, the candler shows a consistent formation of a network of blood veins from day 10 to day 18, a silhouette chick image is visible. “It’s the growth of an embryo,” he says.

From his base in Gitaru on the Nairobi-Nakuru highway, he sells a candler with lighting system for Sh1,000 and one without for Sh500. The one without light sees farmers use ordinary torch to examine their eggs. Mr Kago says the demand for his candlers is propelled by the need for new innovative egg incubators that he also invented and sells. It can check eggs for ducks, turkeys and guinea fowls, and hens.

Sameer partners with Chinese company for cheaper tyres

0

Influx of the market by cheap Chinese tyres has pushed a regional firm into producing a cheaper brand to gain competitive advantage.

Sameer Africa Tuesday announced a partnership with a Chinese company to produce and sell its price fighter brand Summit tyre regionally with the first shipment already distributed here.

Group Managing Director Allan Walmsley said the firm’s brand had undergone turbulent times in the past year due to dumping from the Asian market and the conflict in South Sudan.

“It has been an extremely difficult year for us with cheap imports from subsidised markets such as China flooding the market. Our strategy, however, is going to address this because we already have a manufacturer based in China to manufacture tyres from there. We test every consignment we receive to ensure quality is maintained,” he said.

The tyre maker said the new brand had recorded good uptake since the first shipment arrived.

The company also revealed a modernisation plan set to reduce its cost of production marginally and speed up output after sealing a deal with a technical and equity investor.

Negotiations with an unnamed investor, who is expected to pump in over Sh1 billion, have been going on for the past 18 months.
Sameer Africa posted a Sh66 million loss in earnings for the year ended December 2014.

The group now plans to establish more distribution centres across the country as well as diversify into other markets, including Mauritius, Mozambique and Nigeria, to increase sales. According to Mr Walmsley, dumping of counterfeits reduced the firm’s earnings by 22 per cent last year.

The tyre producer based in Nairobi’s Industrial Area has a production capacity of 600,000 per day. It sources 95 per cent of natural rubber from Malaysia while the rest comes from Malawi and DR Congo.

The East African tyre market, estimated at about four million tyres a year, has had challenges just like in other regional markets, with factories in Zimbabwe, Mozambique, Nigeria and Tanzania going off track.

Equity Bank buys out DRC bank at Sh. 6 billion

Equity Bank Group has made an entry into the Democratic Republic of Congo through acquiring a controlling interest in ProCredit Bank.

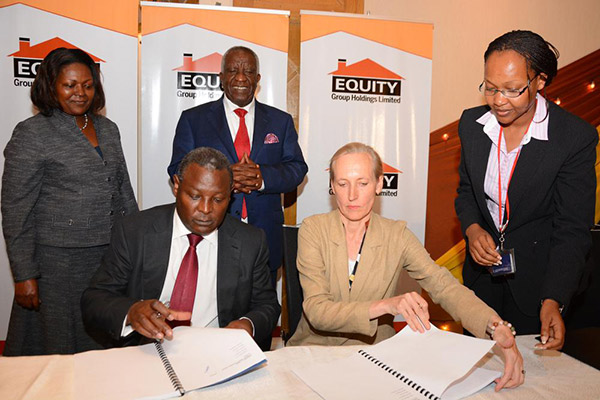
Equity will pay about Sh6 billion to gain a 79 per cent control of the seventh largest bank in the country.

Making the announcement Tuesday, Equity Group chief executive James Mwangi said the DRC presented huge opportunities for the bank owing to a large population of more than 85 million people, most of whom are excluded from formal banking services.

“The bank is well positioned for growth in the vast and resource-rich country as the market scales up its banking penetration across the over 85 million population from current levels of under 4 per cent,” noted Mr Mwangi.

The move comes less than two months after the bank announced it would spend Sh200 billion in its pan-African expansion plans that would see it venture outside its East African stronghold to Southern and West Africa.

The investment in ProCredit, the DRC-based German owned small and medium enterprise (SME) lender, marks its first step in a journey to establish its presence in 15 new African countries in a decade. The transaction is subject to regulatory approvals in the two countries.

Part of the Sh6 billion investment will go towards doubling the bank’s branch network to 30 from the current 15.

CONFIDENT

“After evaluating various bids, ProCredit Holdings was clear that Equity Group provided the right strategic fit to support the further development of ProCredit Bank Congo S.A. We are very confident that Equity Group will offer excellent prospects for our clients, staff and most importantly, for DRC’s economy,” said ProCredit Holdings Manager Helen Alexander.

Equity Bank

Established in 2005, ProCredit has net assets of $25 million (Sh2.5 billion) and a customer base of over 170,000.

Some of its shareholders include the German Development Bank (KfW) and the International Finance Corporation (IFC), who will hold 12 per cent and 9 per cent shareholding respectively in the new structure after the acquisition.

Those that have exited include Stichting Doen (which held 12 per cent) and Bio (which had 6 per cent).

Equity’s next move will be to expand to Zambia, Malawi, Angola, Mozambique and Zimbabwe in the Southern Africa region, as well as Ghana, Cameroon and Nigeria in West Africa.

Ethiopia and Burundi are also on its expansion radar.

In its growth journey, it will deploy mergers and a mix of acquisitions for the relatively large countries and greenfield developments for the smaller ones.

Currently, the lender has footprints in Kenya, Uganda, Tanzania, Rwanda and South Sudan.

Save for the Ugandan operation, which was started by way of acquisition, all other outlets in East African countries were launched from scratch.

It is targeting to grow its customer base to 100 million in 10 years from about nine million currently.