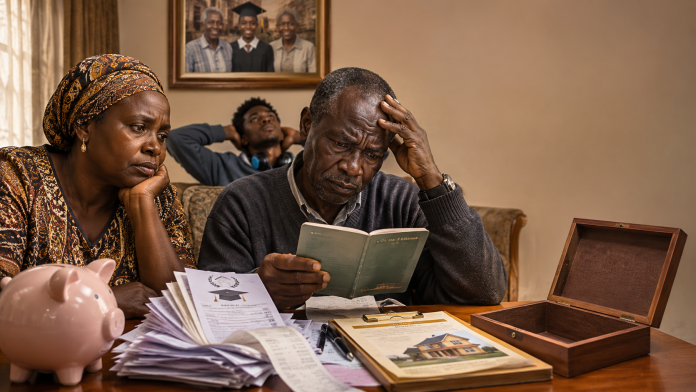
When Parents’ Sacrifices Become Their Children’s Dependency: Perhaps the greatest tragedy of the education and career illusion is not unemployment itself.
It is the destruction of family wealth that was accumulated over generations.
In many African families, wealth is built slowly. A grandparent acquires land. A parent builds a business, purchases property, saves money or invests in assets. The next generation is expected to improve upon that foundation.
But increasingly, some families are caught in a cycle in which wealth is accumulated by one generation, consumed by the next and never transferred sustainably to the third.
The financial sacrifice of parents
Parents may spend decades financing their children’s education.
They pay school fees, university tuition, accommodation, transport, food, medical expenses, laptops, smartphones, holidays and other lifestyle costs.
Some parents take loans against their property. Others sell land, withdraw retirement savings, reduce business investment or postpone important financial decisions.
The expectation is that their children will eventually become financially independent and contribute to the family’s prosperity.
But if the children remain unemployed or underemployed for prolonged periods, the financial equation changes dramatically.
Instead of receiving support from their children during retirement, parents continue financing adult dependents.
A 25-year-old becomes a 30-year-old dependent.
A 30-year-old becomes a 35-year-old dependent.
In some families, the dependency continues well into the forties.
The financial burden is no longer temporary.
It becomes a permanent household expense.
The retirement crisis parents never planned for
Parents who spent their productive years financing education may reach retirement without sufficient assets.
Their businesses may have lost capital.
Their investment portfolios may have been depleted.
Their properties may have been sold.
Their savings may have been exhausted.
At precisely the moment they should be enjoying financial security, they find themselves supporting adult children who are unable to support themselves.
The tragedy is compounded when parents are ageing, their health is deteriorating and their earning capacity is declining.
The children who were expected to become their retirement plan become an additional financial liability.
This is one of the most painful reversals of the African family economic model.
When dependency creates resentment
Long-term dependency can also create serious emotional and social tensions.
Parents may become frustrated by children who appear unwilling to work, accept opportunities, learn new skills or change their lifestyles.
Children may become resentful of parents who impose financial restrictions, demand accountability or refuse to continue funding their lifestyles.
Family relationships deteriorate.
In extreme cases, financial disputes over inheritance, property and parental resources can lead to exploitation, elder abuse, threats and criminal behaviour.
It is important not to generalise these extreme cases to unemployed young people. Most struggling graduates are not criminals. However, financial dependency, unresolved family conflict and entitlement can create vulnerabilities that families must address before they become destructive.
What keeps us from achieving our Financial Goals
Generational wealth is more than inheritance
Generational wealth is not simply the property, cash or businesses parents leave behind.
It also includes:
- Financial literacy.
- Work ethic.
- Entrepreneurial skills.
- Professional networks.
- Emotional resilience.
- Responsibility.
- A culture of saving and investing.
- The ability to create and manage businesses.
- Respect for property and capital.
- The capacity to create wealth independently.
A family that transfers millions of shillings to children who have never learned how to manage money may be transferring capital without transferring the capacity to preserve it.
The wealth may disappear within a few years.
A family that transfers modest assets but equips its children with discipline, financial intelligence, entrepreneurial competence and a strong work ethic may create wealth that survives for generations.
Parents must rethink the investment strategy
Parents need to ask difficult questions before committing the bulk of their financial resources to expensive education.
Is the school providing genuine value?
Are the children acquiring practical skills?
Are they learning financial literacy?
Are they being exposed to entrepreneurship?
Do they understand the cost of living and the realities of employment?
Are they learning how to work?
Are they participating in family businesses or productive activities?
Are parents building assets alongside paying school fees?
Are children being prepared to become independent, or merely comfortable?
Education should be one component of a family’s investment strategy, not the entire strategy.
Parents should consider balancing education expenditure with investments in businesses, property, retirement savings, financial assets and productive ventures.
Children should also be exposed to the realities of money, work, business and responsibility from an early age.
They need to understand that wealth is created, not merely inherited.
How your family’s poor or rich past affects your approach to money today
The uncomfortable truth
The dream of giving children the best education is noble.
But the belief that expensive education guarantees success is dangerous.
A university degree cannot guarantee employment.
A prestigious school cannot guarantee character.
A comfortable upbringing cannot guarantee resilience.
A parent’s wealth cannot guarantee a child’s financial independence.
And an expensive education cannot compensate for a lack of discipline, initiative, practical skills and willingness to work.
The real measure of parental success should not be the institution from which a child graduates.
It should be whether that child is capable of standing independently, creating value, managing resources, supporting a family and contributing to society.
Parents should invest in education. But they must invest equally in character, competence, entrepreneurship, financial literacy and the preservation of family wealth.
The objective is not merely to produce graduates.
It is to produce capable, responsible and economically independent adults who can build upon what previous generations created.
That is the difference between spending wealth on children and building wealth through generations.