An unexpected expense can turn an ordinary day into a stressful one for someone without a financial cushion.
A medical bill, a car repair, a family need, or an urgent purchase can arise when there is little cash set aside.
Traditionally, people relied on borrowing from friends and family, and bank loans to sort such emergencies.
However, banking has changed that equation through credit cards, giving customers access to ready credit before an emergency arises.
A credit card is essentially a revolving credit facility packaged in the form of a payment card. Unlike a debit card, which accesses money already held in a bank account, a credit card allows the customer to spend money provided by the lender up to an approved limit.
As the customer repays the amount borrowed, the available credit is restored, subject to the terms of the facility.
How a credit card works
When a bank approves a credit card application, it assigns the customer a credit limit based on its assessment of the applicant and the product’s eligibility requirements. The limit represents the maximum amount the customer can borrow through the card at a given time.
The card can then be used to pay for goods and services at participating merchants, make online purchases and, depending on the product, withdraw cash from an ATM.
For example, a customer with a Sh100,000 credit limit who spends Sh20,000 would have Sh80,000 of available credit remaining, before applicable charges. The Sh20,000 becomes part of the amount the customer is required to repay.
At the end of a billing cycle, the lender provides a statement showing transactions, the outstanding balance, minimum payment and payment due date. The customer can then repay the amount according to the terms of the card.
Co-op Bank’s credit card offering
The Co-operative Bank of Kenya is among the financial institutions offering credit cards to customers.
The card provides access to an approved credit limit that can be used locally or internationally. Unlike a debit card, a credit card is not linked to money held in a bank account. Instead, the bank assigns the cardholder a credit limit, effectively providing access to a loan that can be used through the card.
The funds can be accessed by withdrawing cash at any Visa-branded ATM or by paying for goods and services at outlets that accept Visa cards.
These include supermarkets, fuel stations, restaurants, pharmacies and other retail outlets. Customers can also use the card for online purchases, including clothing, books, furniture, subscriptions and other services.
Why you need a Co-op Bank credit card
One of the key advantages of the Co-op Credit Card is that you can pay for goods and services without being charged a transaction fee. The amount deducted is the cost of the item or service being purchased.
Cash withdrawals, however, attract an upfront commission, which is deducted immediately from the available credit limit.
Another feature of the card is the opportunity to avoid interest charges by settling the outstanding balance within the stipulated period.
The bank provides an interest-free period of up to 49 days when the outstanding balance is cleared on or before the statement date.
Customers who are unable to settle the full amount at once can repay in instalments, with monthly interest charged on the outstanding balance until it is fully paid.
Co-op Credit Cards are fitted with a microchip designed to make the card difficult to copy, while transactions require the cardholder’s secret PIN where applicable.
Customers should report a lost or stolen card immediately by calling Co-operative Bank on 0703 027 000.
The card can also help customers keep track of their spending. Those who have opted for SMS alerts receive notifications when the card is used, while monthly statements provide a record of transactions.
This gives cardholders a clearer view of their expenditure and can support better monthly budgeting.
Customers who qualify for a Co-op Platinum Credit Card can also access airport VIP lounges around the world at a discounted rate.
Before travelling, cardholders can search for participating lounges at their departure airport.
At the lounge, the Platinum Credit Card is presented to staff, who process the card through the LoungeKey system to confirm eligibility. Once approved, the customer can sign where required and access the lounge.
How to apply for a Co-op Credit Card
You do not need a Co-op Bank account to apply for a Co-op Credit Card. Customers can apply at any Co-operative Bank branch countrywide.
Applicants need to provide:
- A valid identification document
- Six months’ bank statements
- The applicable card processing fee
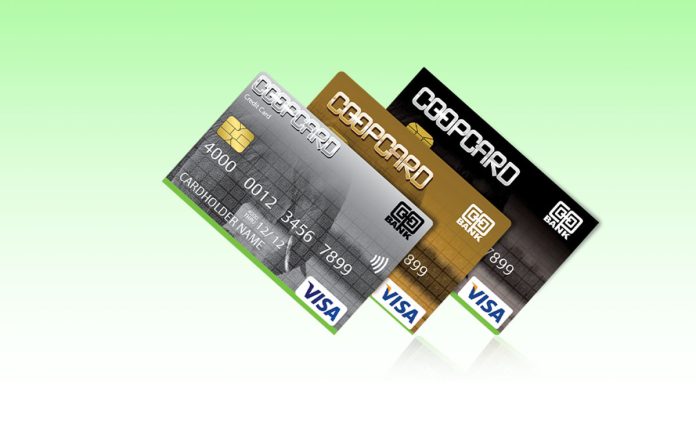
The bank offers different card options based on customer eligibility and income levels, including the Classic, Gold, Platinum and Secured Credit Cards.
Also Read: What investors need to look out for after strong H1 2026 performance by banks