Home Blog Page 158

Is Buying a Rental Property Still Profitable in 2025? A Practical Guide for First-Time Investors

0

Buying a rental property can still be profitable in 2025, but it is no longer a rising tide that lifts all boats. Returns depend on purchase price discipline, financing costs, realistic rent assumptions, and the ability to manage vacancies. The good news is that inflation in Kenya has eased into the target range, financing benchmarks are down from early 2025 peaks, and rental yields in several submarkets remain resilient. The flip side is that lending rates for households and small businesses remain elevated, and global house prices in real terms are not surging the way they did in 2020 to 2022. Put together, this means first-time investors need a methodical approach.

Below is a step-by-step playbook, with benchmarks and tools to run the numbers before you commit.

1) Read the 2025 macro signals that matter for landlords

Kenya’s annual CPI inflation was 4.5 percent in August 2025, within the official 2.5 to 7.5 percent target band. Lower and more stable inflation reduces uncertainty around rent escalation and maintenance costs.

Policy rates have trended lower through 2025. The Central Bank of Kenya reduced the policy stance during the year, and by September 2025 the commercial banks’ weighted average lending rate still hovered near 15 percent, reflecting a lagged pass-through to households and SMEs. Plan conservatively when you model mortgage payments.

Globally, real house prices are not overheating. BIS data show that real house prices fell 1.0 percent year over year in the first quarter of 2025, with advanced economies modestly up and emerging markets slightly down. This is a sign to prioritize cash flow over speculative appreciation.

Takeaway for first-timers: assume today’s financing will not be ultra cheap, assume moderate rent growth tied to inflation, and underwrite deals on cash flow, not on a hope for rapid price gains.

2) Anchor your expectations with local rental yield evidence

Independent research indicates that Kenya’s investment grade rental yields have been steady, not collapsing. For example, sector reports for 2024 show average yields in mid to high single digits across segments, with submarket selection a key driver of performance.

International vacancy and absorption patterns also remind us that supply cycles affect rents. In the United States, the rental vacancy rate reached 7.0 percent in the second quarter of 2025 as new supply came online, a cautionary example of why micro location and product fit are crucial.

Takeaway: use local yield ranges as a sanity check and verify them against actual asking rents and recent leases in your target micro market.

3) Build a conservative deal model before viewing properties

A simple cash flow model forces discipline. List the monthly rent, subtract vacancy, operating costs, and financing. Aim for a positive cash on cash return after all costs, not just a paper yield.

Start with rent and vacancy. Use recent comps, not just online listings. If you plan flexible move in dates to fill units faster, budget for prorated charges in the first and last month of a lease.

Estimate operating expenses. Include service charge, property management, routine repairs, insurance, land rates, and a maintenance reserve. Rising construction input costs often show up with a lag, so your reserve should be real.

Price your financing with a margin of safety. Use today’s actual offered mortgage rate quotes, not only the policy rate, to model payments.

Helpful tool for a quick first pass: plug your figures into a rental rental property calculator. It outputs cap rate, cash flow, cash on cash, and break even occupancy, which helps you rapidly test multiple scenarios before you ever pay for an appraisal.

4) Stress test the rent path and the exit value

Rents tend to track inflation and wage growth rather than jump unpredictably. Across OECD economies, lower income renters carry a higher risk of being overburdened by housing costs, which caps how fast rents can rise without hitting demand. Use conservative rent growth that aligns with local CPI rather than double digit hopes.

For long term value, forecast with a transparent compounding assumption. Test scenarios such as 3 to 5 percent annual appreciation over 10 to 15 years and compare them with realistic inflation baselines. A simple way to do this is using a future value calculator, which keeps expectations grounded and helps you avoid overpaying based on rosy exit numbers.

5) Plan for vacancies and mid month move ins without losing money

Vacancy is a fact of life. Two practical practices protect your return:

Proactive leasing. Start marketing 60 days before expiry and consider flexible move in windows. In markets with rising supply, homes can take longer to place, as international data on absorption of new apartments has shown.

Prorated billing. When tenants arrive or leave mid month, charging a fair daily rate preserves goodwill and prevents revenue leakage. You can compute the exact daily charge with a prorated rent calculator.

6) What good looks like for a first time deal in 2025

Benchmarks vary by neighborhood, but the following targets are a solid starting point in the 2025 environment:

Entry cap rate at acquisition equal to or higher than your realistic cost of debt. If your mortgage offer is near the mid teens, a 7 to 9 percent gross yield will not carry the deal unless expenses are extraordinarily low. Use net yield and cash on cash as the final decision metrics.

Break even occupancy at or below 85 to 90 percent. This gives you room to absorb one empty month per year without going cash flow negative.

Debt coverage ratio above 1.20 on realistic rent and expense assumptions. This is a basic safety margin that many lenders look for and that protects you when repairs run hot.

A maintenance and capital reserve set aside from day one. Older buildings can surprise you with roof, plumbing, or electrical issues that overwhelm a thin budget.

Enter these thresholds into your model and adjust until the numbers clear the bar.

7) Micro market diligence that first timers sometimes skip

Tenant profile. Match your unit type and finish level to a clearly defined tenant pool. If your target area is dominated by families, two bedroom units may have more stable demand than tiny studios.

Walkability and transport. Proximity to reliable transport and employment nodes often matters more for occupancy than cosmetic finishes. Visit at peak hours and speak to shopkeepers and caretakers.

Competing supply. Track building approvals and handovers. A flood of nearly identical apartments can stretch leasing timelines, pressure rents, and push concessions.

Property management realism. Cost out professional management and a handyman network before you buy. Cutting corners here often costs more later through longer vacancies.

8) Financing tactics in a high lending rate world

Shop widely and negotiate. Even as the policy stance eased during 2025, retail lending to households has remained elevated. Request written quotes from multiple lenders and compare the all in APR, including fees and insurance.

I guaranteed friend Sh5m Faulu loan, lost Sh32.5m property to auctioneers

Rate type and reset risk. Understand whether your loan is fixed for a period or variable against a benchmark. Ask how and when your rate can reset and recalculate your break even occupancy under that scenario.

Conservative leverage. In 2025, less debt often equals more sleep. A slightly larger down payment can bring your debt coverage ratio above safety thresholds and reduce the chance that a surprise repair pushes you negative.

9) Responsible rent setting and tenant onboarding

Price to your target return, not just to match neighbors. Use your net yield and cash on cash targets to set a rent floor that makes sense after expenses.

Offer clear prorated options for mid month leases. This is a win win. You maintain fairness and occupancy, and tenants pay only for the days they use.

Document and communicate. Provide an itemized first month statement that shows base rent, prorated days, deposit, and any utilities or service charges. This reduces disputes and speeds collections.

10) Exit strategy thinking on day one

Good landlords buy with the exit in mind. Three practical exit paths to evaluate upfront:

Hold and refinance. If rates fall and your property builds equity and a stable rent roll, a refinance can lock in better terms. Stress test this using equity growth assumptions that align with inflation and realistic appreciation.

Sell to an owner occupier or to another investor. Owner occupiers pay for lifestyle attributes while investors pay for yield. Upgrades should be targeted accordingly.

Know your tax context. Do not assume foreign style tax deferrals. Speak with a tax professional early so you do not assume benefits that are not available.

11) A simple first deal checklist

Validate market rent using three to five recent leases within one kilometer and the same unit type.

Build a conservative cash flow model that accounts for vacancy, operating costs, and realistic financing.

Stress test rent growth at CPI and at CPI minus one percentage point using current inflation as your baseline.

Compute move in prorations accurately and document them on the first invoice.

Project potential sale price scenarios with transparent, conservative appreciation rates and compare against inflation.

Recheck your deal against submarket yield evidence. If your net yield is far below the ranges indicated by independent research, renegotiate or walk away.

Bottom line for 2025

Rental property can still be profitable for first time investors in 2025, provided you buy for income rather than for speculative appreciation. Kenya’s inflation backdrop is supportive, policy rates have eased from earlier highs, and average rental yields have held up, but lending rates remain elevated and tenants are price sensitive. If you underwrite conservatively, insist on positive cash flow after a vacancy allowance, and run your numbers with the three calculators above, you can tilt the odds in your favor. Key indicators to watch as you evaluate specific opportunities include KNBS monthly CPI releases, CBK lending dashboards, BIS housing indicators, and local yield surveys that break outcomes down by unit type and neighborhood.
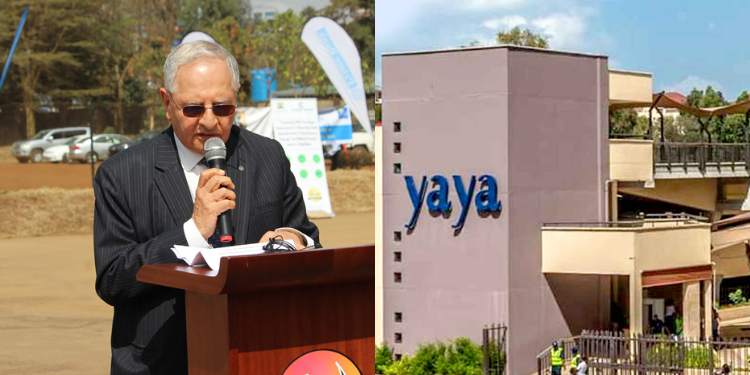
 

Billionaire family that bought Yaya Centre from Biwott family

0

Yaya Centre, located along Argwings Kodhek Road, is one of the popular shopping malls in Nairobi.

The mall was founded in the 1980s and has over the years grown to become one of the leading shopping malls, housing over 100 shops and offices.

Previously owned by the Nicholas Biwott family, Yaya Centre’s ownership was in 2023 passed to the billionaire family of Rasik Kantaria in a deal that is estimated to be worth billions.

The Kantaria family has a long-standing history of entrepreneurial success in Kenya, with their first enterprise established in the country in 1896.

The family’s legacy in Kenya began when Kantaria’s grandfather migrated from India and settled in Limuru, where he operated a small shop with the dream of his getting his family out of poverty.

Through hard work, the small retail shop expanded into a successful sawmill and charcoal-selling enterprise. Kantaria’s grandfather would later relocate to Nairobi, where he established an auto spares shop.

Meet Kenyan billionaire behind popular Qwetu and Qejani hostels

Following his grandfather’s footsteps, Kantaria entered the service industry, founding Prime Capital and Credit Finance Company, which eventually evolved into a successful commercial bank.

The family has since expanded its portfolio with investments in various sectors, including finance, real estate, hospitality, horticulture, and manufacturing, among others.

Besides Yaya Centre, the Kantaria Family reportedly has established banks in Malawi, Botswana, Zambia, and Mozambique.

The family has an aluminium factory in Mombasa and also founded the East African Building Society. Other investments include Leisure Lodge, which is one of the most exclusive hotels in the Coastal region.

Besides his entrepreneurial success, Rasik Kantaria is also known for his philanthropic work and is credited with transforming local education and healthcare.

His contributions include the Jaipur Foot Project, which has transformed the lives of over 30,000 handicapped individuals by providing them with rubber-based prosthetic legs, enabling them to lead normal lives.

He is a longstanding Rotarian and has been awarded an Honorary Doctor of Humanities Degree by The United Graduate College & Seminary for his outstanding contribution to humanity.

The billionaire holds a Bachelor of Economics degree from London.

Multichoice cuts DStv and Gotv decoder prices as subscription dips

0

Multichoice Kenya has announced a significant price reduction on its decoders and installation accessories for the festive period, running from November 1 to December 31, 2025.

The decision is aimed at attracting new subscribers as the company faces a sharp decline of more than one million subscribers in just 12 months.

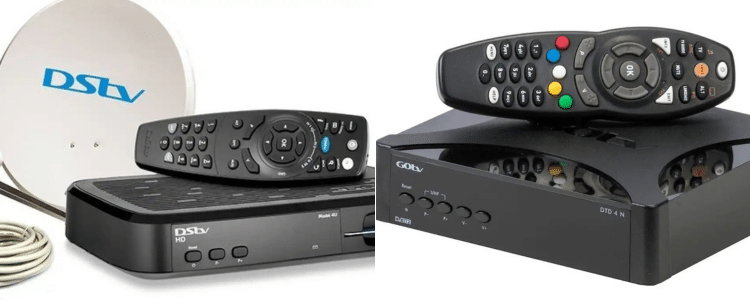
According to the new prices, the DStv Zapper Decoder will go for Sh850 down from Sh1,199 while the GOtv decoder now retails at Sh799, down from Sh999.

Prices of installation accessories have also been reduced, with the DStv dish kit going for Sh1,650 from Sh2,000, and the GOtv antenna at Sh700, down from Sh1,000. Additionally, GOtv has reintroduced the GOtv Value package, now available at Sh599.

“This festive season, we are turning every moment into a celebration by making it easier for families to connect with the content they love. These offers are our way of saying thank you to our customers for their loyalty and trust, while inviting new customers to join our growing family,” MultiChoice Kenya Managing Director Nzola Miranda said during the announcement.

The hardware offers are available at all MultiChoice Kenya service centers, authorized dealers, and retailers nationwide.

The price cuts come as the company faces a sharp decline of its subscriber base as Kenyans shift to cheaper streaming services.

Internal data indicate that active DStv subscribers plunged from 1.19 million in June 2024 to just 188,824 by June 2025, representing a loss of more than 80 percent.

Industry analysts attribute the mass exit to frequent price increases and the surge of illegal streaming platforms that offer cheap or free access to premium content.

ALSO READ: Unaitas SACCO and PesaLink partnership sets benchmark for digital inclusion in Kenya

Education Ministry scraps secondary schools categorisation, announces Sh53,000 fees

0

The Ministry of Education has announced that all Senior Secondary Schools in Kenya will charge the same annual fees from next year.

The move is in line with the guidelines on the implementation of senior schools published by the Ministry, which aim to standardize operations in these institutions.

The new guidelines have scrapped the categorisation of secondary schools based on infrastructure and location, and will see all the institutions classified on the same level, charging a standard fee.

According to the guidelines, Senior school students enrolled in boarding schools will pay Sh53,554 annually.

“The school fees to be charged for all categories of boarding school shall, for the time being, remain at Sh53,554.00 as per the Gazette Notice No. 1555 of 10th March 2015,” read part of the guidelines.

Schools are required to adhere to the annual fee guidelines issued by the ministry and seek written approval from the Cabinet Secretary for any additional levies through the County Education Board (CEB).

Additionally, fee structures must be issued at the start of the academic year, specifying vote heads such as tuition, boarding, meals, and activity fees.

In the guidelines, the Ministry of Education has also directed that Parents must be given advance notice of fee collection deadlines, with schools required to designate official payment channels. All payments must be accompanied by official receipts that clearly indicate the amount, date, and purpose.

Grade 9 learners won’t get certificates after sitting KJSEA national exams

Where necessary, schools may allow fees to be paid in instalments, provided that clear documentation of the payment plan is signed by both parties to prevent disputes and ensure that students are not denied access to education.

Moreover, schools must prepare and present annual financial reports to the Parents’ Association (PA) and BoM, detailing how funds were spent.

Grade 10 subjects and lessons

The grade ten learners will take seven subjects, including core learning areas of English, Kiswahili, and core or essential mathematics, depending on whether the learner is pursuing STEM, arts, or humanities.

A new concept, community service learning, will also be introduced. The other three subjects will be determined by the pathway chosen by the learner.

Learners will be required to have eight lessons, each lasting 40 minutes per day, and a total of 40 per week.

Mbadi: Shilling to USD should be 118 but we’re artificially keeping it 129

0

National Treasury Cabinet Secretary John Mbadi has admitted that the government is currently artificially managing the Kenya Shilling exchange rate against the dollar at 129. CS Mbadi said on Tuesday that the Kenyan currency could have strengthened to 118 to the US dollar if the government allowed it to move freely based on increased inflows of the US dollar into Kenya.

“The stability of the shilling has a basis. If it is just allowed to free fall, the shilling would even trade at 118 to the dollar. Our current account balance has been improving and our exports are doing better,” said Mbadi. This implies that the government may be deliberately keeping the shilling at a weak position against the US dollar.

For close to one year now, the local currency to USD rate has been within the range of 129 without any significant movements. This stability has raised eyebrows and questions from international bodied including the International Monetary Fund (IMF).

According to the IMF, the Kenyan currency’s rate against the dollar of between 129.22 and 129.24 since January 2025 has been too stable to be natural. This is even as the local currency weakened against the two other main currencies, the Sterling Pound and the Euro by 12 percent and 6.1 percent respectively.

According to a report that appeared in a local daily, analysts have suggested that the government is keeping the local currency weak against the US dollar by using the Central Bank of Kenya to purchase dollars from the market.

The currency’s current rate is despite the US dollar being weaker against major currencies in 2025. As at October 2025, the US Dollar had dropped nearly 10 percent against major currencies including the Euro and the Sterling Pound, placing it on course for the worst performance in a calendar year for the first time in more than 20 years.

In Kenya though, the dollar has remained steady as the government blocks the local currency from gaining against the US currency.

The shilling first took a turn for the worse after the August 2022 General Elections. Forex data from the Central Bank of Kenya shows that as at August 2022, the Shilling traded at 119.12 against the US dollar. It then went on a free fall.

READ MORE: Munga turns to wife to avoid auctioneers over multi-million ABC Bank loan

On January 15, 2024, the local currency recorded a nasty historical low after sinking past 160 to the US dollar. Later that month, it touched an all-time low of 161 on January 23, 2024. In February, the local currency made a sharp turnaround.

Between February 9, 2024 and February 29, 2024, the local currency went from 160 to 143.5. A month later, by March 28, the local currency was at 131.8, about 2 units shy of its current rate – nearly two years later.

Unaitas SACCO and PesaLink partnership sets benchmark for digital inclusion in Kenya

0

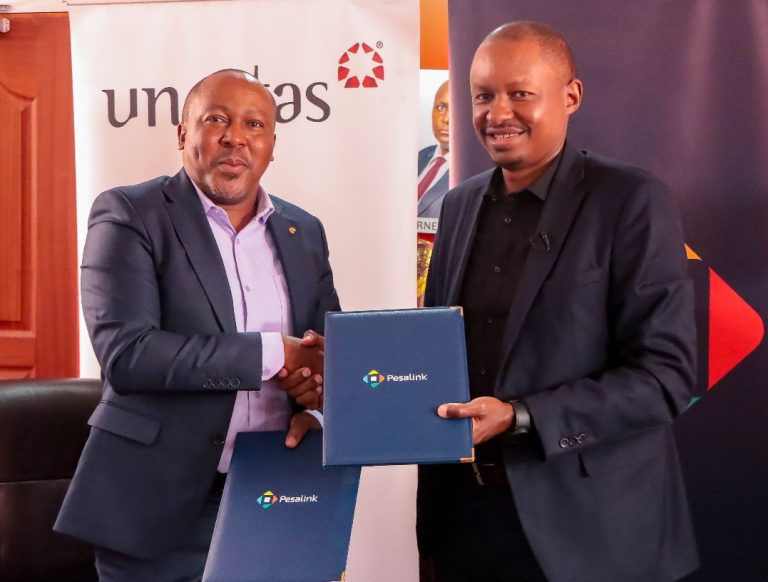
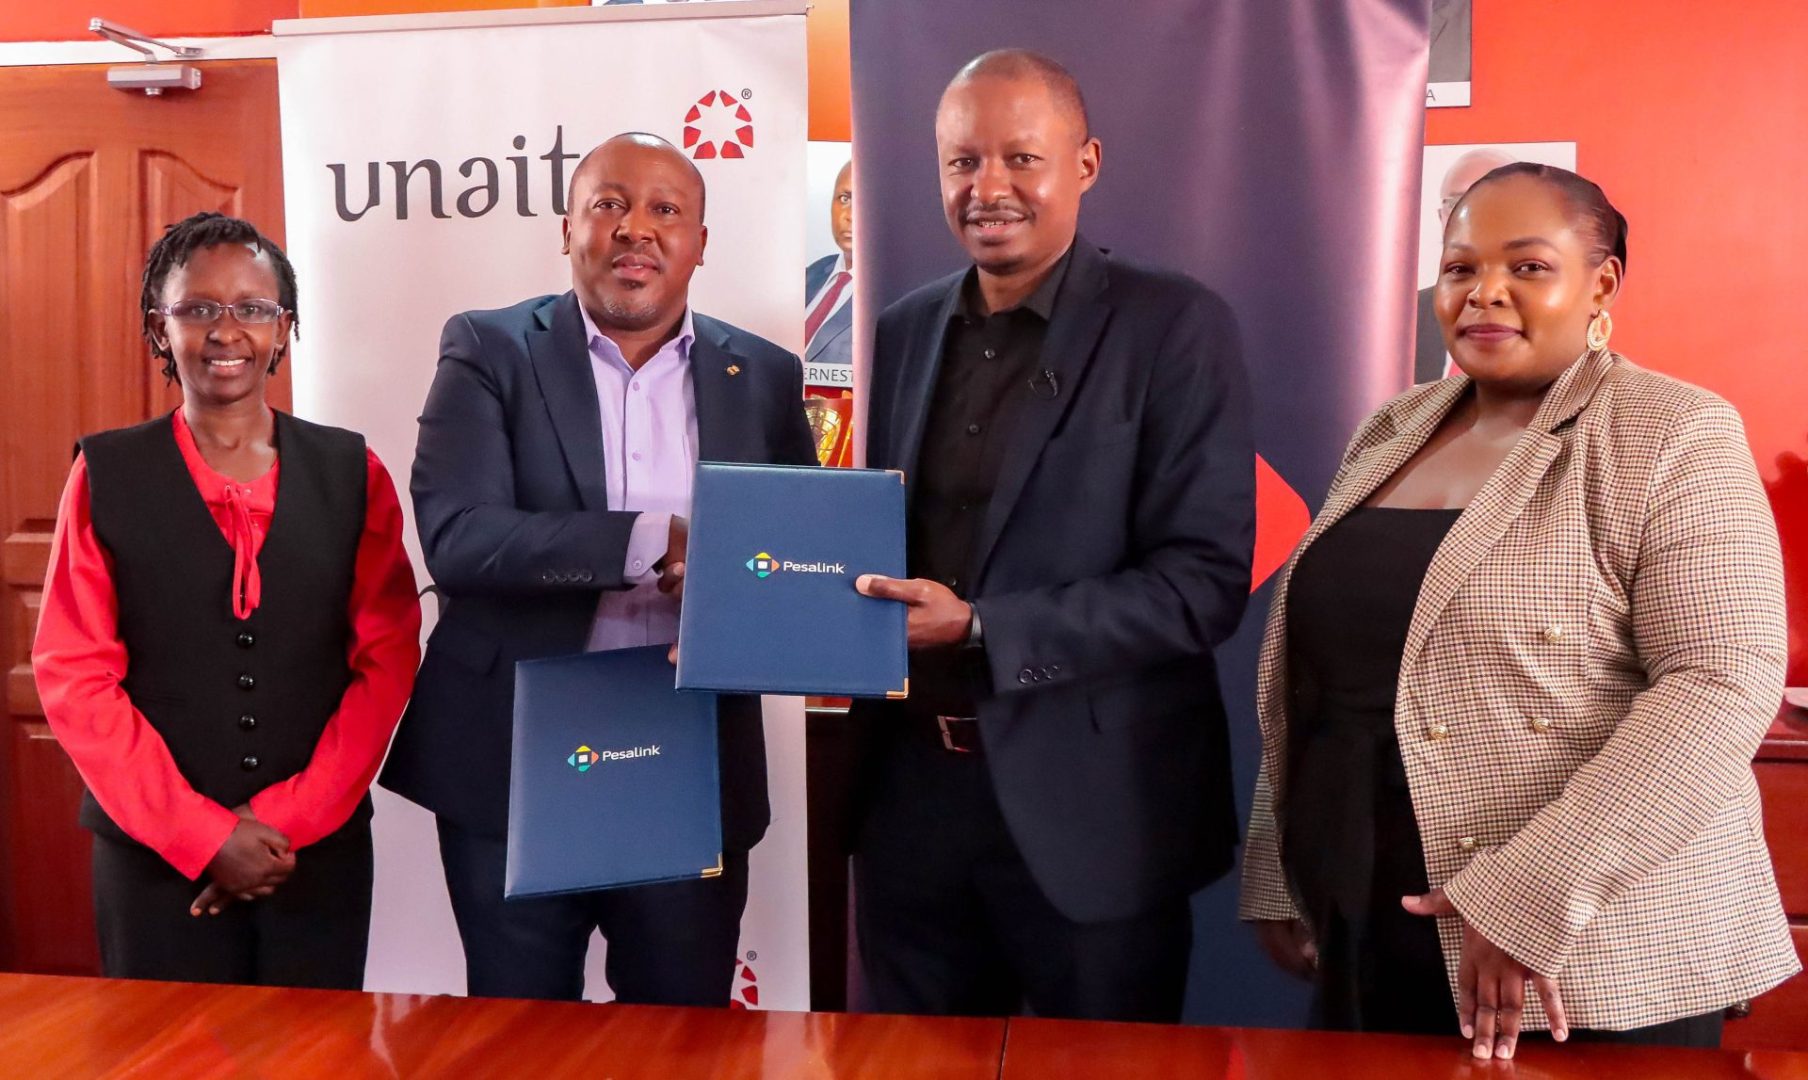
Unaitas SACCO and Integrated Payment Services Limited (IPSL), operator of the Pesalink instant payments network, today celebrated their landmark partnership, which has established a working model for digital inclusion by empowering SACCO members with instant, affordable, and seamless financial access.

The collaboration, which made Unaitas among the first SACCOs in Kenya to integrate with Pesalink, has evolved from a technology implementation to a proven blueprint for the entire cooperative movement. It is currently delivering real-time payments, simplifying transactions, and building greater trust in digital finance for Unaitas members.

The integration of Pesalink—Kenya’s de facto instant, open, and interoperable account-to-account transfer network—has transformed how Unaitas members manage their finances. With Pesalink now serving as the default instant-payment channel on Unaitas platforms, more than 400,000 members get continuous, 24/7 access to their funds. This is available via the Mo-Cash App and  USSD service on *493#, eliminating reliance on traditional banking hours.

24/7 account-to-account payments provide speed and flexibility for individuals and small businesses. A parent, for example, can pay school fees in seconds, not hours. Farmers and traders can restock or settle supplier payments after traditional business hours. Pesalink Send also provides immediate responses to a sudden financial need, without the wait for a branch to open.

“This is not just a technology launch; it’s a celebration of partnership, progress, and proof,” stated Gituku Kirika, Chief Executive Officer, IPSL. He emphasized Unaitas’ pioneering role, adding, “Unaitas was a trailblazer, and that single move has changed the narrative for the entire SACCO sector. This collaboration demonstrates how interoperable payments turn integration into impact by empowering SACCO members with instant, affordable, and inclusive access.”

Unaitas SACCO and PesaLink partnership sets benchmark for digital inclusion in Kenya

The success of the integration highlights the critical role played by the SACCO sector in Kenya’s digital-finance inclusion story. They are a powerful economic force, comprising over 14 million members and holding more than KES 800 billion in deposits (SASRA 2024).

By integrating new payment solutions like Pesalink’s Bulk for real-time payroll disbursements and Pesalink Pay for merchant and supplier settlements, Unaitas is providing the sophisticated tools needed by SMEs, agribusinesses, Chamas (informal savings groups), and institutions.

“Harnessing Pesalink means a faster, more convenient, and secure way for our members to transact instantly. For Unaitas, it means better member experience, reduced manual processing, and a stronger foundation for digital growth,” said Martin Muhoho, Chief Executive Officer, Unaitas.

How to link your Co-operative Bank accounts to PesaLink

Muhoho added that, in the spirit of cooperation, Unaitas is committed to extending its experience to other smaller Saccos. “We have worked closely with the IPSL team to design this system, and the success has encouraged other cooperatives to explore integration. This partnership shows how inclusion can be achieved through interoperability, connecting Kenya’s robust savings culture to modern digital finance.”

The collaboration is a foundational step toward a truly national fast payment system that works for banks, fintechs, and SACCOs alike, ensuring that financial inclusion is about giving people control, speed, and choice in how they manage their money.

Job interview: mistakes not to make when answering “Why are you interested in this position?”

0

Hiring managers don’t always say what’s on their minds, and sometimes this results in a less effective interviewing experience for you, the job candidate. But, regardless of how good or bad your interviewer is, you’ll very likely still get this question: “Why are you interested in this position?”

You Never Talk About the Company

When people answer, “Why are you interested in this position?” with something about being passionate about programming, writing or some other skill with no mention at all about the actual company, it’s immediately a red flag. Think about it this way: You can bring your skills anywhere. The trick is explaining why you want to use them for this particular company.

You Only Say What’s in it for You

This mistake is particularly common because, well, this is what the question is asking for, isn’t it? Maybe this job would give you the chance to learn a lot about marketing, or it’s an opportunity to grow your quantitative analysis skills—that’s great, but it’s not what your interviewer really wants to hear. At the moment, the hiring manager isn’t the most invested in what’s in it for you; he or she wants to know what’s in it for the company. The solution? Align your interests and say something about your enthusiasm for using your skills to contribute to the company’s greater goal.

Dos and don’ts: How to answer ‘What is your salary expectation’ question

You Bring Up Points That Aren’t Relevant

In the heat of the moment, it can be really tempting to reveal that the office is actually quite close to your daughter’s school or how the company’s flexible hours policy would make it easier to carpool with your roommate, but don’t give in. These are nice perks, but (hopefully) they’re not the only reason why this position is exciting for you. Plus, you’ll be giving up an opportunity to share the more relevant ones.

You Answer the Wrong Question

Have you ever gone on a date with someone who wouldn’t stop talking about his or her ex? Well, turns out this happens during job interviews, too. Don’t be that person who can’t shut up about why you need to leave your old job, stat. Even if the reason you’re job searching is directly related to your previous position, focus on the future. Bring up the skills you’ve developed for sure, but no need to dive into the history of how you acquired them.

source:themuse

Emirates marks 30 years of connecting Kenya to the world

0

Emirates, the world’s largest international airline, marks 30 successful years of flying to Nairobi, Kenya. Since the inaugural flight in October 1995, Emirates has carried over 6.6 million passengers to and from the country, on over 34,250 flights.

Served with a double daily Boeing 777 service, Emirates connects Nairobi, one of the fastest growing cities in Africa, with over 145 countries on its vast global network, facilitating trade and tourism. In the last year, key inbound traffic has been from Asia and Australasia, including South Korea, China, Thailand and Australia as well as ultra-long-haul passengers travelling from the US. The outbound traffic is similar, with travellers from Kenya visiting destinations such as Shanghai and Beijing, China; Melbourne, Brisbane and Sydney, Australia; and Seattle, New York and Washington.

Further expanding their combined footprints, Emirates and Kenya’s flag carrier, Kenya Airways, signed an interline partnership in 2023, offering seamless one-ticket-itineraries and unlocking connectivity to some of the most in-demand tourist destinations in East Africa. In the last 2 years, 31,000 passengers have taken advantage of the partnership – with almost a 50/50 balance between Kenya Airways passengers and Emirates passengers. The most popular destinations Emirates passengers travel to beyond Nairobi are Rwanda, Malawi, Tanzania (Kilimanjaro), Mozambique and Burundi.

Commenting on the milestone anniversary, Christophe Leloup, Emirates’ Country Manager for Kenya, said: “Since launch, Nairobi has been one of the most consistently busy destinations on our African network, not just with international tourists but with corporate travellers connecting with one of the continent’s major economic hubs. Over the last three decades, we have steadily and strategically expanded our operations both in the skies and on the ground to provide our renowned world-class experience in Kenya. We are proud to play a key role in Kenya’s aviation, tourism and trade journey and remain committed to the destination for the decades to come.”

Nairobi is home to Africa’s very first Emirates World travel store, which opened its doors and introduced the airline’s reimagined retail concept in 2024. Centrally located in the ultra-modern Cube, Riverside Drive, the store offers customers expert travel advice, immersive displays and the airline’s elevated experience.

Since the very first flight, Emirates has provided an outstanding passenger experience and, to date, remains the only airline serving Kenya with private, enclosed First Class cabins. The airline also offers one of the most generous baggage allowances on the market, starting at two bags at 23KG each in Economy and two bags at 32KG each in First and Business Class, per traveller. Passengers in every cabin can enjoy regionally inspired menus prepared by award-winning chefs, and over 6,500 channels of entertainment, including Kenyan movies, TV shows and music.

.Emirates set to become the world’s first Autism Certified Airline

Kenya and the UAE have deep-rooted and mutually beneficial bilateral and economic relations, headlined by the signing of a Comprehensive Economic Partnership Agreement earlier this year. Emirates SkyCargo, the airline’s freight division, has played a key role in facilitating global trade with Kenya, operating three weekly freighters into Nairobi, in addition to the bellyhold capacity in passenger aircraft. Kenya is one of the top four flower producing countries in the world, growing popular buds such as roses, carnations and chrysanthemums. In 2024, Emirates SkyCargo uplifted over 16,000 tonnes of fresh cut flowers, transporting them from farm to florist in as little as 24 hours.

Emirates also created employment opportunities, both with the 50-person strong staff in Nairobi and across its global operations. Over 1,100 Kenyans work with The Emirates Group in a variety of different roles, from HR, sales and marketing, through to flight deck. 254 of those employees work as part of Emirates’ multinational Cabin Crew community, and a further 41 are employed as pilots, travelling all over the globe with the world’s largest international airline.

Beyond its operations, Emirates supports three Kenyan humanitarian organisations focused on child welfare through the Emirates Airline Foundation. The Little Prince Nursery and Primary School provides holistic education and rehabilitation for children, and the Foundation has supported its meal programme since 2014; Alfajiri Street Kids offers a safe space and a range of programmes focusing on art therapy for more than 200 children; and finally, the Foundation sponsors four-year scholarships for 10 students at the Starehe Boys’ Centre which delivers academic support for underprivileged boys and includes a high school and multiple tertiary programmes.


Munga turns to wife to avoid auctioneers over multi-million ABC Bank loan

0

Businessman Peter Munga has managed to stall a looming auction of his Britam shares valued at over half a billion shillings over a defaulted ABC Bank loan. This is after the businessman’s wife successfully asked the court to stop the auctioning of the 75 million shares claiming that they part of matrimonial property.

Rose Njeri, who is the wife of Peter Munga, told the High Court that since the shares were part of matrimonial property, they could not be disposed of without her consent. After her petition, the High Court ruled that she had an arguable case that her husband had pledged the shares to secure loans without consulting her.

The High Court then blocked ABC Bank from auctioning the shares until Njeri’s case is heard and determined.

Munga and Njeri’s tactic follows in the footsteps of a similar tactic that has been deployed by former cabinet secretary Moses Kuria and his wife Joyce Njambi Gathungu. Kuria had also turned to his wife in April this year to block the auctioning of his property by Equity Bank over a Sh54.3 million defaulted loan.

In that petition, Kuria’s wife had claimed that the property that was up for auctioning in Ruaka and Juja which she valued at Sh100 million is matrimonial property.

In April this year, Munga had lost his bid to block auctioneers from selling off his multimillion shares over a Sh433.76 million ABC Bank loan. This was after the High Court dismissed the businessman and lashed at him for filing multiple applications in various courts in hope that one of the courts would issue orders favourable to him.

Munga had filed a fresh case at the High Court following another ruling by High Court judge Alfred Mabeya. That ruling had given ABC the green light to auction 75 million shares that he holds at Britam Kenya over the debt that he had guaranteed one of his companies.

Justice Mabeya had ruled that the loan taken by Munga’s company remains in default and as such there is no reason why ABC Bank should not attach the shares.

“In the absence of such payment, the court finds that the prayer for a permanent injunction [by Munga] preventing the first defendant [ABC Bank] and ABC Capital from realizing the security [of 75 million shares] is untenable and is disallowed,” Justice Mabeya had ruled.

READ MORE: Peter Munga wins Sh150 million court case against ex-friend Muturi

Step-by-step guide to making liquid fertilizer; benefits and shelf life

0

Fertilizers are critical to maintaining the health and vitality of crops. Two of the most common types of fertilizers are liquid and granular fertilizers.

While they both serve the same purpose of providing essential nutrients to plants, they differ in their application methods, efficiency, and cost.

Liquid fertilizers are considered the best compared to solid fertilizers due to their quick supply of nutrients to plants and cost-effectiveness.

Understanding liquid fertilizer

Liquid fertilizer is a type of fertilizer that comes in a liquid concentrate that needs to be diluted with water before being applied. Some liquid fertilizers begin as water-soluble tablets that dissolve in water first.

Unlike granular fertilizers, liquid fertilizers are typically quick-releasing, meaning they provide an immediate burst of nutrients to crops. This quick release also means that liquid fertilizers may need to be applied more frequently than granular fertilizers.

How to make liquid fertilizers

Gather organic waste

Gather organic waste, focusing on plant-based materials. Kitchen scraps (excluding meat and dairy products), yard waste like grass clippings and leaves, and even weeds can serve as the base for your fertilizer.

Roughly cut up the plant matter

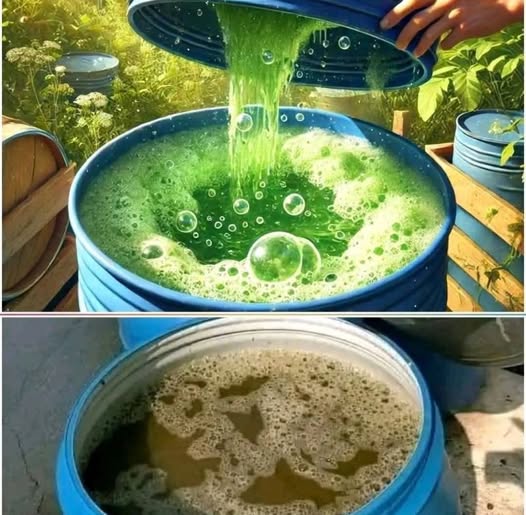
Cut the plant matter and add to a large plastic container along with about 10 litres of rainwater. The plants must be completely submerged.

Cover the mixture

Cover the mixture up but not so airtight as the fermentation process requires oxygen to work. Place the container in a shaded spot.

Leave the solution to ferment

Make sure to stir the mixture every day. Once bubbles no longer form on the surface of the liquid when it is stirred, fermentation is complete. This might take between 8 to 15 days depending on the plant used and the temperature outdoors.

Filter

Filter the liquid and the fertiliser is ready to use. If you can’t use the fertiliser right away store it in airtight containers such as bottles or jerry cans and keep it in a cool, dark place. It will then last several months.

Poultry farming: How much can a first timer make from 300 layers

Tips for making the best liquid fertiliser

  • Use rainwater instead of tap water, especially if you’re hoping for the mixture to ferment as rainwater is naturally soft. Alternatively, use water from a well or another natural source.
  • If you have to use tap water, leave it to air out for two days, taking care to stir it regularly; this will help the chlorine to evaporate.
  • Do not prepare your mixture in a metal container to prevent oxidisation. Similarly, don’t use a wooden container as this can alter the end results. Instead, use glass, plastic or terracotta.
  • When filtering, work in two or three steps. Start with a rough filter to take out the largest debris (a sieve, for example) and work your way down to one or two passes through an old insect net or pair of tights.
  •  Liquid fertiliser can be kept for a long time (up to a year) if stored in opaque, airtight containers kept in a cool spot. To ensure your fertiliser lasts, be sure to fill your containers up to the neck to prevent oxygen from getting in.
  • Do not mix plant varieties when making a plant-based liquid fertiliser. This can prevent the mixture from fermenting properly. However, you can make several different mixtures as long as you prepare them separately.