Home Blog Page 75

Embedding Project Management in Public Sector Decision-Making essential for improved development outcomes

0

Project management must be embedded more firmly within public sector policy and decision-making frameworks if Kenya is to strengthen government delivery and achieve sustainable development impact.

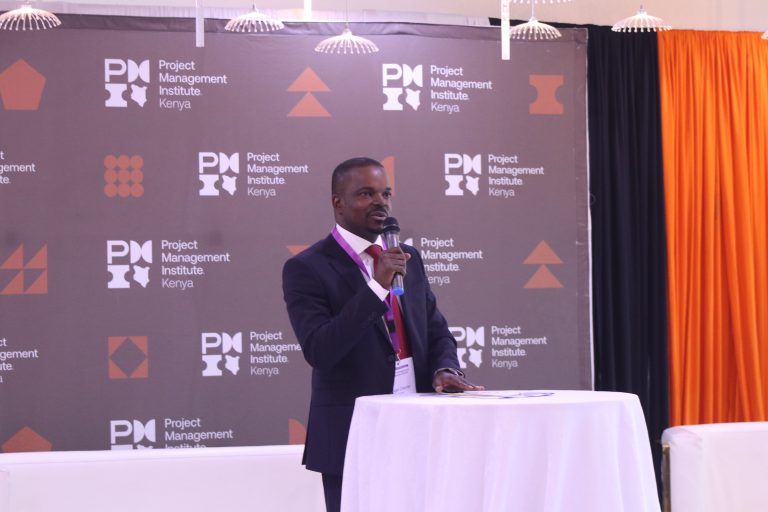
Speaking during the Government and Public Sector Industry Project Management Conference 2026 in Nairobi, Dr Sitati Olando, Head of Government Delivery (HGD), emphasized the strategic role of project management in translating national priorities into measurable outcomes, calling for stronger collaboration, greater professional influence in policy making, and more structured approaches to public sector implementation.

“Project management must occupy a stronger place in the public space. If we are to influence policy and deliver meaningful impact, we must be at the decision-making table,” said Dr. Olando.

He called on project management professionals and institutions to work collectively to elevate the profession’s role in government delivery systems, including establishing a technical team to lead discussions on integrating project management more deeply into public sector policy and implementation frameworks.

Nairobi to host Government and Public Sector Project Management conference

Dr. Olando also underscored the importance of value creation in public sector delivery, urging practitioners to leverage technology, stakeholder engagement, and collaborative approaches to improve project outcomes and service delivery.

Highlighting the profession’s growing global relevance, he challenged stakeholders to transform project management into a broader movement capable of shaping governance and development outcomes.

“We have a duty to grow this profession and expand its contribution to national development. I am encouraged by its progress and believe we can grow beyond 10,000 members. Government stands ready to support this journey,” he added.

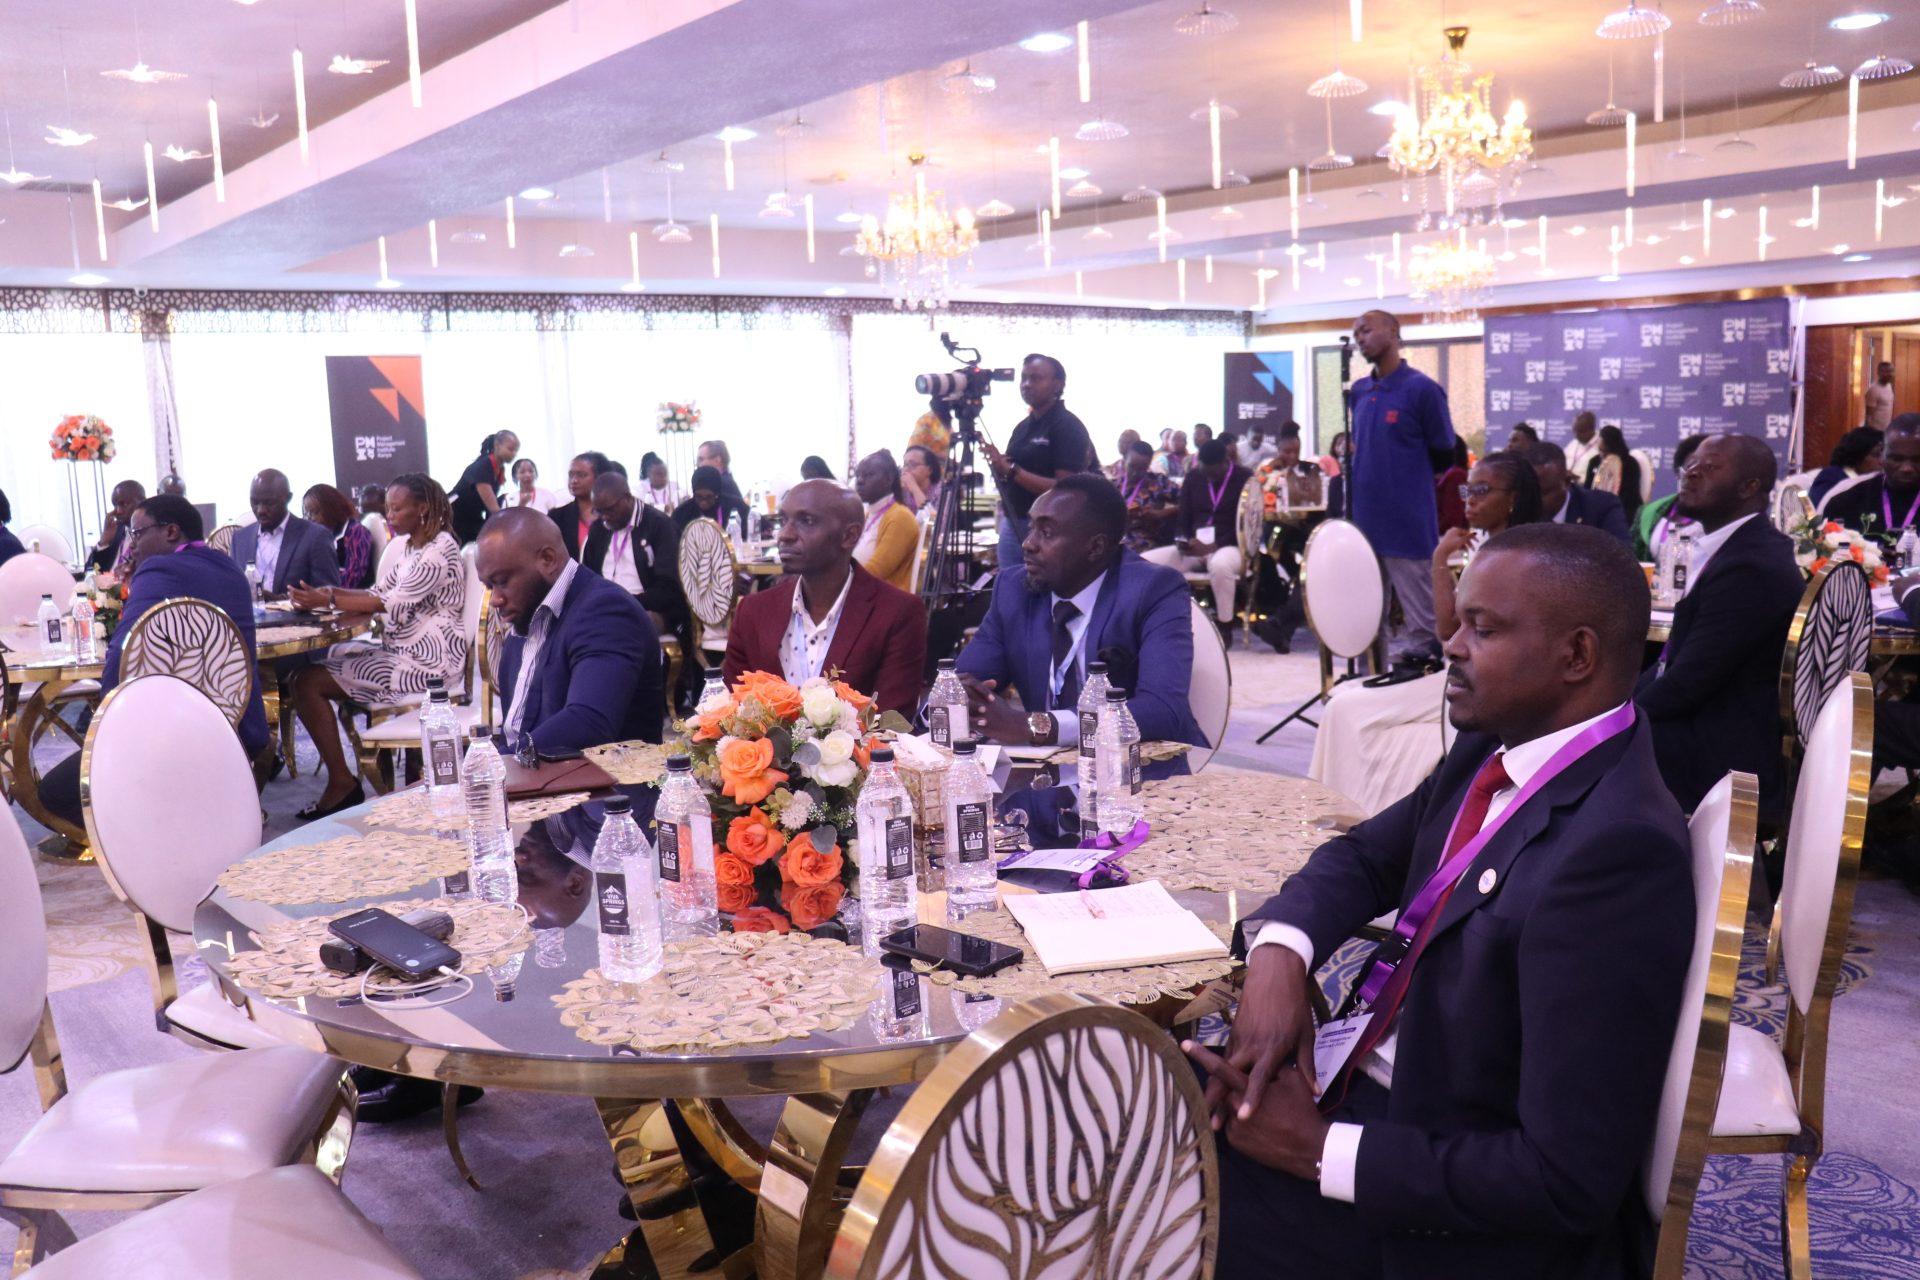
The conference, convened by PMI Kenya Chapter under the theme “Delivering Kenya’s Development Agenda Through Project Management” and the tagline “From Policy to Impact,” brought together leaders from government ministries, county governments, state corporations, development agencies, academia, and the private sector to explore ways of strengthening project delivery, accountability, and development impact.

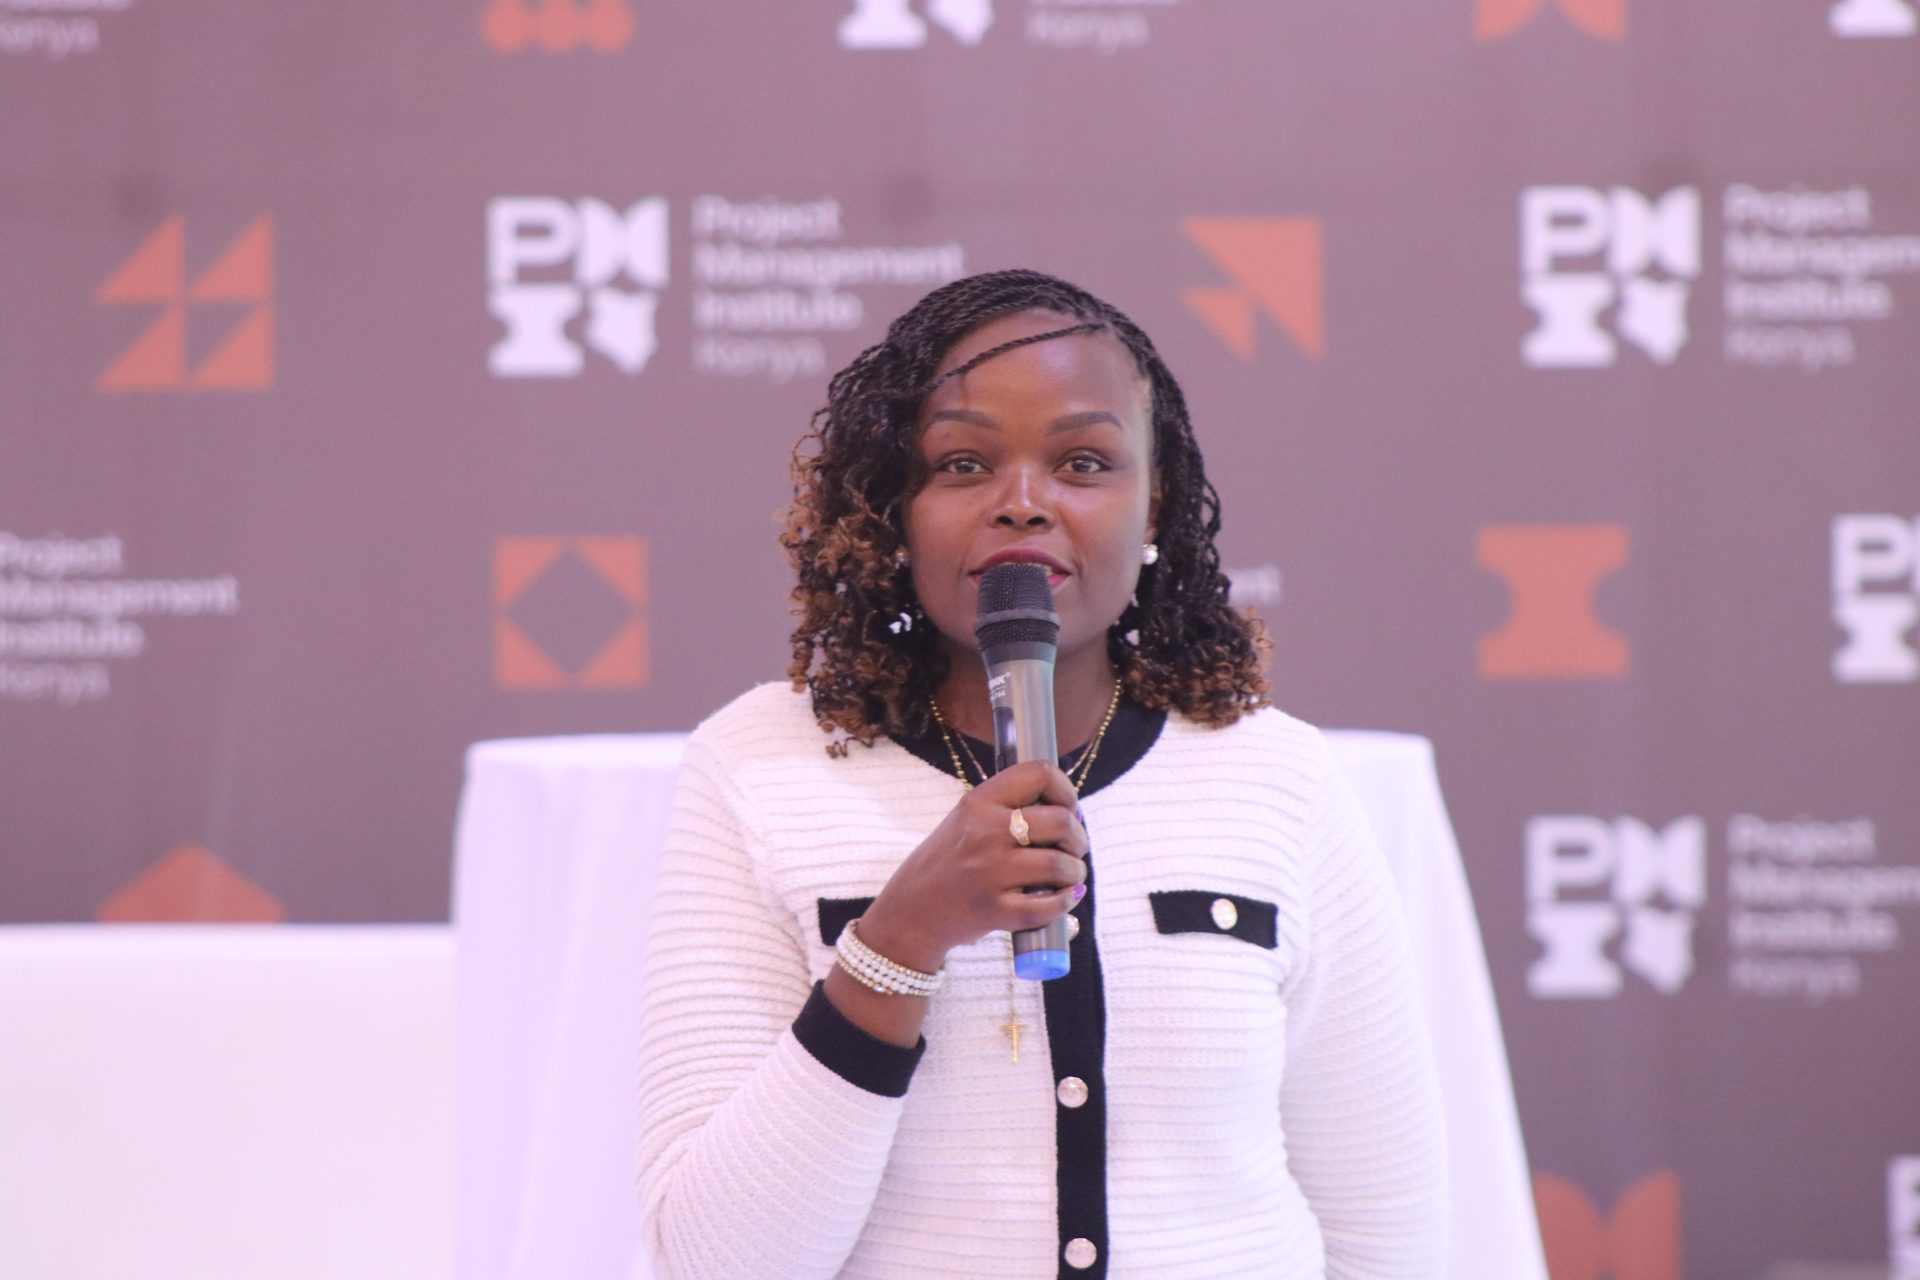
In her remarks, Maureen Ochang, President of PMI Kenya Chapter, highlighted the urgent need to strengthen execution systems within public institutions.

“Kenya has no shortage of strong policies and ambitious development plans. The challenge has consistently been execution. This conference is about equipping public sector professionals with the tools, frameworks, and networks needed to translate policy into tangible, measurable impact,” she said.

PMI launches the shift code™ podcast on project management & innovation

Ochang noted that public investment remains one of Kenya’s most important instruments for national transformation, with development expenditure accounting for approximately 30–35 per cent of government spending in recent years. However, implementation challenges continue to undermine outcomes, with studies indicating that up to 40 per cent of public projects in developing economies experience delays, cost overruns, scope changes, or fail to fully achieve their intended objectives.

According to PMI global research, organizations that adopt standardized project management practices waste 28 times less money than those that do not, highlighting the significant governance, efficiency, and public finance benefits associated with stronger project management systems.

The conference featured discussions on project governance, risk management, digital transformation, performance measurement, and accountability in public projects, with participants examining practical approaches to strengthening implementation across Kenya’s development agenda, including Vision 2030 and related national priorities.

As governments navigate increasingly complex delivery environments and rising citizen expectations, participants underscored the need to institutionalize project management as a strategic capability for public sector transformation, effective service delivery, and sustainable development outcomes.

How a simple Sh100 daily habit can help you save Sh11,000 a month

Saving money is often easier said than done. For many households, rising living costs, school fees, transport expenses, and day-to-day responsibilities make it difficult to put aside money consistently.

While financial experts continue to emphasise the importance of building a savings culture, many people still view saving as a daunting task that requires large amounts of disposable income.

However, a growing number of Kenyans are turning to simple and practical saving methods that rely more on discipline than high earnings.

One such approach gaining attention is the “Sh100 Challenge”. The challenge works by saving a fixed amount each day, increasing the amount gradually throughout the week before resetting again.

Under the model, one saves Sh100 on Monday, Sh200 on Tuesday, Sh300 on Wednesday, Sh400 on Thursday, Sh500 on Friday, Sh600 on Saturday and Sh700 on Sunday. The cycle begins again with Sh100 on Monday.

By following the routine consistently, a person saves about Sh2,800 every week. Over four weeks, the amount grows to Sh11,200. If extended to a full 30-day month, the savings rise to about Sh11,500, while a 31-day month pushes the total to roughly Sh11,800.

According to some individuals using this saving method, the cycle simplifies saving as it breaks down saving into manageable daily targets rather than demanding large lump-sum deposits.

The gradual increase also makes it psychologically easier to maintain. Instead of struggling to save thousands of shillings at once, individuals only focus on setting aside small daily amounts that match the day’s target.

The savings approach also encourages financial discipline by creating a consistent habit of setting money aside. Over time, this habit can help individuals improve budgeting skills and reduce unnecessary spending.

Another advantage is flexibility. Participants can save the money through mobile wallets, savings accounts, digital money market funds or even traditional savings boxes, depending on personal preference.

Also Read: Kenya’s Deposit Administration Funds Deliver Stronger Returns Amid Growing Retirement Savings Confidence

NALA secures $50M credit facility from Liquidity to scale global stablecoin payments infrastructure

NALA, a global stablecoin payments infrastructure company, today announced it has secured up to $50 million in credit financing from Liquidity, the global AI-driven private credit and technology provider, through Mars Growth Capital, a joint venture between Liquidity and MUFG Bank Ltd.

The initial $25 million facility offers a scale-up option of at least $50 million to provide working capital, supporting NALA’s continued global expansion, product development, and operational scaling as it builds the next-generation neobank, powered by its global stablecoin infrastructure.

The credit facility comes as NALA continues to operate from a strong balance sheet. The company still holds more than 50% of the capital from its 2024 $40m equity round, allowing Liquidity’s financing to be used strategically to accelerate growth and expand payment corridors without additional shareholder dilution.

“The financing from Liquidity validates our vision of building the definitive stablecoin payments infrastructure for the long term,” said Benjamin Fernandes, Founder and CEO of NALA. “At some point our business was more than doubling every other quarter, we grew faster than we could handle pre-funding for single direction payments and everything broke. Liquidity came in quickly and were highly flexible, so their tailored capital is a lifeline for us. It provides the cash required for NALA to pre-fund customer accounts and unlock our next phase of growth.”

Anzens and Credit Bank partner to explore crypto-based stablecoin settlement for banking in East Africa

“Our team structured a facility that accounts for NALA’s compliant stablecoin rails, real-time cross-border payments and rapid growth in emerging market corridors,” said Paul Brodie, Global Head of Investments at Liquidity. “We conducted extensive bottom-up due diligence on NALA, stress-testing the model across a range of scenarios and created a bespoke, highly scalable facility that matches the sophistication of NALA’s operations.’’

This diligence informed a hands-on structuring process, with Liquidity working alongside NALA to align capital with real-time payment flows and liquidity demands.

“At Liquidity, we partner closely with founders, working alongside teams to design financing around how companies scale in practice,” said Justin Langen, Director at Liquidity. “In NALA’s case, that meant structuring a facility that can adapt as volumes grow and corridors expand, giving them the flexibility to meet rising demand without friction. We worked closely with management to co-develop a tailored credit solution rather than relying on an off-the-shelf approach.”

Demand from enterprise customers has accelerated sharply, with NALA seeing a significant increase in B2B stablecoin payment demand over the past year alone. Liquidity’s financing gives NALA the working capital to meet this demand at scale, pre-fund larger customer accounts and onboard enterprise contracts set to go live later in 2026.

NALA secures $50M credit facility from Liquidity to scale global stablecoin payments infrastructure

The hidden costs and dangers of selling your products on credit

The constant demand for cash to settle supplier bills, pay employee salaries, pay utility bills, make loan repayments, pay rent, and even pay taxes such as Value Added Tax (VAT) and Pay as You Earn (PAYE) are realities that business owners cannot avoid in the ordinary course of operations.

Despite these cash outflows occurring regularly, many entrepreneurs find themselves in the unenviable position of limited downside resources, especially at the end of the month when the above obligations become due.

The limited cash resources that characterise many month-end seasons can be the biggest nightmare for business owners, as undercapitalised companies are tough to run.

It may come as a surprise to you, but many businesses do not collapse because of lack of profit. The main culprit is usually lack of cash.

This statement may be confusing, so I’ll explain.

As an illustration, consider the entrepreneur who manufactures cakes that cost her one thousand shillings to produce per piece, but which she sells for one thousand five hundred shillings.

If she chooses to sell the cakes on a cash basis, she will recover both the cost of production (of one thousand shillings) and the profit (of five hundred shillings) immediately she sells a cake.

If, on the other hand, she chooses to sell her cakes on credit, she will book the transactions as sales in her financial records, but she will not have received any money, since the transactions are credit sales whose payments will be received in the future. In other words, from an accounting perspective, she has made sales and recorded the associated profit, even though she has not yet received payment from her clients.

To complicate matters a little, let’s assume that cake sales are also subject to VAT and that the entrepreneur is servicing a monthly loan. You could also add payments such as salaries, electricity, rent, airtime costs, and the purchase of inventory items such as icing sugar, wheat flour, and margarine, and a clear picture of her end-of-month cash balance begins to emerge.

It can be seen that if the entrepreneur has been selling her cakes largely on credit, the end of the month will be a sure source of sleepless nights for her if she hasn’t received any money for the cakes she sold on credit.

Here is why.

For one, the taxman expects the entrepreneur to pay VAT on her credit sales (adjusted for the VAT she paid for her supplies) based on what she invoiced, rather than the actual money she collected. If the entire monthly sales of her cakes have been on credit, where is she going to get the money to pay VAT, which is paid in cash?

Secondly, we could also ask where she will get the money to settle other obligations, such as PAYE, salaries, rent, and loan servicing, if the entire monthly sales have been on a credit basis.

The point should be clear by now.

Even though the entrepreneur could be making good cake sales with healthy profit margins, her business could easily come under intense financial pressure if the majority of her sales are on credit.

The fact that she has booked strong sales with healthy margins in her financial records doesn’t necessarily mean that there is money in the bank.

If, on the other hand, the majority of her cake sales are on a cash basis, it is unlikely she will ever have trouble settling her obligations with suppliers, the taxman, employees, and her landlord, even if her profit margins are small.

One may even argue that, as long as she breaks even on her cake sales, the entrepreneur who sells her cakes on a cash basis is likely to remain in business much longer than if she chooses to sell all her cakes at better profit margins but on credit.

The lesson is clear: credit sales could be the biggest contributor to your present cash flow challenges.

However, many entrepreneurs will still go ahead and sell their products on credit even though they know that such decisions could put pressure on their cash flows or expose them to the risk of bad-debt losses.

The reasons behind this are varied, including the desire to boost sales, prevailing industry customs or traditions, the rush to beat the competition and gain a bigger share of the market, or the inability to negotiate with large buyers such as supermarkets and government agencies.

In fact, suppliers to our local supermarkets and government agencies often endure long wait times before their invoices are settled in full.

To meet the cash shortfall resulting from giving too much credit, business owners usually troop to banks to obtain facilities such as overdrafts, invoice discounting, uncleared effects facilities, and loans.

Bank overdrafts are services that allow customers to draw funds beyond the amounts actually standing in their current accounts, subject to an authorised limit. In practice, this means the bank will allow your current account to swing into negative balances whenever cash is needed.

In the case of invoice discounting, the bank undertakes to pay you a percentage of an accepted invoice in the form of a cash injection to your account when you present it to the bank. To illustrate, suppose you are one of the suppliers to our large local supermarkets, which are notorious for holding payments, in some cases for up to 6 months.

Once you have supplied your goods to the supermarket, you could arrange with your bank to pay you a percentage of the invoice amount (technically known as “discounting“) while you wait for your full payment from the supermarket. As soon as the supermarket pays the invoice amount, the bank will recover the amount it advanced to you, including its service charges, and send the remainder to your account.

The third option, known as “uncleared effects facilities“, allows customers to draw funds from their accounts even though the cheques banked have not yet matured (or “cleared“). Ordinarily, banks return cheques drawn against uncleared funds in your account, but when you sign up for un-cleared effects facilities, the bank will allow you to draw some uncleared funds in cash. In practice, this means you can draw funds from cheques deposited in your account before the mandatory three working days required to clear the cheques have elapsed.

Lastly, there are the good old loans, which, once drawn, are usually paid monthly until the entire facility is cleared. Most banks offer loans on a reducing balance basis, which means your monthly loan repayment includes both interest and principal.

If you have taken the trouble to study your loan statement, you will notice that the interest portion of your monthly loan repayment is higher than the principal portion during the early period of the loan, while the principal portion is greater than the interest portion as the loan period draws to a close.

There are pros and cons to using bank facilities.

Let’s begin with the good side.

If properly utilised, the bank facilities mentioned above can help ease financial pressure, especially during crunch times when many obligations fall due simultaneously. Many entrepreneurs would rather maintain a good reputation by spending on bank interest than lose the goodwill they enjoy with clients, landlords, employees, and suppliers. The opportunity cost of losing the benefits of these valuable business relationships pales in comparison to the inconvenience or cost of paying bank interest and fees.

On the downside, these same bank facilities can mask the inefficiencies in your business when you fail to address the root causes of your current financial difficulties.

Usually, the main culprits are failing to collect the money owed by your debtors, giving too much credit, or both.

 If this is true, then the cure for your financial troubles may not be increased access to bank facilities, but the discipline to control your credit sales and prompt collection of whatever is owed to you. In fact, rushing to the bank to obtain facilities to make up for your failures as an entrepreneur could trigger a downward spiral in the financial circumstances of your business that may leave you worse off than if you had chosen to forgo the bank facilities altogether.

Whenever you fail to manage your credit sales to the extent that the resulting strained cash flows force you to rely heavily on the support of banks, you are in effect administering the financial equivalent of steroids to keep your business afloat.

 Just as overdependence on real steroids leads, sooner or later, to adverse effects, an excessive reliance on bank facilities to make up for the shortfalls of the shoddy management of credit sales can easily lead to dire financial consequences for your firm.

The allure of readily available (and at the moment, relatively cheap) bank facilities can be hard to resist when the demands for payment from suppliers and the taxman are mounting by the day. Whenever such situations arise, you will be well advised first to examine what is owed to you, and then take the necessary steps to recover the money that is currently lying with your debtors. You may also want to consider the painful option of toning down your credit sales, especially to those star clients who take too long to pay.

Lastly, before you consider doling out credit facilities to boost your product sales, you will do well to keep in mind this adage: Turnover is vanity, profit is sanity, and cash is king.

Mr Kiriinya Kithinji is a Director of Strategy at WYLDE International. You may connect with Kiriinya via email: [email protected]

Also Read: Business strategy 101: a practical guide for entrepreneurs
Best institutions for IT training in Kenya

0

As Kenya continues to position itself as a regional technology hub, Information Technology (IT) has emerged as one of the country’s most marketable and future-driven fields of study.

From software engineering and cybersecurity to data science, networking and artificial intelligence, the demand for IT professionals is steadily rising across industries.

The rapid digitisation of banking, healthcare, education, media, transport and government services has created a strong appetite for skilled technology experts.

Kenya’s thriving innovation ecosystem, anchored by the growth of startups, mobile technology and digital finance, has further increased opportunities for graduates with IT skills.

Against this backdrop, universities and higher learning institutions are increasingly investing in modern ICT programmes designed to equip students with practical and industry-relevant skills.

Several institutions across the country have been hailed for offering quality training that has in turn boosted graduate employability. Among the institutions offering best IT training are:

JKUAT

Jomo Kenyatta University of Agriculture and Technology (JKUAT) has built a strong reputation as one of Kenya’s leading institutions for technology and engineering studies.

The institution offers  a comprehensive range of IT programs, spanning from certificate and diploma levels to undergraduate, postgraduate, and professional short courses.

Over the years, JKUAT has consistently produced graduates who are competitive in software development, systems engineering and telecommunications, among other emerging technology fields.

Strathmore University

Strathmore University has earned recognition for offering industry-oriented IT programmes that align with global technology trends.

Its Faculty of Information Technology offers degree, higher diploma, and professional certificate programmes that are consistently ranked among the best on the continent. Its @iLabAfrica research centre puts it at the cutting edge of African tech innovation.

Zetech University

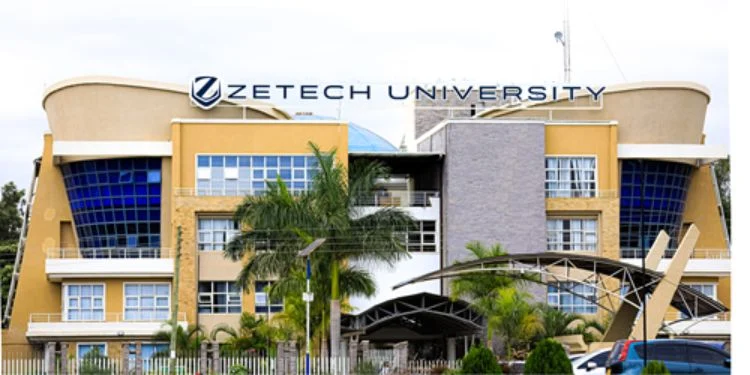
Zetech University through its School of ICT, Media & Engineering, offers a market-driven curriculum covering fields like software engineering and cybersecurity.

The curriculum blends theoretical knowledge with practical skills, ensuring graduates can address real-world business and technological challenges.

Zetech is widely known for its state-of-the-art ICT and STEM laboratories alongside interactive digital platforms that mirror modern, tech-driven workspaces.

The institution supports both traditional in-person learning and online options, giving students the flexibility to learn in ways that best suit their schedules.

Management University of Africa

The Management University of Africa offers IT training with a management focus suited for government, corporate, and NGO technology roles across Kenya.

Programmes include BSc in IT management, information systems diploma, and business computing

 Catholic University of Eastern Africa

CUEA offers specialized programs such as a Bachelor of Science in Computer Science, Diploma in IT, and various technical short courses like Python, Data Science, and Cybersecurity, designed to provide employable, hands-on skills.

Through the CUEA Innovation Hub, the institution provides students with funding, mentorship, hackathons, and corporate networking, allowing them to build real-world software and technological solutions.

“The CUEA Innovation Hub is a center of excellence dedicated to nurturing creativity, fostering technological advancements, and empowering young innovators,” CUEA states.

KCA University

Located in Nairobi, KCA offers specialized training in areas like Applied Computing, Information Security and Forensics, Gaming and Animation, and Business Information Technology.

The institution offers programs externally examined by ICDL Africa, providing globally recognized qualifications.

Kenya Institute of Management

KIM offers ICT management and business technology programmes to learners with KCSE mean grade of C- and above.

KIM programs are fully accredited by TVETA and recognized countrywide. Additionally, training is offered through physical campuses or the KIM Online Branch.

Also Read: Best universities in Kenya for Education degree courses

Why gas cylinders are covered with nets during distribution

0

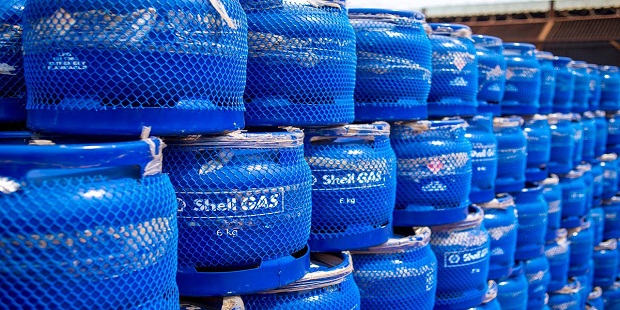
Ever wondered why gas cylinders are usually covered with nets during distribution? While some distributors ferry the cylinders uncovered, the nets play a crucial role in the safety of the highly explosive substance.

According to various media reports, one of the primary functions of the net is to maintain stability during transportation and storage.

It is important to note that gas cylinders are pressurized containers, and any sudden movement or impact can lead to accidents, leakage, or even explosions.

The net serves as a cushion absorbing shocks and preventing direct contact between the cylinder and potentially hazardous surfaces.

In addition, the protection net, made of strong threads and plastic material, has a construction that is resistant to all weather and environmental conditions.

This cushions the cylinder from physical damage, maintaining the structural integrity of the cylinder and thereby shielding it from leaks and ruptures.

India’s Adani Airports goes after 30 acres of land near JKIA

Furthermore, the nets which come in in red, black, white, blue, and yellow colours to match the colour of the tube, are made from non-corrosive materials that act as a barrier, shielding the cylinder from moisture and other corrosive elements.

The weight of this net per yard can range from 25g to 200g. It allows the tubes to breathe thanks to its pores of 10 x 20 mm and 15 x 25 mm.

The Energy, Petroleum, and Regulatory Authority (EPRA) directs that all gas cylinders be properly secured at all times to prevent tipping, falling, or rolling.

The regulator further directs gas companies to transport the cylinders using hand trucks designed for that purpose.

The cylinders should be stored in a cool, dry, well-ventilated, fire-resistant area that meets all regulations.

For the empty cylinders, the valve should be closed, the regulator removed and the valve protector cap secured in place.

EPRA warns users against using a flame to detect a gas leak; instead, they should use soapy water.

16 dead, over 70 injured in dawn dormitory fire at Utumishi Girls Academy

0

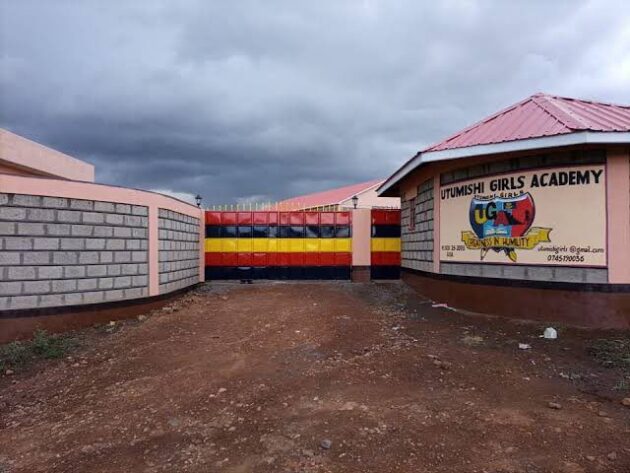
At least 16 students have been confirmed dead following a devastating overnight fire that razed a dormitory at Utumishi Girls Academy in Nakuru.

The fire reportedly broke out late at about 1 am while students were asleep, rapidly spreading through the building and causing panic within the school compound.

Reports indicate that 74 students were also injured in the incident and were hospitalised at Gilgil Sub-County Hospital and St Mark’s Hospital with varying degrees of injuries.

The affected dormitory has been identified as the Meline Waithera Block, which housed 220 grade 10, form 3, and form 4 students.

Kenya Red Cross, in a statement on Thursday, May 28, confirmed the incident adding that its emergency response teams were on ground to assist in the evacuation of the learners.

“Following a fire incident reported at around 3:30am at Utumishi Girls Academy in Nakuru County, Kenya Red Cross responded to support the ongoing emergency response,” stated Kenya Red Cross.

“Our first responders, E-Plus ambulance crew and our psychosocial support personnel are currently on the ground supporting affected students alongside other responders and relevant authorities,” it added.

Rift Valley Regional Commander, Masoud Munyi said investigations were underway to establish the cause of the deadly fire.

The school is currently conducting a headcount to ascertain the number of students present following the inferno.

Munyi said that only parents would be allowed to gain access to the school as they await reports from doctors attending to the students and investigators currently on site.

“We have not yet been able to explain exactly what happened because we are still waiting for doctors, as well as the nurses and caregivers attending to our children.”

“We also want the parents to be present so that we can talk to them, inform them about the steps we are taking, and explain the nature of the problem,” he said.

Also Read: TSC proposes new entry grades for teacher training, announces mass promotion

Equity Group emerges as most profitable Kenyan bank in Q1 2026

0

Equity Group has emerged as the most profitable banking group in Kenya and the larger Eastern Africa region in the first quarter of the current financial year 2026. This is after the banking group returned a net profit of Sh18.33 billion. This was a growth of Sh3.53 billion from the Sh14.80 billion. This net profit was derived from a profit before tax of Sh24.52 billion, which was a growth of 31.2 percent from the Sh18.68 billion profit before tax that was recorded in the same period in the previous 2025 financial year.

An analysis by Bizna Kenya shows that Equity Group grew its net profit in the first quarter of the current financial year by 23.8 percent. In contrast, its closest rival KCB Group grew its net profit for the year by 10.7 percent. KCB Group posted a net profit of Sh17.82 billion from the Sh16.09 billion that it had posted in the same period the previous financial year. This net profit was derived from a profit before tax of Sh24.43 billion.

In the quarter under review, Equity’s balance sheet expanded by 16 percent to Sh2.04 trillion, reflecting sustained momentum across its markets. Customer deposits grew by 13 percent, while net loans increased by 9 percent, pointing to continued customer confidence and steady economic activity in the region. This performance was anchored on a growing customer base of 22.7 million, backed by a wide distribution network of 86,910 agency outlets and 1.4 million merchants.

In the same period, customer deposits increased by 12.6 percent to Sh1.48 trillion from the Sh1.314 trillion that was recorded in the same quarter the previous year. The banking group’s assets increased by 16.4 percent to cross the Sh2 trillion mark and settle at Sh2.036 trillion from the previous Sh1.749 that was recorded in the first quarter of 2025.

On share price at the Nairobi Securities Exchange, an analysis by Bizna Kenya shows that Equity Group closed the quarter at Sh69 per share. This means that since the end of the same first quarter in 2025 when the share had traded at Sh47.10, Equity shareholders have gained 46.5 percent in value.

This trend of growth and profitability marks a continuation of the trend that Equity Group established in the full financial year 2025. In that full year, net profit for the bank increased to a record Sh75.5 billion. This was the highest by a banking institution in the East and Central Africa. This net profit represented a 54.7 percent growth in profit. It was derived from a full year profit before tax of Sh90.8 billion which was a growth of 51.6 percent.

READ MORE: Inside Equity’s 2025 rise to most profitable bank in East and Central Africa

In the previous full year, Equity Group had seen its total assets increase by 9.2 percent to Sh1.97 trillion from the previous year’s total of Sh1.8 trillion. Meanwhile, customer deposits grew by 4.2 percent to Sh1.46 trillion from the previous Sh1.4 trillion while loans to customers increased by 7.7 percent to Sh882.5 billion. In full year 2024, total disbursed loans had stood at Sh819.2 billion. Net interest income increased by 17 percent to Sh126.9 billion while non-funded income increased by 7 percent to Sh90.8 billion.

How I made Sh1.4 million from pig farming in one year

Pig farming is increasingly emerging as one of the most lucrative livestock ventures for smallholder farmers in Kenya, offering quicker returns, high reproduction rates and growing market demand compared to many traditional farming activities.

As erratic weather patterns continue to affect crop farming, many rural households are turning to pig rearing as a dependable source of income and financial stability.

In the rolling hills of Meteitei village in Tinderet Sub-county, 42-year-old David Kiprono is among the farmers who have successfully transformed their livelihoods through pig farming.

What began as a modest venture with only two pigs in 2019 has steadily grown into a thriving agribusiness that now supports his family and inspires other farmers in the region to reconsider conventional farming practices.

“At the time, maize farming was no longer reliable because of erratic rainfall. I needed an enterprise that could generate returns within a short period,” Kiprono says.

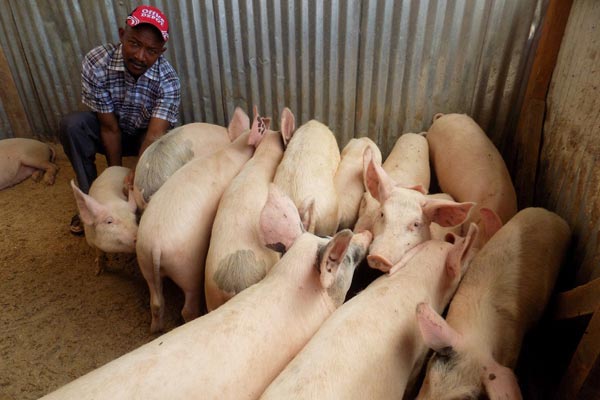
Over the last five years, his pig enterprise has expanded to 18 pigs, including four sows and one boar managed under a semi-intensive production system.

Each sow produces between eight and 12 piglets per litter, with two litters annually, giving him an estimated output of between 64 and 96 piglets every year.

Unlike cattle farming, which often requires vast tracts of land and takes years before generating substantial returns, pig farming offers faster growth and quicker income cycles.

Pigs mature rapidly, reproduce in large numbers and can be raised successfully even on relatively small parcels of land, making the venture attractive to smallholder farmers with limited resources.

Kiprono sells his pigs at an average live weight of between 50 and 60 kilogrammes, earning between Sh20,000 and Sh24,000 per animal depending on prevailing market prices.

In 2025 alone, he sold 52 pigs, generating approximately Sh1.4 million in gross revenue.

“After deducting feed and veterinary expenses, I remained with a net profit of about Sh420,000,” he says. “That is much better than what I used to make from maize farming on the same piece of land.”

The growing demand for pork has further strengthened the profitability of the venture. Kiprono says traders now visit his farm directly to purchase pigs, reducing transportation costs and market uncertainties.

“Sometimes I do not even need to transport the pigs because buyers come straight to the farm,” he explains.

Pork consumption has continued to rise in urban centres, hotels and processing industries, creating a ready market for farmers.

For Kiprono, the venture has become more than just a source of income. Proceeds from pig farming have enabled him to educate his three children, improve his family’s living standards and diversify his investments.

“I have built a permanent house and installed a water tank using income from pigs,” he says. “I am now planning to venture into dairy farming as well.”

Another advantage of pig farming is the efficient feed conversion ratio. Pigs convert feed into body weight faster than many livestock species, allowing farmers to realise profits within a shorter production cycle.

In addition, pig manure can be used to improve soil fertility and support crop farming, creating an integrated farming system. However, despite the promising returns, pig farming also presents significant challenges.

The high cost of feed remains one of the biggest obstacles facing farmers, often consuming the largest share of production expenses.

“To raise one pig to market weight requires a substantial amount of feed,” Kiprono explains. “When feed prices increase, profits reduce significantly.”

Disease outbreaks also pose serious risks to farmers. African Swine Fever, in particular, remains one of the most devastating diseases affecting pig production and can wipe out entire herds if proper biosecurity measures are not observed.

Kiprono recalls losing six pigs to disease in 2021, a setback that forced him to adopt stricter hygiene practices and improve vaccination schedules.

“We learnt through experience,” he says. “Since then, I have improved sanitation and disease control measures.”

Limited access to veterinary services and quality breeding stock continues to hinder many smallholder pig farmers, especially in rural areas.

Farmers also face price fluctuations and exploitation by brokers due to the absence of structured markets and formal supply contracts.

Nevertheless, Kiprono remains optimistic about the future of the enterprise and hopes to expand his herd to 50 pigs within the next two years.

“Pig farming has completely changed my life,” he says. “I believe many more farmers can benefit from it if they embrace it seriously.”

Also Read: Guardian Angel: Why I chose to do pig farming despite successful music career

KEMRI announces job, internship opportunities: how to apply

The Kenya Medical Research Institute (KEMRI) has announced 17 job vacancies across its research and support programmes.

The institution is offering opportunities for professionals and graduates in Kilifi, Nairobi, Suba/Mbita and Kirinyaga counties.

The vacancies, which are on contract terms, span various fields including biosciences, epidemiology, health systems research, data management, project management, medical imaging and programme support.

KEMRI is also seeking interns and research assistants to support ongoing scientific and community health initiatives.

Among the advertised positions are five vacancies for Assistant Research Officers in Biosciences, two Assistant Research Officer positions in Epidemiology, and one Assistant Research Officer role under the School Engagement Programme.

KEMRI is also recruiting two Research Officers in Bioscience, one Research Officer under the NEWRISK programme, one Research Officer in the Health Systems Unit (HSU), and two Research Officers specialising in Health Systems Evaluation and Data Analytics.

Additional openings include one Research Officer position focusing on Evaluating Hospital Workloads and Case-Mix, one Assistant Research Officer role for an Epidemiologist/Data Analyst, one Research Officer position in Data Management, and another Research Officer role in Data Management under the Wellcome Research Programme.

In Suba and Mbita, the institute is seeking two Research Assistants, while Kirinyaga has openings for a Project Manager, a Research Assistant and a Medical Imaging Technologist.

Nairobi also has a vacancy for a Program Assistant.  KEMRI is also offering two Research Internship opportunities.

How to apply

Interested applicants are required to submit applications online via the KEMRI online recruitment portal before the stated deadline.

Applications for the first batch of vacancies close on May 27, with others closing on June 1 and June 15.

“Candidates must supply an email and telephone contact that will be used when offering interviews. Only shortlisted candidates will be contacted,” KEMRI stated.

Shortlisted candidates will be required to produce originals of their National Identity Card, academic and professional certificates, original transcripts and testimonials, detailed curriculum vitae and valid clearance certificate (certificate of good conduct) during the interviews.

The recruitment drive comes as KEMRI continues to expand its health research programmes and strengthen capacity in disease surveillance, data analytics and healthcare systems evaluation.

KEMRI said the opportunities are aimed at supporting ongoing scientific research and healthcare programmes in the country, while also creating employment opportunities for skilled professionals and young researchers.

Also Read: Allan Kilavuka walks away from KQ with Sh131 million in pocket