A budget is more than a record of income and expenses. For households living on a tight monthly income, it can be an important tool for ensuring that essential needs are met while creating room for saving, investing and supporting family members.
Financial experts generally recommend giving every shilling a specific purpose and balancing present needs with future financial security.
A practical budget should cover necessities first, provide for important family obligations, allow for a modest amount of discretionary spending and, where possible, set aside money for emergencies and long-term goals.
For someone earning Sh25,000 a month, financial advisor Benjamin Cheruiyot of Abojani Investment has developed a budget that allocates income across these competing priorities while keeping the level of saving realistic.
The Sh25,000 monthly budget
According to Cheruiyot, someone taking home a net salary of Sh25,000 should divide it into four broad categories:
Needs — Sh15,000 (60 per cent): This includes Sh7,000 for rent in a suburban area, Sh4,000 for food, Sh2,000 for transport and Sh2,000 for airtime and utilities.
Parents — Sh3,000 (12 per cent)
Wants — Sh2,000 (8 per cent)
Saving and investing — Sh5,000 (20 per cent)
Cheruiyot cautions against increasing the saving and investment allocation beyond Sh5,000 while earning Sh25,000 a month.
Although saving more may appear attractive, he argues that putting too much pressure on a limited income could leave an individual struggling to meet basic expenses.
“Don’t invest more than this until your income grows, else you’ll be stressed,” he states.
The first priority: build an emergency fund
For the first 14 months, Cheruiyot recommends putting the entire Sh5,000 monthly saving into a Money Market Fund (MMF).
At an assumed annual return of 9 to 10 per cent, regular contributions of Sh5,000 could accumulate to around Sh70,000 before accounting for interest after 14 months, bringing the saver close to the Sh75,000 target.
He recommends using the accumulated funds for emergencies to reduce reliance on expensive short-term loans when emergencies arise.
From month 15: introduce SACCO savings
Once the emergency fund has been substantially built, Cheruiyot recommends changing the way the Sh5,000 monthly allocation is used.
From the 15th month, the amount can be divided equally between the MMF and a SACCO:
Sh2,500 — Money Market Fund: This continues to strengthen the emergency reserve.
Sh2,500 — SACCO: The money goes towards building savings and deposits in a stable SACCO.
At Sh2,500 a month, a member would contribute Sh30,000 over 12 months, excluding any returns or other SACCO considerations.
Cheruiyot notes that such savings may help a member qualify for a loan, depending on the SACCO’s specific rules and lending requirements.
Under the example he gives, Sh30,000 in deposits could support eligibility for a loan of up to Sh90,000, assuming a three-times-deposit lending arrangement.
At an indicated rate of 1 per cent per month, such borrowing could potentially be directed towards acquiring an income-generating asset or paying for skills development.
The approach, however, requires discipline. Borrowing should be considered only when repayment can comfortably fit within the monthly budget and when the money is being used for a clearly defined purpose.
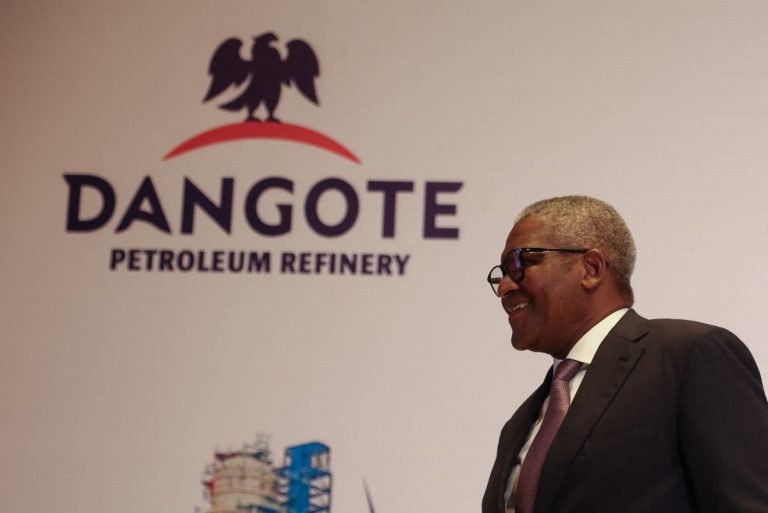
Kenyans can now invest in the Dangote Petroleum Refinery after Africa’s largest oil refinery opened its initial public offering (IPO), allowing retail investors to buy shares through their mobile phones.
The offer, which opened on September 14, 2026, will run until October 13, giving investors nearly a month to submit applications.
Nigerian billionaire Aliko Dangote is offering about three per cent of the refinery to the public in a share sale targeting up to $2.1 billion (about Sh272 billion). If fully subscribed, the transaction would rank among the largest initial public offerings on the African continent.
Each share has been priced at ₦525. Kenyan investors can apply for a minimum of 10 shares, with additional applications made in multiples of 10. Based on the indicative exchange rate provided in the offer guide, the minimum investment is approximately Sh550.
The funds raised will help finance the refinery’s expansion plans. Dangote Group intends to double the facility’s processing capacity to 1.4 million barrels of crude oil per day over the next three years.
The share sale will also support the group’s plans to increase its ownership of the refinery and strengthen its access to capital markets in the future.
How Kenyans can invest in the Dangote IPO
Kenyans seeking to participate in the offer can apply through MyStock Africa using a mobile phone.
The first step is to open an account on the platform and deposit funds in Kenyan shillings. The money is then converted into US dollars before the investor selects the Dangote IPO.
The investor can subsequently indicate the number of shares they wish to purchase, subject to the minimum requirement of 10 shares and the stipulated multiples for additional applications.
Once the application is submitted, the funds are held in escrow while the allocation process is completed. Applying for a particular number of shares, however, does not guarantee that the investor will receive the full amount requested.
If demand exceeds the number of shares available, the IPO will be oversubscribed and investors may receive a smaller allocation than they applied for.
Any money left over because of a reduced allocation will be returned to the investor’s MyStock Africa wallet.
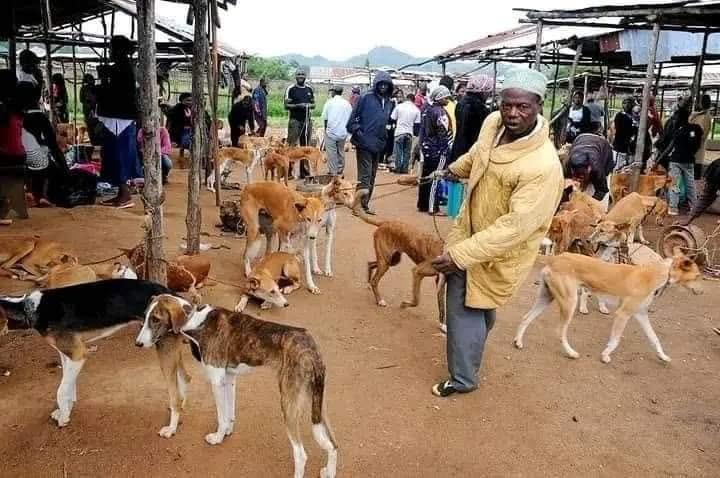
By Thursday morning, Lubao takes on a different rhythm. Along the market lanes in Malava, Kakamega County, dogs bark from the ends of ropes as their handlers lead them through the crowd, while prospective buyers stop to inspect their size, build and temperament.
Traders negotiate over prices, buyers move from one animal to another and the otherwise ordinary shopping centre comes alive with the unusual business of buying and selling dogs.
For generations, Thursday has been market day at Lubao, a trading centre synonymous with dogs. Unlike many rural markets where cattle, goats and sheep dominate the livestock section, dogs have long occupied a special place here.
Now, the indigenous dog trade is reportedly showing signs of a comeback, with traders saying demand for local breeds remains steady despite the growing popularity of exotic breeds and changing tastes among Kenyan pet owners.
The dogs on sale are largely valued for their usefulness. A buyer looking to protect a homestead may be interested in a large and alert dog.
A farmer may want one capable of guarding livestock. Others look for animals believed to have the stamina and keen sense of smell needed for tracking.
Traders say an indigenous dog can fetch between Sh2,000 and Sh3,500, depending on factors such as size, maturity, appearance and perceived ability.
Previous accounts from the market have recorded even wider price variations, particularly for mature or highly sought-after animals.
Over the years, Lubao has attracted traders and customers from across western Kenya and beyond. Reports from the market have documented sellers sourcing dogs from areas including Nandi and Uasin Gishu before bringing them to Kakamega for sale.
A market built around dogs
The prominence of dogs at Lubao dates back in the early 1950s, when the market was already developing as a trading centre. By the 1970s, it had gained a reputation as an important livestock market, with dog auctions becoming one of its distinguishing features.
The market’s development is closely linked to increased demand for dogs due to changes in farming and the need for households to protect themselves and their livestock.
Dogs became valuable working animals in rural homes. They barked at intruders, guarded livestock and homesteads and, according to older residents, were sometimes used in hunting.
By the time modern breeds such as German Shepherds, Rottweilers and Boerboels became increasingly popular among urban dog owners, Lubao had already developed a long-standing market for indigenous dogs.
A 2013 study on dog ownership and rabies in Kakamega found that the county had several weekly dog markets, with Lubao recording the highest sales volume among them at the time — about 80 dogs a week.
From hunting companion to security guard
The role of dogs in the region has changed with the times. As hunting declined and rural lifestyles evolved, the animals’ role increasingly shifted towards guarding homes and livestock.
At the same time, the growth of towns and changing consumer preferences brought greater interest in foreign breeds.
However, for a rural household that needs a dependable guard dog but cannot afford an expensive imported breed, the local dog remains an accessible option. That may partly explain why traders believe the market continues to attract buyers.
The market also serves as a meeting point where people exchange information about dogs — from breeding and feeding to training, and the characteristics buyers should look for.
A market that has changed
Lubao’s dog market, however, has not remained untouched by change. Its surroundings and trading arrangements have evolved as the wider livestock market has expanded.
In 2019, Kakamega County modernised the market’s livestock yard in a project reported to have cost Sh10 million. The improved facility was intended to serve traders from several counties, including Kakamega, Nandi, Uasin Gishu, West Pokot and Bungoma.
The dog section has also faced challenges. A 2019 report on the market raised concerns about the treatment of dogs, including allegations that some animals were deliberately made aggressive before being offered to customers seeking guard dogs.
Beyond dog auction, the market is said to be used by veterinary officials to provide rabies vaccination and educate owners.
Getting a first VPS feels a lot like buying a first car. You know you need one. The options still blur together after the third browser tab. Shared hosting was fine for a hobby blog, sure. A real business needs more room to breathe, and more control too. This is roughly where VPS hosting for beginners starts making sense — right around the point where “just use whatever’s cheapest” stops working.
What a VPS actually costs you
Price tags look simple until someone actually digs in. A $5 plan and a $40 plan can run the exact same operating system, side by side, no visible difference on the surface. The real gap hides in CPU cores, RAM, and something providers love calling “burstable bandwidth.” Beginner VPS hosting deals often pull people in with a rock-bottom intro price, then quietly double it at renewal — month thirteen, not month one.
Backups, extra storage, dedicated IPs, control panels, and managed support can also sit outside the advertised price, adding to the monthly bill. Read the fine print. Or just screenshot the pricing page before signing up, so there’s proof later.
Support matters more than specs
Here’s the part most beginner VPS hosting guides gloss over. Then regret skipping, usually around 11 pm on a Tuesday. A cheap VPS with terrible support ends up costing more than a pricier one with people who actually answer. Servers crash for no clear reason sometimes. DNS breaks. Someone edits the wrong config file, and the storefront goes dark for forty minutes.
When that happens, response time is the only spec that matters, full stop. The marketing page won’t tell you much. Before committing to anything, run anuptime and support comparison across two or three providers — and judge it by the live chat window.
Benjamin Franklin put it neatly: “An ounce of prevention is worth a pound of cure.” Test support before you need it. Nobody wants to discover a two-hour response time while the site’s down and customers are emailing.
Setting up without losing a weekend
Easy VPS hosting doesn’t mean zero effort — nothing technical really is zero effort — but it shouldn’t swallow an entire Saturday either. A first setup usually breaks down into something like this:
Pick an OS image, Ubuntu or CentOS usually, based on what the app needs.
Set up SSH key access instead of leaning on a plain password.
Sort out a basic firewall first — before anything public-facing goes live.
Get the domain’s DNS records pointed at the new server’s IP.
Get the web stack up, then test it on a subdomain before you touch the live one.
Skipping step three is how servers get compromised in the first 48 hours. It happens more than most people admit out loud. A few providers, Antihost among them, bundle managed setup help right into their beginner plans — handy for anyone short on patience or nerve for terminal work.
Once that list is done, the server stops being an abstract monthly charge. It’s the thing quietly running checkout pages or client dashboards while nobody’s watching it.
Antoine de Saint-Exupéry said it nicely— perfection isn’t when you’ve got nothing more to add; it’s when you’ve got nothing left to remove. That’s not a bad standard for a first business server either. Once it’s secure, stable, and doing its job, the best VPS is often the one you barely have to think about.
A practical last word
Getting the VPS running isn’t really the finish line, and that’s worth repeating for anyone still shopping around. Most of the VPS hosting for beginners advice online focuses only on price, which misses half the picture. It’s closer to moving into a new office space, honestly. Signing the lease is one thing; running the place day to day is another. Easy VPS hosting, chosen well, means picking with the next two years in mind — not this month’s traffic spike, which will fade anyway.
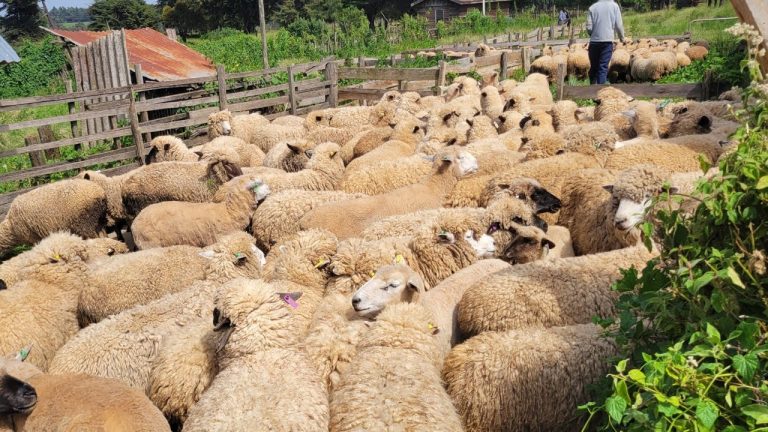
Demand for quality meat, adaptable breeds, and relatively manageable production costs are driving growing interest in sheep keeping
The animals require less space than larger livestock, can make use of available pasture and crop residues, and, with proper management, can provide farmers with regular income through the sale of lambs and mature animals.
Among the breeds attracting growing attention is the Dorper, a meat-oriented breed known for its ability to perform under relatively harsh conditions.
Dorpers are valued for their adaptability, fast growth and good meat production, making them suitable for farmers targeting the expanding demand for sheep meat.
Their hardiness and ability to utilise available forage have also made them an attractive option for both small-scale and commercial producers.
However, breed choice alone does not guarantee a profitable flock. Farmers entering sheep production need to pay close attention to breeding, feeding, housing, disease prevention and marketing.
Below are key tips every sheep farmer should master to raise a healthy flock:
Breed selection and culling determine the strength of the enterprise
A profitable flock begins with choosing animals that can consistently perform. Farmers should assess sheep based on their health, growth, fertility and ability to raise lambs.
Animals that repeatedly fall ill, remain in poor body condition or fail to care adequately for their offspring can become a financial burden.
Such animals should be identified and removed from the breeding flock rather than consuming feed and other resources without delivering returns.
Regular culling helps farmers gradually build a healthier and more productive flock.
Good nutrition before and during pregnancy can improve lambing results
Feeding management plays an important role in reproductive performance. Giving ewes adequate nutrition before mating can improve their chances of conceiving and may increase the likelihood of multiple births.
The nutritional needs of pregnant ewes become particularly important toward the end of pregnancy.
Providing additional energy during the final weeks helps support foetal growth and prepares the ewe for milk production after lambing.
Keep housing simple, dry and well ventilated
Sheep do not require elaborate housing, but their shelters should protect them from rain, strong winds and prolonged exposure to damp conditions.
The sleeping area should remain dry, with clean bedding and adequate airflow. Poor ventilation combined with wet and dirty surroundings can create conditions favourable to respiratory diseases, including pneumonia, while persistent moisture can contribute to foot problems.
Responsible parasite control saves money and slows drug resistance
Regularly administering deworming medicine without determining whether treatment is necessary can become an expensive and ineffective practice.
More importantly, excessive use of the same drugs can contribute to parasite resistance, making future treatment less effective.
Farmers should instead monitor their animals for signs of parasite problems and use appropriate veterinary guidance when treatment is required.
Rotating grazing areas can also reduce parasite pressure, while keeping feed and water troughs clean and raised off the ground helps limit contamination.
The first hours and days can determine whether a lamb survives
Newborn lambs require close attention immediately after birth. One of the most important steps is ensuring that each lamb receives colostrum, the ewe’s first milk, soon after delivery.
Colostrum provides essential nutrients and antibodies that help the young animal develop immunity.
Farmers should also disinfect the newborn’s navel using iodine or an appropriate antiseptic to reduce the risk of infection.
Close observation during the first few days allows farmers to identify weak lambs or animals that are struggling to suckle before their condition deteriorates.
Balanced feed, water and minerals support growth and flock health
Successful sheep production depends on more than simply providing pasture. Animals need adequate quantities of nutritious forage, reliable access to clean water and appropriate mineral supplementation.
Farmers should ensure that feed resources are sufficient for the size of the flock and adjust feeding according to the animals’ stage of production.
Ewes carrying lambs, lactating mothers and growing lambs may have higher nutritional requirements than other animals.
For breeds that produce substantial amounts of wool, regular shearing is also important. Removing excess wool helps animals cope with heat and reduces the risk of fly-related problems, including maggot infestations.
Farm records can reveal which animals generate income and which consume it
Record keeping is a simple management tool that can have a significant effect on profitability. Farmers should document lambing dates, birth weights, treatments, feed expenditure and other important events.
These records make it easier to identify fast-growing animals, productive mothers and recurring health problems. They also help farmers determine the actual cost of raising their sheep and identify areas where money is being lost.
Without reliable records, it can be difficult to tell whether a flock is genuinely profitable.
Buy healthy stock and sell strategically
Farmers looking to expand their flocks should be cautious when purchasing breeding stock. Animals that appear inexpensive may be in poor condition or carrying diseases that could spread to an established flock.
Where possible, farmers should source sheep from reputable breeders or farms and inspect animals carefully before bringing them home.
New purchases should also be managed responsibly to reduce the risk of introducing infections into the existing flock.
Marketing should begin well before animals reach sale weight. Farmers can plan breeding and finishing schedules around periods when demand traditionally rises, including festive seasons, when the market for sheep meat may strengthen.
The objective is to have market-ready animals when buyers are actively seeking quality stock.
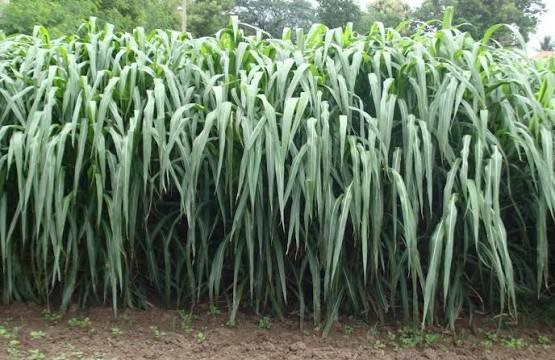
Gibert Melli, a Kitale-based farmer, is now reaping big from Napier grass farming on his six-acre farm after quitting maize farming.
The farmer makes at least Sh2m per year from Napier grass as opposed to the Sh900,000 he made from maize over the same period. In a good season, the farmer would harvest 50-90Kg bags of maize per acre, which he sold at Sh3,000 per bag.
He, however, saw an opportunity for big money in Napier grass after extensive research guided by the Kenya Agriculture and Livestock Research Organisation, KALRO.
He grows the high-yielding clone 13 variety that is also resistant to snow mold. He harvests about 10 tons of Napier grass per acre every two months and sells it to dairy farmers in the region at between Sh5,000-Sh6,000 per ton.
Growing Napier Grass
Experts recommend the use of the Tumbukiza method when planting the grass as it results in higher yields of better quality feed.
This method involves digging pits in which to plant the grass. The pits are filled with a mixture of topsoil and manure, which provides the plants with the nutrients they need to grow.
Several varieties of Napier grass are suitable for the Tumbukiza method, including Bana, Clone 13, French Cameroon, and Pakistan Hybrid.
Farmers can obtain planting material from research institutions, other farmers, or the Ministry of Agriculture.
Apply compound fertilizer (NPK: 20-20-0), 1 teaspoon per hole at planting time. Apply NPK (20-10-10 or 20-20-0) fertilizer during heavy rains at the rate of 4 teaspoons per plant. Additional topdressing may be done using CAN at the rate of 1 teaspoon per plant after cutting.
For pests and diseases, control by removing infected material and planting resistant varieties. Harvesting should be done 3 to 4 months after planting when the Napier is about one metre high.
A woman has shared that she is always broke by the fifth of every month, despite taking home a net salary of Sh150,000.
The woman, a single mother of two children aged eight and two, lives in Nyandarua and is seeking advice on how to put her income towards buying a plot and eventually building a home.
Her financial situation was shared by Benjamin Cheruiyot, a financial advisor at Abojani Investments, on his X account.
According to the woman, identified as July, her monthly expenses include a Sh50,000 loan repayment, Sh5,000 in Sacco savings, Sh10,000 in a chama, Sh5,000 sent to her mother, Sh18,000 for shopping, Sh10,000 rent and Sh10,000 for a househelp.
She also spends Sh24,000 on school fees per term, leaving the remaining amount to miscellaneous expenses.
Despite earning Sh150,000 each month, July said she finds herself without money as early as the fifth day of the month and wants a financial plan that can help her acquire property.
Responding to the matter, Cheruiyot said the figures suggest that the problem is not necessarily her income but a lack of control over part of her expenditure.
He noted that about Sh34,000 could not be accounted for in the stated budget. If left unchecked, this would amount to Sh408,000 a year—money that could instead contribute towards her property goal.
He advised July to identify the expenses hidden under the miscellaneous category, which can include transport, fuel, airtime and data, online purchases, eating out and financial assistance to friends and relatives.
According to Cheruiyot, the first step towards investing should be to close these spending gaps and establish where every shilling is going.
He also questioned the purpose of the Sh50,000 loan and urged her to establish whether it was taken for a property purchase, home improvements or consumption. Knowing the outstanding balance would also help determine how best to manage the debt.
Cheruiyot further advised her to reconsider the Sh10,000 monthly chama contribution. While she is putting away Sh15,000 through the chama and Sacco combined, he noted that such savings may not be readily available when she needs cash.
He recommended reviewing the chama’s returns and structure, particularly if it operates mainly as a merry-go-round rather than an investment vehicle. In such a case, he suggested redirecting some of the contribution towards a money market fund (MMF).
The Sh18,000 monthly shopping bill was another area he identified for review. With food prices and household needs varying, he advised the mother to examine her kitchen expenses, plan meals and consider buying produce directly from farmers’ markets where possible.
“Sh 18K food shopping appears a lot in “Potato County” With two young children and a househelp, examine leaks in your kitchen. You can cut costs by purchasing directly from farmers’ markets,” he advised.
To make progress towards her property goal, Cheruiyot proposed setting up separate sinking funds for school fees and the planned plot purchase.
He suggested making automatic transfers immediately after payday so that saving becomes a priority rather than relying on whatever money remains at the end of the month.
Under his proposed budget, Cheruiyot advised her to set aside Sh50,000 for loan repayment, Sh5,000 Sacco contribution, Sh10,000 rent, Sh10,000 househelp, and Sh5,000 support for her mother.
Other proposed allocations include Sh5,000 for Chama contribution; Sh10,000 for shopping; and Sh10,000 for miscellaneous.
The revised budget would bring monthly spending to Sh113,000, leaving Sh37,000 for saving and investment.
Cheruiyot’s proposed allocation of the surplus is Sh20,000 a month towards a property fund, Sh8,000 towards school fees and Sh9,000 towards an emergency fund.
If maintained for 24 months, the property fund would accumulate Sh480,000, while the school fees fund would reach Sh192,000 and the emergency fund Sh216,000.
The approach would give July separate funds for her major financial obligations while creating a dedicated pool of money for her long-term goal of purchasing land.
Cheruiyot also advised her to compare her total chama contributions with the expected payout and assess whether the arrangement is delivering meaningful returns.
If the benefits are unclear after reviewing the arrangement, she could reconsider her participation during the next cycle.
Kenyan commercial banks are increasingly shifting their lending strategies from traditional primary production to value addition, aiming to plug local small and medium-sized enterprises (SMEs) into global supply chains.
Leading this strategic pivot is Equity Bank, which is accelerating its push to transition grassroots businesses from raw material producers to competitive players in the global market.
This accelerated push was the focal point during a recent high-level business dinner held between Equity Bank’s executive leadership, the Narok County Government, and the local business community. Once heavily anchored on the Maasai Mara National Reserve and rain-fed wheat farming, Narok is rapidly transforming into a formidable commercial hub, serving as a blueprint for this new wave of local enterprise development.
Equity Bank Managing Director Moses Nyabanda noted that the focus must shift toward “smart agriculture” and market linkages to unlock the true wealth of local enterprises.
“We are seeing farmers adopting smart agriculture, moving away from how our forefathers farmed,” Mr. Nyabanda said. “But we do not just want to increase yields; we want to connect you to the market. If you are a livestock farmer, we want to see how we can link you to markets that buy processed leather for designer bags, rather than selling raw hides for a fraction of the price.”
To further de-risk the agricultural sector, which remains highly sensitive to weather patterns, Mr. Nyabanda committed to aligning loan disbursement timelines strictly with local crop cycles, assuring farmers of a two-week turnaround time for agricultural credit to ensure planting seasons are not missed.
This focus on targeted capital deployment is driven by rapid, multi-sectoral economic expansion in regions outside traditional urban centers.
“Narok is not a small market to us,” noted Kagiso Moloi, Equity Bank’s Commercial Director. “Livestock business is growing, trade is growing, and tourism is growing. People in Nairobi may not realize how fast this region is expanding. Our job is to fund that growth and move money quickly and safely.”
To sustain this momentum and build capacity for global export, lenders are deploying aggressive asset finance and unsecured credit lines to stimulate local enterprise.
“If you want a tractor or a commercial truck, we are ready to support you with up to 105 per cent financing,” said Carol Rutto, Equity Bank Kenya’s Head of Retail and Branch Business. “We are also offering unsecured loans of up to Sh10 million without requiring you to pledge any collateral at the bank. Our doors are open to serve you exactly how you need.”
Historically, access to credit in agrarian regions was stifled by stringent collateral requirements, locking many out of the commercial supply chain. Okipira Ole Tutai, a veteran farmer who began his agribusiness journey in 1985, recalled how state-backed agricultural financiers strictly demanded title deeds, a near impossibility for young farmers in communally held land systems.
“From 1985 to 1994, I had never received a loan anywhere. With state financiers, you had to have a title deed, which we didn’t have as young men. There was simply no way to access credit,” Mr. Tutai recalled. The entry of flexible, cash-flow-based lending altered this landscape, allowing farmers like him to scale from subsistence to commercial operations, eventually acquiring tractors and commercial real estate.
This flexible approach to banking has also been crucial for insulating SMEs from macroeconomic shocks. Education investors in the region noted that strategic interventions such as loan moratoriums were the lifeline that prevented mass closures of private educational institutions during the Covid-19 pandemic. By putting loan repayments on hold until the economic environment stabilized, institutions were able to survive the crisis and later leverage bank financing to acquire land and build infrastructure.
However, as credit uptake increases, so does the conversation around loan recovery, a sensitive issue in Kenya’s banking sector amid rising non-performing loans (NPLs). Speaking at the forum, Narok County Executive Committee Member for Finance, David Ole Muntet, urged financial institutions to adopt more humane default management strategies.
“Borrowing is a wedding, but paying back can feel like a funeral,” Mr. Muntet remarked. “While people must pay their loans, we urge banks to find better approaches to handling defaulters rather than immediately auctioning properties. There is always a way out.”
TikTok has become an important platform for creators, entrepreneurs, businesses, media companies and influencers looking to reach large audiences.
But building an audience on TikTok also comes with an important responsibility: understanding the platform’s Community Guidelines.
A post can be removed or flagged within seconds of being uploaded. In some cases, creators may receive a warning even when they did not intend to violate TikTok’s rules.
I recently experienced this myself.
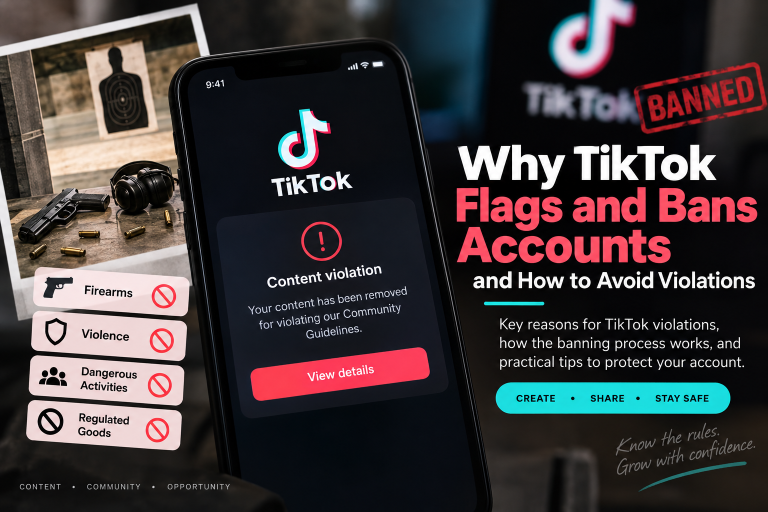
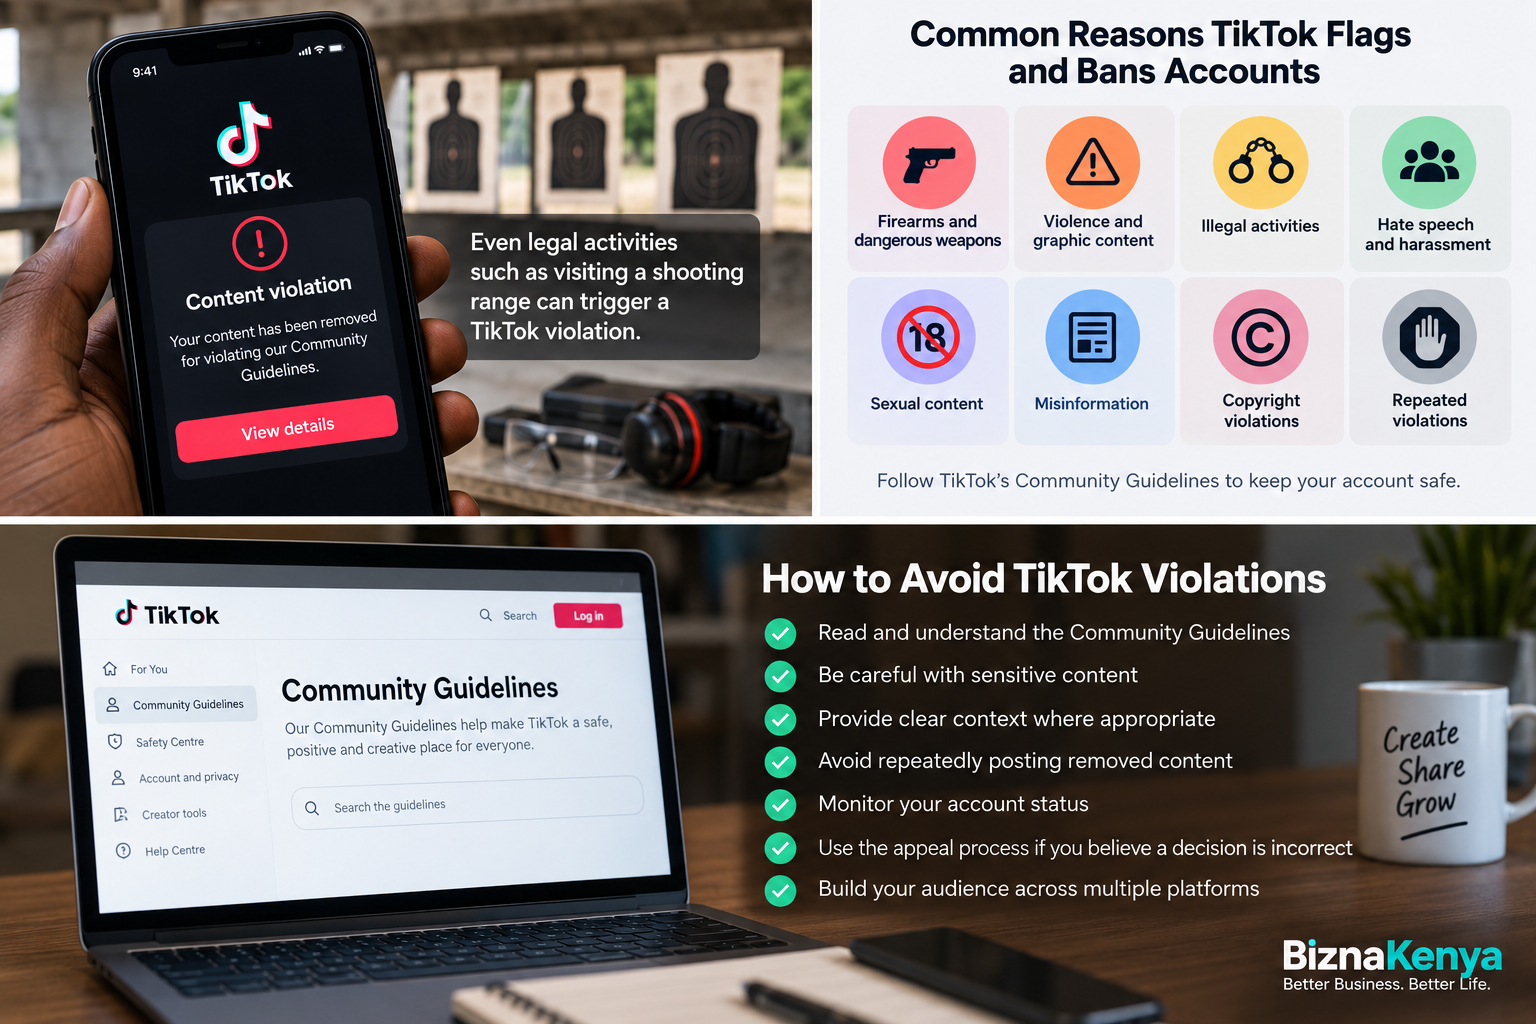
I posted pictures I had taken at a gun shooting range. The photographs were simply documenting my experience at the range. I was not selling a firearm, promoting violence or encouraging anyone to use a weapon.
Almost immediately, TikTok issued me a violation warning.
The experience highlighted an important lesson for anyone building an audience on TikTok: what a creator intends to communicate is not necessarily how an automated moderation system interprets the content.
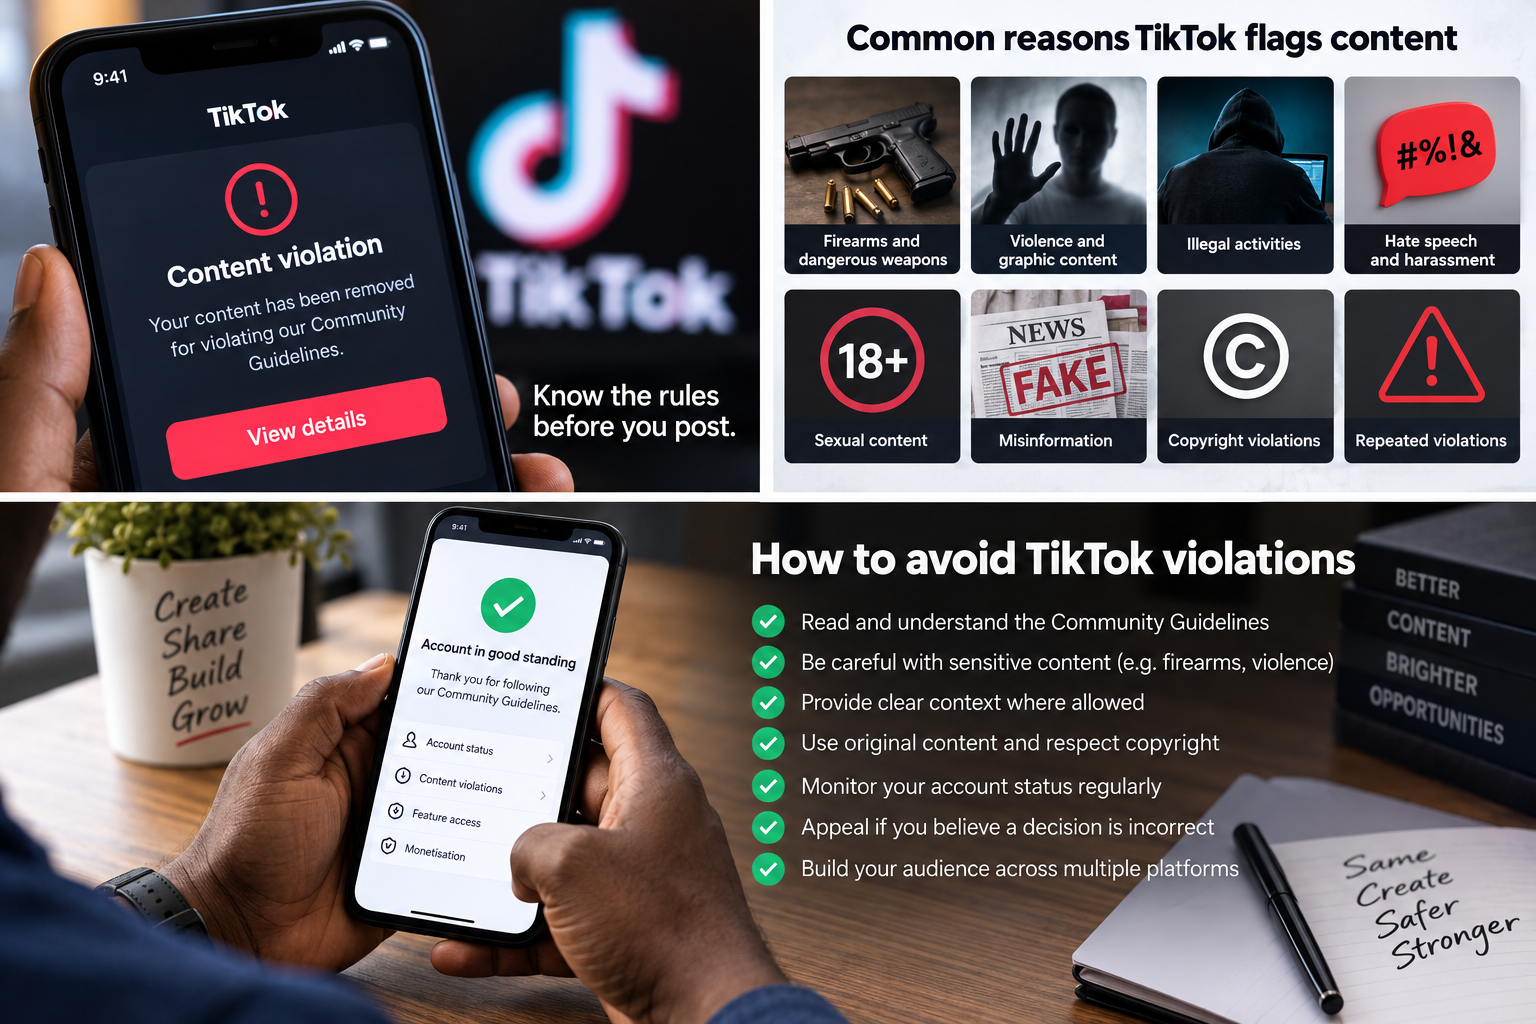
TikTok’s Community Guidelines cover a broad range of subjects, including violence, dangerous activities, regulated goods, illegal activities, hate speech, harassment, misinformation, sexual content and intellectual property.
TikTok has also consolidated firearms and dangerous weapons under its regulated goods and services policy.
This means that content featuring certain objects or activities can attract moderation even when the creator’s intention is not harmful.
TikTok uses automated systems as part of its content moderation process. The company said in 2025 that more than 85% of content removed for violating its Community Guidelines was identified and taken down by automation.
This helps explain why a violation notification can sometimes appear almost immediately after content is uploaded.
Why TikTok flags and bans accounts and how to avoid violations
Why shooting-range photographs can trigger a violation
A photograph taken at a shooting range may appear harmless to the person who took it.
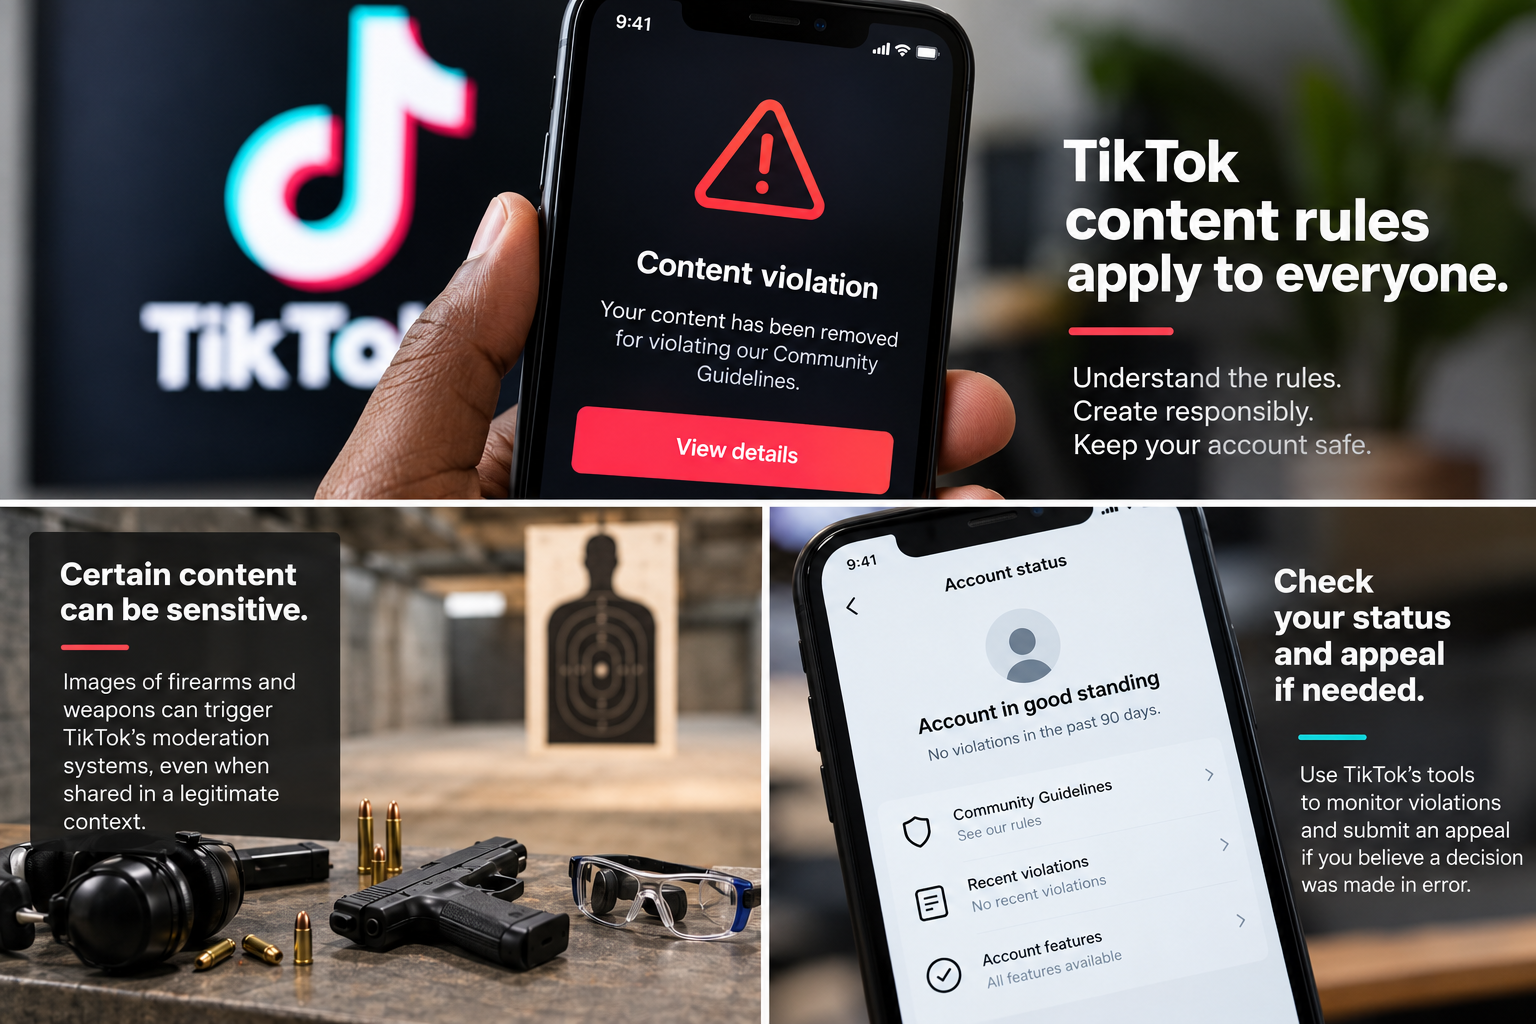
However, the presence of firearms makes the content fall into a category that TikTok treats as sensitive.
There is an important distinction between the creator’s intention and what is visually detectable.
A photograph of a firearm could potentially represent recreational shooting, news reporting, educational material, historical content, firearm promotion or content associated with violence.
Automated moderation systems have to assess enormous volumes of content, often before a human moderator has reviewed the material.
TikTok has acknowledged that automated moderation cannot be perfectly accurate and maintains an appeal process for creators who believe content has been incorrectly removed.
For creators, the practical lesson is simple: sensitive visual content should be treated carefully, even when the context is completely legitimate.
A TikTok violation does not automatically mean that an account will be permanently banned.
Depending on the nature and severity of the violation, TikTok can remove content, issue a warning, restrict certain features, issue strikes or take more serious action against an account.
TikTok’s account enforcement system uses strikes for violations. The threshold for action can vary depending on the policy involved and the potential harm associated with the violation. TikTok also says that serious violations can result in a permanent ban without going through the normal progression of strikes.
TikTok has stated that strikes expire from an account’s record after 90 days.
Why TikTok flags and bans accounts and how to avoid violations
Can TikTok permanently ban an account?
Yes.
An account can be permanently banned if it reaches the relevant enforcement threshold. TikTok can also impose a permanent ban for particularly serious violations.
The company has previously identified severe violations, such as promoting or threatening violence and certain forms of child sexual exploitation, as examples where a permanent ban can occur following a single violation.
TikTok also says that accounts accumulating a high number of strikes across different policies and features can be permanently banned.
This makes repeated violations particularly important for creators who depend on TikTok for their audience or income.
A warning is an opportunity to understand what TikTok believes went wrong.
Creators should read the violation notification carefully and identify the specific policy involved.
TikTok has also introduced tools that allow creators to check their account standing and see information about violations and restrictions. Its Account Check feature can show whether recent posts have violated rules and whether certain account features have been restricted.
Rather than simply continuing to publish the same type of content, creators should use the warning to review their content strategy.
Why TikTok flags and bans accounts and how to avoid violations
What should you do if TikTok removes your content?
If you believe TikTok has made a mistake, you can appeal.
TikTok’s current support guidance says creators can appeal an account restriction through the violation notification. The process includes going to the Inbox, System notifications, Account updates, selecting the relevant restriction and choosing Appeal.
The same principle applies to content removals where an appeal option is provided.
An appeal should explain the legitimate context clearly and factually.
For example, if a photograph was taken at a licensed shooting range, the appeal should explain that context rather than simply arguing that the creator did nothing wrong.
There are several broad categories that creators should monitor.
1. Firearms and dangerous weapons
Content involving firearms and dangerous weapons can attract moderation because TikTok treats these as regulated goods and services.
Creators should therefore exercise particular caution when posting photographs or videos showing firearms.
2. Violence and graphic content
Content that promotes, threatens or depicts certain forms of violence can result in serious enforcement action.
TikTok has identified some violence-related violations among categories that can result in permanent bans.
3. Illegal activities
Content that facilitates or promotes illegal activities can violate TikTok’s rules.
4. Hate speech and harassment
Targeting individuals or groups with prohibited hateful or abusive content can result in enforcement.
5. Sexual content
TikTok places significant restrictions on sexual content, nudity and sexually explicit material.
6. Misinformation
Certain forms of misinformation can violate TikTok’s Community Guidelines, particularly where the content creates a risk of harm.
7. Copyright violations
Creators should also ensure that they have the appropriate rights to use music, video, photographs and other copyrighted material.
8. Repeated violations
Repeated violations can be more serious than an isolated mistake because TikTok’s enforcement system considers both the frequency and severity of violations.
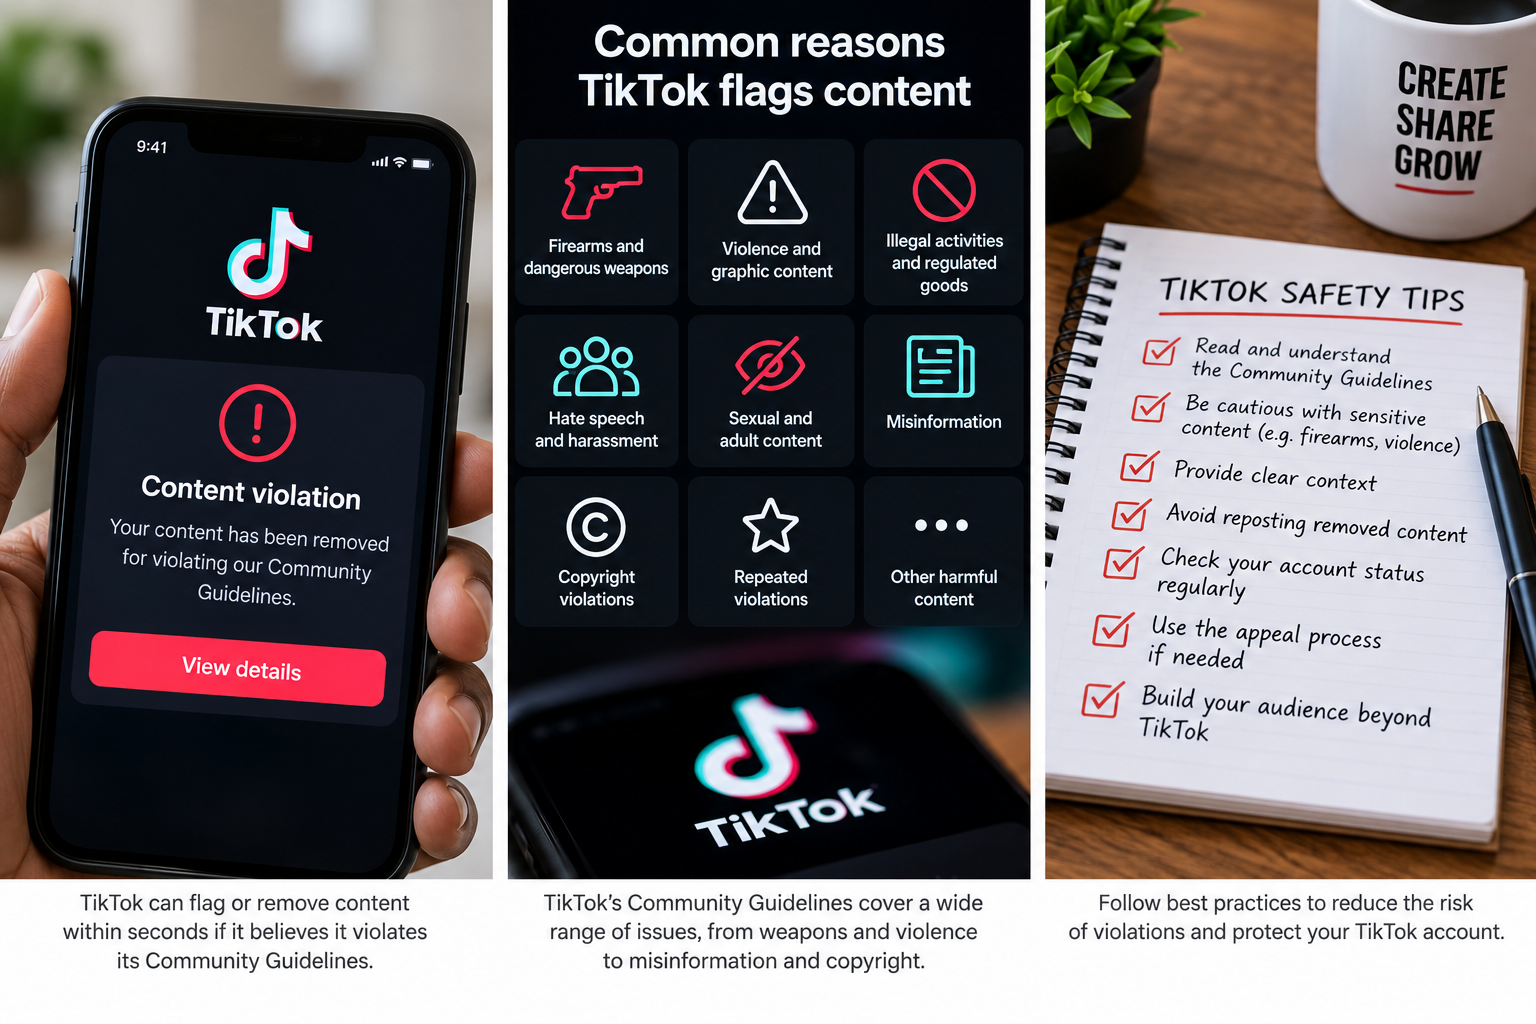
The best way to protect a TikTok account is to understand the platform’s rules before publishing potentially sensitive content.
Creators should regularly review TikTok’s Community Guidelines, particularly if their content involves regulated products, finance, health, politics, weapons, dangerous activities or other sensitive subjects.
It is also important to consider the context of photographs and videos.
If an image could easily be misunderstood, the surrounding content should make the legitimate purpose clear, where the platform’s rules permit the material.
Creators should also avoid repeatedly uploading content that has already been removed. If you believe the removal was incorrect, use the appeal process rather than repeatedly reposting the same material.
Another important habit is monitoring the account’s status.
TikTok provides tools that allow creators to see whether their content or features have been restricted.
Why TikTok flags and bans accounts and how to avoid violations
Don’t assume that a legal activity is automatically TikTok-approved
This is an important distinction.
Something can be legal in the country where it takes place and still be subject to restrictions on a social-media platform.
For example, visiting a shooting range may be a lawful activity. That does not automatically mean every photograph or video taken at the range is permitted under TikTok’s Community Guidelines.
Social-media platforms establish their own rules about what can be published and distributed through their services.
TikTok’s Terms of Service also state that it can take action where it believes users have violated its Terms, Community Guidelines or other applicable policies.
For professional creators, there is a bigger business lesson.
A TikTok account can become extremely valuable, but the account itself is not an asset that the creator completely controls.
A creator who has spent years building an audience can potentially lose access to distribution because of repeated violations or a serious policy breach.
That is why serious creators and businesses should build an audience across multiple channels.
A website, email database, customer database, newsletter, community and other direct communication channels can reduce dependence on a single social-media platform.
TikTok can provide powerful distribution, but the underlying relationship with the audience is more important.
My shooting-range experience was a useful reminder that TikTok moderation can sometimes react to what is visible in an image before the full context is understood.
The photograph may have been completely innocent from my perspective, but the presence of a firearm was enough to trigger a violation warning.
The lesson is not to avoid creating content.
It is to understand the rules of the platforms on which we build our audiences.
Creators should know what subjects are considered sensitive, monitor their account status, take warnings seriously and use the appeal process when they believe a decision is incorrect.
For entrepreneurs and businesses, there is an additional lesson: never build your entire digital audience on a platform you do not control.
Build the platform audience, but also build an owned relationship with your customers and followers.
In the long term, responsible digital entrepreneurship is not simply about gaining followers. It is about building an audience, protecting trust and creating assets that remain valuable beyond any single platform.
For much of the past two decades, Africa’s digital payments story was told through mobile money, where phones gave millions of people a practical way to send, receive and store money without depending entirely on bank branches.
That story is still growing, but governments across the continent are now taking the next step by moving taxes, permits, licences, public services and other payments away from cash, paper receipts and disconnected offices.
The change matters for a simple reason, since collecting money is only one part of the problem when governments still struggle to match a payment to the right service, account, institution and transaction record.
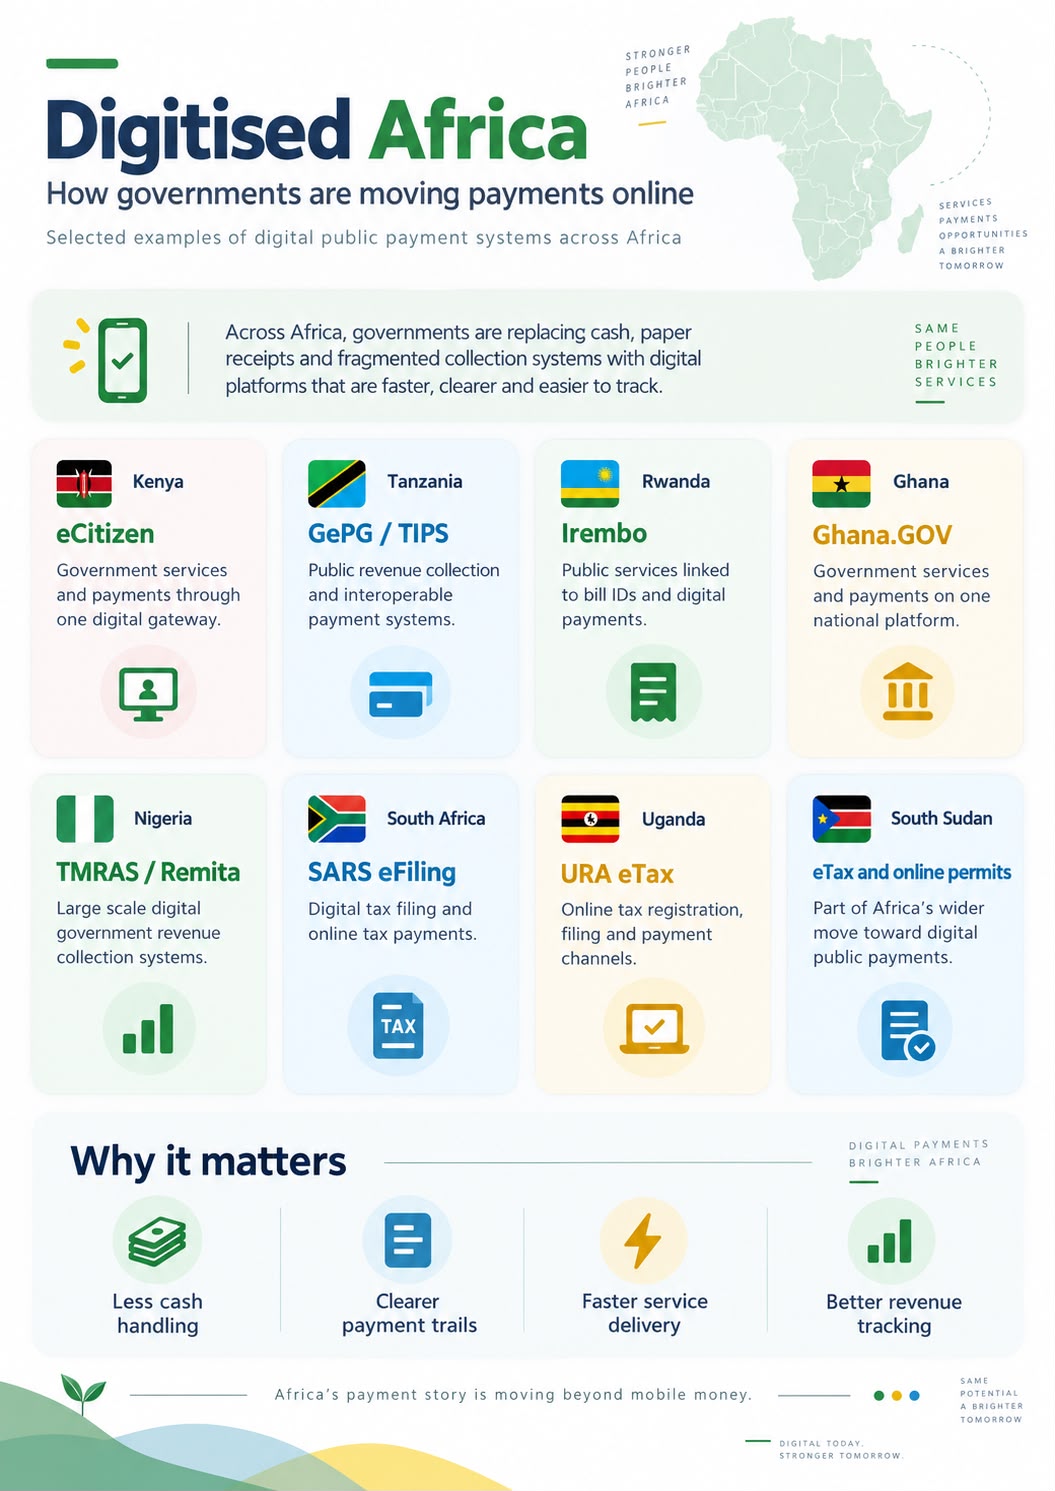
Across Kenya, Tanzania, Rwanda, Ghana, Nigeria, South Africa and South Sudan, different systems are being built around the same basic idea, where public payments should become easier to collect, easier to record and easier to check later.
Kenya Turned eCitizen Into A Government Payment Gateway
Kenya remains one of Africa’s best-known digital payments markets, where mobile money became part of everyday life long before many governments elsewhere had begun thinking seriously about digital public services.
The government later extended that thinking into public payments through eCitizen, which became a central point where citizens and businesses could apply for services and make payments through electronic channels.
The National Treasury says that before the programme expanded, more than one third of government payments were cash-based, creating room for leakage, abuse and expensive collection processes across public institutions.
The move toward eCitizen was about much more than convenience, since the government wanted to improve revenue collection, lower collection costs, and connect public services to payment records that could be followed electronically.
Once a service, invoice and payment sit inside the same system, the government can more easily check what was requested, what was charged, when the payment happened and whether the amount reached the right institution.
Tanzania Built One Gateway For Government Revenue
Tanzania approached the same problem through the Government Electronic Payment Gateway, which connects government institutions with different electronic payment channels and brings public revenue collection into a more standardised system.
The country also built the Tanzania Instant Payment System, known as TIPS, which connects banks and non-bank financial institutions through real time infrastructure that allows money to move between different providers.
During 2024, Tanzania recorded more than 453 million interoperable retail transactions worth over TZS29.9 trillion, alongside approximately 63.2 million active mobile money wallets and strong growth in merchants accepting digital payments.
The bigger lesson from Tanzania is that government digitisation works best when billing, payment channels, transaction records and settlement can be connected instead of sitting inside separate systems that barely speak to each other.
Rwanda Put Public Services And Payments Into One Process
Rwanda has taken its own route through Irembo, where people can apply for government services, receive a billing reference and complete payment through mobile money, banks or international cards.
That approach connects the service request to the payment itself, which means people do not need to move between different offices carrying receipts before the government can confirm that money has been paid.
For the government, the value sits in the record left behind, where a billing identifier, service request and completed transaction can all be connected inside the same process rather than being handled separately.
Rwanda’s system shows how government digitisation can make public services easier to access while giving institutions a clearer way to connect applications, billing information and completed payments.
How African Governments Are Moving Payments From Cash to Digital Systems
Ghana Is Bringing Government Services Onto One Platform
Ghana has followed a similar path through Ghana.GOV, where taxes, permits, certificates and other public services can be accessed and paid for through a common national platform.
The country’s wider payment market has been growing at the same time, with electronic transactions becoming a larger part of daily commerce, banking and the way people interact with public institutions.
When government services move onto the same digital rails already used by banks, cards and mobile wallets, the gap between ordinary payments and public payments becomes much smaller.
That means a citizen can increasingly expect government services to work much like other digital services, where an application, bill, payment and receipt can all be handled without visiting several offices.
Nigeria Shows What Happens When Digital Payments Reach a Huge Scale
Nigeria takes the story into a much larger market, where electronic payments now move at a scale that makes digital infrastructure part of the country’s basic economic machinery.
The Central Bank of Nigeria recorded approximately 5.63 billion instant payment transactions worth around N476.89 trillion during the first half of 2024, with web transfers accounting for the largest share of transaction volume.
Government revenue collection has gone through its own digital changes, with Remita becoming closely associated with federal payments before the Treasury Management and Revenue Assurance System was introduced as part of a newer approach.
Once payments reach that size, the challenge is no longer simply whether money can move quickly, since governments and financial institutions must also deal with reconciliation, settlement, reporting, identity and transaction records.
Nigeria, therefore, shows where many African markets are heading, where digital payments are becoming too important to sit outside the systems used to manage public revenue and national financial activity.
South Africa Has Made Tax Payments A Digital Routine
South Africa has spent years building digital tax administration through SARS eFiling, where taxpayers can submit returns, manage tax information and make payments without depending on physical branches for every interaction.
The system gives taxpayers and businesses a direct electronic relationship with the revenue authority, allowing filings, payments and account information to sit inside one connected digital environment.
South Africa has also been working on a wider payment infrastructure intended to make faster electronic transactions easier to access and more useful across the wider economy.
That matters because tax collection becomes easier to manage when filing information, payment references, and taxpayer records can be connected instead of being spread across paper files and unrelated systems.
Uganda Is Moving More Tax Services Online
Uganda has been putting more tax administration onto digital channels through the Uganda Revenue Authority, allowing taxpayers to register, file returns, generate payment information and complete transactions electronically.
Payments can be connected to registration numbers and completed through banks, cards or mobile money, giving taxpayers several ways to settle obligations without depending entirely on cash and physical collection points.
The result is the same pattern appearing elsewhere across Africa, where the government increasingly wants every important payment connected to a reference that can later be matched against the person, service or tax obligation involved.
South Sudan is now part of the same African story, where governments are trying to move public payments and services away from manual processes that are harder to track and more expensive to manage.
The country has introduced electronic tax administration and online government services, including digital processes connected to petroleum permits where users can apply, pay through different channels and receive completed documents electronically.
An International Monetary Fund assessment reported that South Sudan’s non-oil revenue rose from SSP8.9 billion during the 2016 and 2017 financial year to SSP83 billion during the 2021 and 2022 financial year.
The IMF linked much of that improvement to stronger compliance after electronic tax administration was introduced, showing why digitisation has become an attractive option for governments trying to improve revenue collection.
Companies providing payment software, settlement tools and billing technology are becoming part of that process across African markets, including South Sudan, where public institutions increasingly rely on electronic systems to handle transactions.
CapitalPay is one of the technology companies associated with that wider market, but the bigger story is the same one playing out across Kenya, Tanzania, Rwanda, Ghana and other countries, moving public payments online.
The Important Work Happens After Someone Presses Pay
The payment screen is usually the only part most people ever see, yet the more important work happens behind it, where a transaction has to be connected to the correct service and account.
A complete system may need to confirm identity, generate a bill, connect to banks or mobile money operators, process the transaction, issue a receipt and preserve records that can later be checked.
That is why seeing the name of a bank, mobile wallet or technology company on a payment screen does not automatically tell you who created the charge or who ultimately received the money.
The useful questions are always the same, because governments need to know who imposed the charge, who processed the payment, where the money settled and what record remains after the transaction.
Africa’s Payment Story Is Moving Into Its Next Stage
Africa has already shown that it can move quickly when technology solves an everyday problem, with mobile money becoming one of the clearest examples of that across the continent.
The next stage is about connecting that payment culture to government services, public revenue, banks, cross-border trade and systems that can preserve reliable records long after the transaction has happened.
Kenya has eCitizen, Tanzania has GePG, Rwanda has Irembo, Ghana has Ghana.GOV, South Africa has SARS eFiling, Nigeria has built large scale government payment infrastructure, and South Sudan is moving deeper into electronic public services.
Those platforms are different, but the direction is increasingly similar, with African governments trying to collect money through systems where billing, payment and settlement leave a clearer trail than the paper-based processes they replaced.
Africa’s digital payments story is no longer only about sending money from one phone to another, because it is becoming part of how governments collect revenue, deliver services and keep track of public transactions.