June 15th 2026, Yellow Card, the largest licensed Stablecoin-based infrastructure provider operating across over 50 markets, has been named to the inaugural Fortune Crypto Innovators list, published alongside the Fortune Crypto 100, cementing its place among the world’s leading digital asset innovators.
The Fortune Crypto Innovators list recognizes organizations advancing the global digital asset ecosystem through breakthrough technology, infrastructure, security, and adoption – shining a light on the builders and enablers whose work shapes the future of blockchain and digital assets beyond traditional measures of scale.
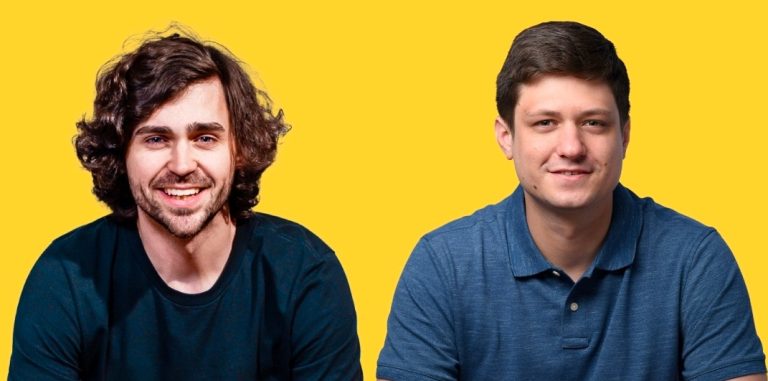
“Being named to the Fortune Crypto Innovators list affirms what we have always known: the future of global commerce runs through emerging markets. Yellow Card exists to bring those markets to global companies, powering the infrastructure that gives businesses everywhere the speed, efficiency, and reliability that modern commerce demands. This is not a regional story. This is a global one,” said CEO and Co-founder of Yellow Card, Chris Maurice.
Justin Poiroux, CTO and Co-Founder, added, “For nearly a decade, the company has been deliberately building the rails that global commerce increasingly depends on. Our infrastructure gives businesses anywhere in the world frictionless access to Stablecoins and digital asset rails, without needing to be crypto experts. What began as a mission to serve underserved markets has scaled into a globally trusted operation, and this recognition from Fortune reflects the depth and ambition of what we have built,” said Poiroux.
In recent months, Yellow Card has accelerated its global expansion strategy, deepening its presence across key emerging markets in Africa, Latin America, and Southeast Asia. The company has made significant strides in product innovation, advancing its Stablecoin payment infrastructure, fiat settlement rails, and custody wallet services to meet the demands of an increasingly borderless financial system. These developments underscore Yellow Card’s evolution from a market-specific operator to a truly global emerging markets infrastructure company.
Trusted by some of the world’s largest financial institutions and payments companies, including Mastercard, Visa, Thunes, MoneyGram, and PayPal, is a testament to the reliability, compliance standards, and global interoperability that Yellow Card has built at scale.
As Yellow Card continues to expand its global footprint, this recognition serves as both a milestone and a mandate. The company remains committed to pushing the boundaries of what is possible in global payments and digital asset infrastructure, building the financial layer that connects businesses to the world, regardless of where they operate.
About Yellow Card
Yellow Card is the largest licensed Stablecoin-based infrastructure provider for emerging markets. From Stablecoin payment infrastructure to fiat settlement rails, custody wallet services, and custom local Stablecoin issuance, Yellow Card provides the complete infrastructure businesses need to manage Stablecoins, payments, and operations across emerging markets.
Over 100 million accounts have been created in World of Warcraft since 2004. The game has survived expansions that divided the community, years of shifting subscriber counts, and two decades of competition from every major studio in the industry. Estimates from analysts and community trackers put active players across all WoW versions somewhere between 8 and 9 million as of mid-2025. It is the highest figure since the Wrath of the Lich King era.
No other game in the genre has managed this. The question worth asking is not whether WoW still matters but why players who leave keep finding their way back. For many returning players, a WoW carry is the first step back in. It is a way to close the progression gap and rejoin the game at a level where it actually gets interesting, without grinding through content they have already seen.
The World Holds Its Value
World of Warcraft takes place in Azeroth, a world that has been constructed through twenty years of expansions and storyline updates. The majority of MMOs grow old and lose their relevance, with newer titles having better graphics and faster development. The opposite is done by Azeroth. Every expansion contributes to an already familiar world for the players.
A gamer who comes back three years later is familiar with the areas, the camps, the characters. That familiarity helps in making the reversion feel like going back to a place. There has never been sufficient time to establish that sort of geography in the memories of players with any other MMO.
The recent Worldsoul Saga, a three-expansion arc encompassing The War Within, Midnight, and The Last Titan, provides the story with the scale that other games seldom attempt. Players are not just logging in for the current patch. They are committed to a story that will take years to be solved.
Progression That Actually Means Something
WoW’s gear system is one of the most refined progression loops in gaming. Every season has a new ilvl ladder and several parallel tracks. The same character power curve is offered through Mythic+, raiding, Delves, world content, and crafting. This allows players to have the flexibility in their progression.
The Great Vault supports weekly interactions. Each week, players who finish certain material get one free pick among a limited set of items. That weekly reward establishes an innate flow. You log in, do whatever you need to, and get your reward. Be late by a week, and you lose the reward. This cycle is fulfilling only because it has a definite end and a predictable result.
Variable loot makes each run exciting in the most appropriate manner. When a player runs a Mythic+ dungeon, he or she may leave with a best-in-slot upgrade or something unhelpful. It is the potential of a significant improvement in any one run that makes every run worth pursuing.
The Social Layer Is Irreplaceable
None of the MMOs has created a social infrastructure as rich as World of Warcraft. Guilds have ranks of officers, bank systems, calendar tools, and communications channels. The raid teams plan weeks. Mythic+ teams form a common acronym about routes and pulls. The social layer of WoW is not something that comes with the game. It is rather a major component of the game.
Studies of the behavior of MMORPG players have continued to report that social bonds are the best predictor of subsequent play. The endgame of WoW is constructed around group content since groups build relationships, and relationships give them a reason to come back.
Returning players nearly always report that they have reconnected with old guildmates or that they have found a new community as a central reason they remain. They are attracted to the world. People hold them in bondage.
A Calendar That Always Has Something Happening
Since 2005, World of Warcraft has been operating a seasonal timetable of in-game events. The Lunar Festival, Brewfest, Hallow End, and a dozen other holidays have their own cosmetics, mounts, achievements, and activities that can only be gained during a certain time.
This calendar proves that nothing is ever completely idle in the game. It is never pointless to log in, a mount that is only available this month, an achievement that is closing in two weeks, a world event that will grant a title that is not available the rest of the year. Breaking players tend to re-enter the cycle of regular play with a seasonal event and get sucked in again.
Two decades of seasonal content also imply that longtime players will have a backlog of cosmetics, mounts, and achievements to work on. The game provides years of optional content to those who desire it. No other MMO has the amount of history.
Blizzard Keeps Making It Easier to Return
A strength that is underestimated in WoW is the deliberate design towards returning players by Blizzard. Catch-up mechanics is a mechanism that is triggered in the middle of an expansion to allow players to bridge the gap in gears as fast as possible. Quest campaigns hasten the leveling. The Warband system is one that shares progress, currencies, and storage with all characters in an account.
The point is the same. There is no time to be late in coming back. Midnight launched in 2026 to the biggest concurrent player peak since Shadowlands. A lot of those players had been out for months or years. This cycle continues each expansion. It makes players come back, unlock new content, rebuild characters, and enjoy the next level. That very cycle has been running for twenty years.
Twenty Years of Evidence
World of Warcraft generated an estimated $680 million in revenue in 2024. It is a 12% increase over the prior year. The game franchise has accumulated roughly $15 billion in lifetime revenue. The game ranked eighth across all Twitch categories by average viewership in 2025, with World First raid races regularly pulling over 500,000 concurrent viewers.
These are not numbers built on nostalgia. Dragonflight reversed years of subscriber decline. The War Within launched to the strongest critical reception since Legion. Midnight continued that momentum. The game is in better shape now than it was in 2021, 2018, or 2015.
What World of Warcraft offers that no other MMO has replicated is a combination of deep world-building, refined progression, genuine social architecture, and twenty years of accumulated content. All these have been maintained in a single living game. Other MMOs can match one or two of those. None has matched all of them at once. That is why players keep coming back. Not because they cannot stop. Because it is still the best game to play.
Unexpected financial emergencies can arise at any time, often catching individuals and families off guard.
Whether it is a medical expense, urgent home repair, school fees requirement, or an unforeseen personal obligation, access to reliable banking services can make a significant difference in managing such situations.
Financial advisors emphasize the importance of having banking solutions that not only facilitate everyday transactions but also provide access to credit and other financial support when the need arises.
One such solution is the Co-op Bank Salary Account, a transactional account designed specifically to facilitate salary processing for employees in both the public and private sectors.
The account is structured to provide convenience, affordability, and access to a range of banking products that can support customers in their financial journeys.
A key feature of the Co-op Bank Salary Account is its accessibility. Customers can open and operate the account without maintaining a minimum balance, making it suitable for employees across different income levels.
The account also attracts no monthly maintenance fee, helping account holders avoid recurring banking charges that can erode their earnings over time.
Beyond salary processing, the account serves as a gateway to a variety of financial solutions. Eligible customers can access asset products including unsecured personal loans, asset finance facilities, mortgages, and cash advances.
These options can provide much-needed financial support for customers looking to meet personal needs, acquire assets, invest in property, or address urgent cash flow requirements.
Account holders are also issued with a debit card, enabling convenient access to funds through automated teller machines (ATMs), point-of-sale transactions, and other payment channels.
In addition, customers may qualify for a credit card, further expanding their access to flexible payment and financing options.
How to open a Co-op Bank Salary Account
Opening a Co-op Bank Salary Account is a straightforward process. Prospective customers are required to present an original and copy of their national identity card or passport, a copy of their KRA PIN certificate, and Sh600 for the debit card, inclusive of excise duty.
A passport photograph is taken at the branch during account opening. Notably, applicants are not required to provide a letter of introduction from their employer, simplifying the onboarding process.
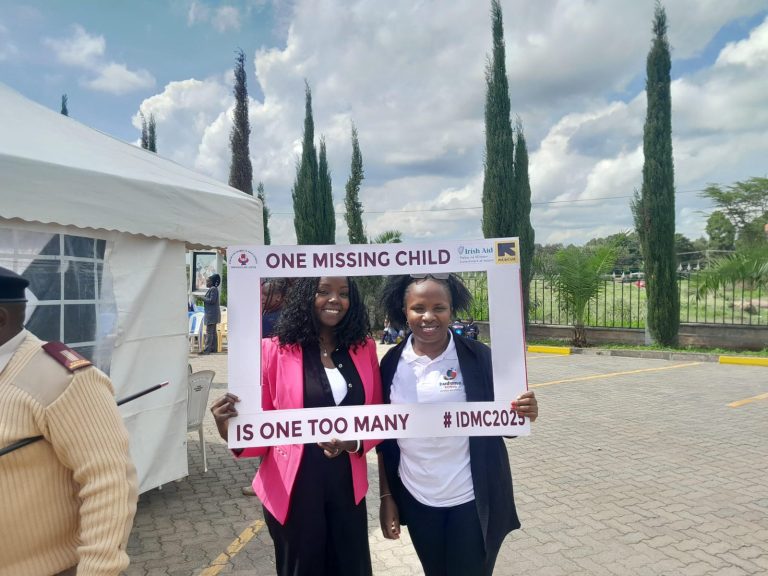
Missing Children: Cases of missing and found children have become increasingly common across the country, leaving many families in agony as they search for their loved ones.
Children may go missing from home or other care settings for a range of complex and often overlapping reasons including abduction, abandonment, running away, getting lost, trafficking, neglect, inadequate care and supervision, poverty, custody disputes, fleeing danger or being targeted through grooming for abuse or exploitation.
Each of these circumstances heightens their vulnerability and places them at serious risk of harm, underscoring the urgent need for stronger protection and prevention measures.
This includes 1,636 cases of missing children, 1,952 abductions, 6,820 abandonment cases and 173 trafficking incidents. Even more troubling is that over 2,300 children are still unaccounted for with roughly 23 children reported missing, abandoned or abducted every day.
These figures represent vulnerabilities facing children and thousands of families dealing with uncertainty, fear and unanswered questions.
In the current digital age, the dissemination of information regarding missing children has become widespread.
Yet what is increasingly concerning is how easily society has become accustomed encountering missing child posters on social media.
Every week, Kenyans come across appeals from parents looking for their children, holding on to hope that they will be found safe and unharmed.
This has contributed to a troubling normalization of an issue that should, each time, evoke urgency, empathy, and collective concern.
However, child disappearances do not just happen in isolation. They are often the result of identifiable risks and systemic gaps in protection.
These factors increase children’s vulnerability and place them in harm’s way long before they are reported missing.
The period a child goes missing presents significant risks that can have lasting effects on their well- being. These risks may include exposure to drugs and alcohol as well as sexual, emotional and physical violence, all of which can adversely affect their health and in extreme cases, lead to death.
This reality demands a shift in focus from reaction to prevention. While finding a missing child remains critical, prevention must take priority.
Kenya must therefore strengthen a child safety framework that frames protection as a shared responsibility among parents, schools, authorities, the government and the wider community.
Schools, in particular, must strengthen supervision systems and implement robust safeguarding measures, including enforcing strict student pick-up and drop-off procedures and ensuring every child is accounted for throughout the school day.
Private security providers also have a critical supporting role to play within this ecosystem. Beyond physical protection services, they can strengthen child safety through secure access control in residential estates, schools, shopping centres, and transport hubs where children frequently move.
Trained security personnel can also assist in rapid incident reporting, surveillance monitoring, and coordination with law enforcement during emergencies.
When integrated into broader community safety systems, private security becomes an important early-warning and response layer in preventing and responding to child disappearances.
Parents, on the other hand, must move beyond assumptions of safety and take a more active role in their children’s daily lives.
This involves knowing who they interact with, where they spend their time and what risks they may be exposed to. Parents should also equip children with basic safety knowledge including how to recognize and respond to potentially dangerous situations.
This can be reinforced by helping children memorize their full name and home address, parents’ full names and contact information and other relevant emergency information.
Additionally, parents can consider including tracking devices on their children as a security measure. Children also need to be guided to understand their surroundings and taught basic safety protocols, such as how to seek help if they get lost or find themselves in unsafe situations.
Communities should also strengthen neighbourhood safety networks that help residents identify and promptly report suspicious activities.
The government, in turn, should invest in faster reporting systems and improve coordination among all agencies responsible for child protection.
It should also conduct public awareness campaigns to inform the public about the available services and response mechanisms activated when a child is reported missing.
Leveraging Technology and Strengthening National Action
Technology must be central to these efforts. In an era where information spreads like wildfire, Kenya should develop more efficient national alert systems that enhance rapid response.
Such systems should enable timely dissemination of information on missing children through mobile phones, media outlets and social media channels, ensuring wider public reach and faster action.
Ultimately, the challenge for Kenya is not only institutional but cultural. It is about building a society where the safety and well-being of children are treated as non-negotiable.
Child disappearances should never become routine news; they must always be treated as unacceptable and impossible to ignore.
The future of any nation depends on how well it protects its most vulnerable citizens. Kenya cannot continue to treat child disappearances as isolated incidents.
The country must acknowledge child disappearances as a national issue that requires immediate and coordinated action.
Mechanisms for promptly reporting, responding to and preventing missing children’s cases must be standardized across all agencies.
In addition, the legal and policy frameworks governing the prevention, protection and response to missing children must be clearly defined, strengthened and consistently enforced.
Abot the author
Irene Opondo – Sales and Marketing Manager at SGA Security Kenya.
Irene Opondo is the Sales and Marketing Manager at SGA Security Kenya.
She is a proactive results-oriented self-starter who can operate both individually and as part of a team with agile leadership skills and a strong believer in self-integrity. She is an accomplished sales Coach with a track record of growing Business tremendously.
She is an experienced in analyzing market trends and sales patterns and drawing sound recommendations that lead to enhanced growth in Market share. She is highly innovative and able to scope out excellent Business solutions that position us a notch ahead of the competition.
As Kenya continues its transition toward a cashless economy, debit cards are increasingly becoming an essential financial tool for consumers seeking convenience, security, and greater control over their spending.
From shopping at supermarkets and fuel stations to making online purchases and withdrawing cash, debit cards are transforming how people access and use their money.
For many consumers, debit cards offer a convenient alternative to carrying cash. With a simple tap, swipe, or insert-and-PIN transaction, customers can make payments instantly without worrying about having exact change or visiting an ATM.
The widespread availability of point-of-sale (POS) terminals in retail stores, restaurants, pharmacies, and fuel stations has made debit card payments more accessible than ever before.
Contactless payment technology has further enhanced convenience by allowing customers to complete transactions within seconds.
The rise of online shopping has also contributed significantly to increased debit card usage. With more Kenyan consumers purchasing products and services through e-commerce platforms, subscription services, and online marketplaces, debit cards provide a secure and convenient way to make digital payments.
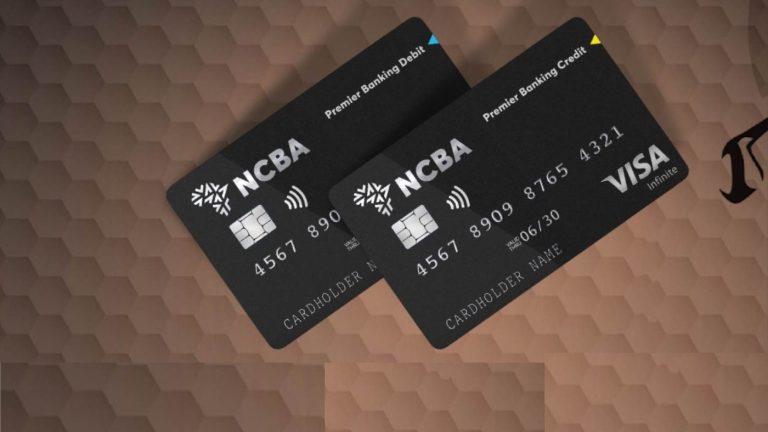
Banks have invested heavily in making debit card payments seamless. NCBA Bank is one of the players leading this transformation through its Visa Debit Card, which offers customers a secure and convenient way to conduct transactions locally and internationally.
The card enables customers to make cashless payments at point-of-sale terminals across the country through a simple swipe or tap, at no additional cost.
The card can also be used for online transactions, giving cardholders the flexibility to shop, pay bills, and access services from anywhere.
Access to funds anytime, anywhere
One of the key reasons many customers choose debit cards is accessibility. The NCBA Visa Debit Card allows cardholders to withdraw cash from NCBA ATMs across the country and access funds through over-the-counter services at any bank branch.
Additionally, the card is accepted at millions of merchant outlets worldwide, making it a practical option for travellers, business professionals, and customers making international purchases.
For Nairobi-based entrepreneur Grace Wambui, the convenience has been invaluable.
“I no longer have to worry about carrying large amounts of cash when travelling for business. Whether I need to pay for services, shop online, or withdraw money, the card gives me easy access to my account whenever I need it,” she says.
Enhanced security for customers
Security remains a major concern for financial consumers, particularly as digital transactions increase. Modern debit cards are designed with multiple layers of protection to safeguard customers’ funds and personal information.
The NCBA Visa Debit Card is equipped with Chip and PIN technology, which enhances transaction security and helps reduce the risk of fraud.
It is also protected through Verified by Visa, an additional security feature that provides enhanced protection for online purchases.
Cybersecurity consultant Anne Njeri says consumers are becoming increasingly aware of the importance of secure payment methods.
“People want assurance that their transactions are protected. Features such as Chip and PIN authentication and secure online verification significantly strengthen consumer confidence,” she explains.
Beyond convenience and security, debit card users can also enjoy value-added benefits. NCBA Visa Debit Card holders have access to discounts at selected merchant outlets when they pay using their cards, allowing them to save money on everyday purchases.
Cardholders also benefit from global customer assistance services, including support for reporting lost or stolen cards, emergency card replacement, and emergency cash disbursement when travelling.
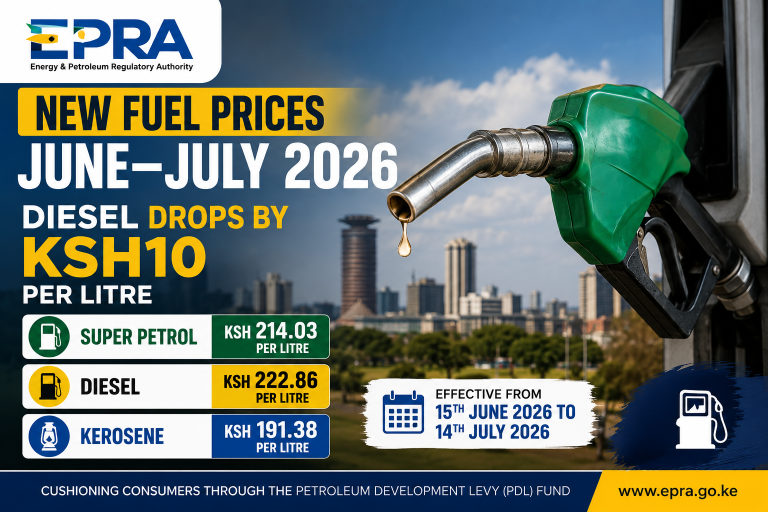
According to the regulator, the price of diesel has decreased by KSh10.00 per litre, while the price of super petrol has reduced slightly by KSh0.22 per litre. The price of kerosene remains unchanged during the review period.
The latest adjustment is expected to lower transportation costs and ease operational expenses for businesses that heavily depend on diesel-powered vehicles and machinery.
New Fuel Prices in Nairobi
Motorists in Nairobi will pay the following maximum pump prices:
Super Petrol – KSh214.03 per litre
Diesel – KSh222.86 per litre
Kerosene – KSh191.38 per litre
These prices are inclusive of Value Added Tax (VAT) and all applicable levies.
EPRA stated that the Government will utilize approximately KSh10 billion from the Petroleum Development Levy (PDL) Fund to cushion consumers against higher diesel and kerosene prices.
The subsidy intervention continues to play a critical role in stabilizing fuel costs amid fluctuations in global oil markets and foreign exchange movements.
Changes in International Fuel Import Costs
Data released by EPRA shows mixed trends in the average landed cost of imported petroleum products between April and May 2026.
The average landed cost of:
Super Petrol declined by 0.56%, from US$906.23 to US$901.16 per cubic metre.
Diesel increased by 0.21%, from US$1,291.98 to US$1,294.71 per cubic metre.
Kerosene decreased by 0.33%, from US$1,332.73 to US$1,328.36 per cubic metre.
These international price movements, together with government interventions and tax considerations, influenced the latest local fuel pricing adjustments.
EPRA noted that fuel imports are denominated in United States Dollars and therefore exchange rate movements significantly affect local pump prices.
The Kenya Shilling remained relatively stable against the US Dollar, with the average exchange rate standing at approximately KSh129.82 per US Dollar in May 2026, helping to moderate fuel costs.
Relief for Consumers and Businesses
The substantial reduction in diesel prices is expected to benefit public transport operators, logistics companies, manufacturers, farmers, and other businesses that rely on diesel-powered operations.
Lower fuel costs could also contribute to easing inflationary pressures by reducing transportation and distribution expenses across various sectors of the economy.
EPRA maintains that the Petroleum Pricing Regulations are designed to cap retail fuel prices while ensuring that importation and operational costs are reasonably recovered, ultimately protecting consumers from excessive price volatility.
In May, Kenyan motorists and businesses were confronted with higher fuel costs following the latest pricing review by the Energy and Petroleum Regulatory Authority (EPRA) for the period between May 15 and June 14, 2026.
The sharp rise in diesel prices carried broader economic consequences. Diesel is the backbone of Kenya’s logistics, agriculture, and manufacturing sectors. A steep increase typically translates into higher transport costs, which cascade into food prices and overall inflation.
For businesses, especially SMEs and logistics operators, the cost escalation will likely compress margins or force price adjustments, further straining consumer purchasing power.
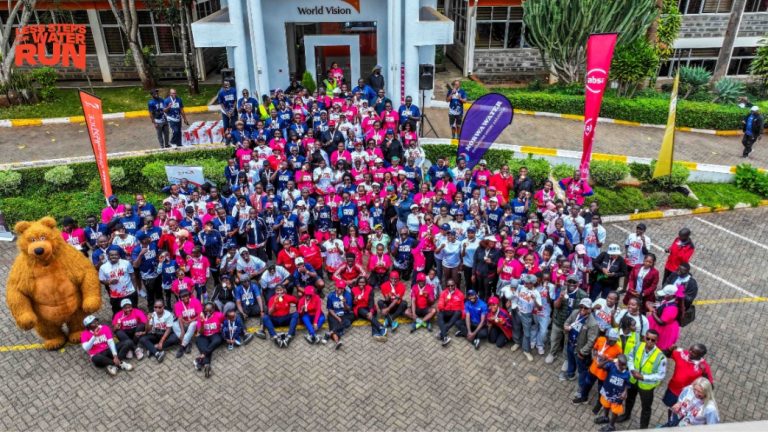
Hundreds of runners, cyclists, corporate partners, staff, children and supporters came together today at World Vision Kenya’s Karen office for the 2026 Less Steps for Water Run, raising awareness and mobilising support for a new water project that will transform access to safe water for communities in Lower Yatta, Kitui County.
The annual initiative seeks to reduce the burden faced by children and families who walk over 6 Kms every day in search of water. Funds raised through this year’s run will support the implementation of the proposed Kithiani Water Project, which will provide safe, clean water to approximately 1,200 community members and 500 pupils from Kithiani and Kyoani primary schools.
The morning event attracted supporters across different sectors, including corporate partners Jambojet, ABSA Bank Kenya, Washlab, Norwa Water Africa, Ngong Hills Hotel, Gig Dynamics, Tsavo Real Estate, Eka Hotel and the Ridge Cabin Resort who joined World Vision Kenya in championing access to water as a critical foundation for children’s education, health and protection.
Speaking during the event, World Vision Kenya’s Interim National Director Gershon Mwakazi said that access to clean water remains one of the most effective investments in children’s wellbeing.
“Every day, children in Lower Yatta spend hours searching for water instead of being in school, studying or enjoying their childhood. Through the second edition of the Less Steps for Water Run, we are taking collective action to change that reality and bring safe water closer to homes, schools and communities that need it the most.”
Speaking during the event, Mumbi Kahindo, Chief People Officer at Absa Bank Kenya, reaffirmed the bank’s commitment to driving sustainable community impact through partnerships that improve access to essential services.
“At Absa, we recognise that access to clean and safe water plays a vital role in improving health outcomes and keeping children in school. Through the Absa Kenya Foundation, and our Corporate and Investment Banking we are partnering with World Vision Kenya to support sustainable solutions like the Kithiani Water Project. This is one of the ways we continue to empower livelihoods of the communities we serve.”
The Kithiani Water Project will be implemented in Kiseuni Sublocation, an area where most residents currently depend on shallow wells along River Tiva for their daily water needs. The project will include the construction of a solar-powered sump well, a 15-metre water tower
Absa Bank Kenya has endorsed a new banking sector initiative aimed at accelerating the uptake of digital payments through the PesaLink platform.
Under the programme, PesaLink transaction fees have been significantly reduced, with transfers valued between Sh1,001 and Sh999,999 attracting charges as low as Sh20. Transactions below Sh1,000 will be processed free of charge.
The move is designed to encourage greater use of real-time account-to-account transfers by providing consumers and businesses with a more affordable payment option for everyday transactions.
The initiative, spearheaded by the Kenya Bankers Association (KBA), comes as Kenya maintains its position as a global leader in the adoption of digital financial services.
Despite this progress, a large proportion of low-value transactions continue to be conducted through mobile money platforms.
By lowering transaction costs, the banking industry hopes to position instant bank-to-bank transfers as a convenient and practical choice for routine financial activities, including sending money to relatives and friends as well as making payments for goods and services.
Speaking on the development, Absa Bank Kenya Consumer Banking Director Moses Muthui said the initiative demonstrates the sector’s commitment to enhancing affordability and accessibility in banking services.
“Through this initiative, we are making banking more accessible, affordable and convenient for our customers. As consumers and businesses increasingly seek value and ease of use, the cost of transactions should not stand in the way of accessing secure and dependable digital financial services,” said Muthui.
PesaLink enables customers to move funds instantly between local bank accounts, whether for personal or business purposes. During the promotional period, users will benefit from seamless real-time transfers at substantially reduced rates across participating banks.
The programme is also expected to strengthen financial inclusion by encouraging more Kenyans to transact through formal banking channels while enjoying improved security, convenience and interoperability within the banking ecosystem.
For small enterprises and entrepreneurs, the initiative offers an opportunity to cut transaction expenses, improve cash flow management and access funds instantly, factors that are critical to supporting daily operations and business expansion.
Muthui noted that affordable digital payment solutions remain central to driving economic participation and fostering a more inclusive financial system.
“Our priority is to provide solutions that address the changing needs of our customers. Cost-effective digital payments play a vital role in supporting business growth, expanding economic participation and building a more inclusive financial ecosystem,” he said.
Customers can access PesaLink through the digital platforms of participating banks, enabling instant account-to-account transfers across the country’s banking network.
Layer poultry farming remains one of the most widely practiced agribusiness ventures across Africa and beyond, largely because of its steady income potential, relatively quick returns, and growing demand for eggs as an affordable source of protein.
For many smallholder and commercial farmers, keeping layers offers a reliable pathway to food security, employment creation, and household income.
The benefits of layer farming are significant. Eggs are consumed daily in millions of homes, making the market dependable and less volatile compared to some farm products.
Beyond direct sales, poultry manure provides valuable organic fertilizer for crop production, while the business itself creates opportunities along the value chain.
Yet despite these advantages, one challenge continues to frustrate many poultry farmers: low egg production.
Many farmers have reported scenarios where birds appear healthy, active, feeding well, but egg output remains below expectations.
According to poultry experts, the problem often comes down to management gaps that directly affect production. Understanding these factors can help farmers restore and improve performance.
Feed Quality and Nutrient Balance
Nutrition is the foundation of egg production. Layers require a carefully balanced diet rich in protein and calcium to sustain laying. Protein plays a central role in egg formation, while calcium strengthens eggshells.
When feed quality is poor, diluted, or inconsistent, hens often respond by reducing laying frequency or producing weak-shelled eggs.
Farmers are advised to maintain a strict feeding schedule and supplement calcium where necessary using materials such as crushed oyster shells or limestone.
Lighting Duration and Stability
Egg laying is heavily influenced by light exposure because it regulates the hormones responsible for production. For optimum output, hens need between 14 and 16 hours of light daily.
When lighting is irregular, whether due to poor housing design or inconsistent artificial lighting, the birds’ laying cycle is disrupted.
Farmers are encouraged to maximize natural daylight and install artificial lighting systems where necessary to maintain consistency.
Stress from Overcrowding and Disturbance
Stress is one of the most overlooked causes of reduced egg production. Overcrowding, excessive noise, predator threats, and constant disturbances create anxiety among birds, which directly lowers laying activity.
A calm and secure environment is essential.
Proper stocking density, reduced movement around the poultry house, and protection from predators can significantly improve production.
Inadequate Nesting Conditions
Hens need safe, comfortable, and private spaces to lay eggs. Poor nesting arrangements can cause birds to withhold laying or deposit eggs on the floor, increasing the risk of breakage and loss.
Clean, dark, and quiet nesting boxes with dry bedding encourage normal laying behavior and help improve productivity.
Heat Stress and Poor Ventilation
High temperatures are a major enemy of egg production. Heat stress reduces feed intake, weakens birds, and interferes with egg formation.
Poor ventilation worsens the problem by trapping hot air inside the poultry house.
To manage this, farmers should improve airflow, avoid overcrowding, and ensure birds have constant access to cool, clean drinking water.
Age and Breed Productivity
Not all hens perform equally. Young layers are naturally more productive, while older birds gradually decline in egg output.
Breed selection also matters. Some breeds are genetically designed for high egg production, while others are less efficient.
Farmers should monitor flock age and cull or replace birds whose productivity has dropped significantly.
Water Intake Quality and Access
Water is often underestimated, yet it is one of the most critical elements in egg production. Eggs contain a large percentage of water, meaning even short periods of water shortage can immediately reduce laying.
Dirty or contaminated water can also discourage intake and affect bird health.
Farmers are encouraged to ensure clean, fresh water is always available and that drinkers are functioning properly at all times.
In determining how matrimonial property should be divided after a marriage ends, courts will now weigh more than just legal documents.
Factors such as years spent raising children, managing a household, supporting a spouse’s work, and sustaining family life will carry significant weight in deciding ownership.
This follows a landmark High Court ruling that clarified a marriage certificate is not the sole basis for proving entitlement in property disputes arising from separation or divorce.
Justice Charles Kariuki held that extended cohabitation, children born during the relationship, and the practical realities of family life can establish a presumed marriage under the Matrimonial Property Act, giving either party legal grounds to claim a share of property.
The court further emphasized that contribution to matrimonial wealth goes beyond direct financial input. Domestic responsibilities such as childcare, household management, and providing an environment that enables a spouse to build wealth are valid forms of contribution deserving legal recognition.
The decision arose from a case involving a woman who was evicted from her matrimonial home in 2010 and later sought the court’s intervention to secure a stake in assets she argued were built through their union.
Although she did not present documents showing monetary contribution, the court found that her two decades of unpaid domestic work and caregiving had created a beneficial interest in the family properties.
While ownership of the properties largely remained with the registered proprietor, the court awarded the woman a 30 per cent beneficial share and barred any interference with her interest.
The ruling offers protection to individuals, often women, whose roles in the home have historically gone unrecognised in property disputes despite being central to wealth creation within marriages.
In Kenya, customary marriages are governed by the Marriage Act, a law that consolidates various forms of unions under a single legal framework. The legislation formally recognises five categories of marriage: civil, Christian, customary, Islamic, and Hindu.
Under the law, customary marriages must be solemnised in accordance with the traditions and practices of the respective communities involved. Although these unions are legally acknowledged, couples are advised to formally register their marriage with the Registrar of Marriages to secure full legal recognition.
The registration process entails the issuance of a marriage certificate, an important legal document that serves as evidence in matters relating to inheritance, divorce, child custody, and property ownership.
While customary unions remain valid under Kenyan law, formal registration offers greater legal protection and enables couples to assert and safeguard their rights in court more effectively, particularly in the event of disputes.