Home Blog Page 66

Operations: the heartbeat of a successful business

Just as human beings with a fractured backbone cannot operate at their optimal level, businesses with fractured operations face similar challenges.

Operations serve as the driving force behind a successful business. Weak operations strain and hinder growth, while strong operations are the key to achieving success.

The Lost Connection in African Businesses

Across Africa, thousands of promising businesses are launched each year. However, many entrepreneurs struggle to transition from mere survival to sustainability.

Often, they find themselves juggling multiple roles, managing marketing, finance, projects, and talent sourcing, while having little time to establish growth-oriented systems. This tendency leads to businesses that should be scaling but eventually stall or fail due to inefficiency.

An often-overlooked term in entrepreneurship discussions, operations act as the engine that drives your ideas, aligns your team, ensures customer satisfaction, and keeps finances on track.

The Real Meaning of Operations

Operations encompass more than just day-to-day tasks and activity management; it is the art of transforming plans into achievable outcomes. This involves creating processes, assembling teams, and developing systems that deliver the right product or service at the right time, with the right quality and at the right cost.

In simple terms, operations are how you fulfil your promises to customers. For example, in a small bakery, this could mean aligning ingredient and recipe choices with daily sales.

In a manufacturing company, efficiency in production, inventory management, and on-time distribution is key. For a digital startup, the ease of use and system availability are crucial.

The Significance of Operations for African Businesses

  1. Scalability: A lack of operational strength can make growth a nightmare. Successful businesses scale effectively because they have systems that support consistency, whether they serve 10 or 10,000 customers.
  2. Trust and Credibility: Investors, partners, and customers are drawn to predictable businesses. An organised operation conveys professionalism and sustainability.
  3. Profitability: Efficiency helps to minimise waste. Every improved process contributes directly to the bottom line, whether by reducing unnecessary costs or increasing turnaround time.
  4. Resilience: Healthy businesses stay on track. During crises like COVID-19, companies with well-defined systems (such as remote work processes and online payment systems) were able to adapt more swiftly and recover more quickly.

Operational Challenges in Africa

Operational excellence remains a significant gap among African SMEs. Common issues include:

Overdependence on the Founder: Many businesses falter when founders retire because no systems have been institutionalised

Low Level of Technology Use: Manual operations can slow processes, leading to delayed decision-making and increased errors.

Lack of Coordination in the Supply Chain: Unreliable suppliers, ineffective logistics, and subpar inputs can cripple efficiency.

Skill Shortages: SMEs often neglect investing in operational or process managers, despite their critical importance alongside marketing and finance.

Poor Record Keeping: Without data, businesses lack measurement capabilities and cannot appeal to investors.

A Practical Playbook for Building Strong Operations

African businesses must work deliberately to strengthen their operations and transition from hustle to high-performance enterprises. Here’s how:

  1. Systematise Your Business: Document key processes from sales to service delivery. Clear Standard Operating Procedures (SOPs) ensure continuity, even during staff changes.
  2. Invest in People: Employees are the backbone of operations. Equip your staff to think systemically, delegate effectively, and take ownership of results.
  3. Leverage Technology: Enhance operational efficiency with affordable digital tools, including accounting software (like Xero and ZohoBooks), inventory management software, and customer relationship management (CRM) software.
  4. Track Performance: Identify key performance metrics, cost per unit, customer satisfaction, turnaround time, and productivity, and analyse them regularly. What gets measured gets managed.
  5. Develop Feedback Loops: Operations should be continually refined. Gather customer and team feedback to enhance your systems.
  6. Create a Scalable Plan: Design a future-proof infrastructure. Even if you are small now, foresight prevents operational strain as opportunities arise.

The African Advantage: Making Structure Scale

Africa boasts a vibrant and innovative business ecosystem. The new generation of entrepreneurs already possesses the ideas; what they need is the discipline to implement them. By mastering operations, African businesses can compete globally, attract investors, and create long-term value.

We have seen numerous success stories across the continent. For instance, in Kenya, Twiga Foods is automating the distribution of fresh produce. In Nigeria, Flutterwave is automating payment systems, while in Rwanda, Inyange Industries is automating the distribution of dairy products. These companies have achieved growth not only through innovation but also by implementing effective operations.

In conclusion: The Growth Story of Africa in Execution.

The future of African business will not be authored by those who have the most outspoken ideas, but by those who perform. It is in operations that vision intersects with the discipline; it is in operations that ambition is transformed into systems that deliver reliable excellence.

With the continent in the next stage of entrepreneurship, now is the time to not only honour founders, but also builders – people who get the systems running. Dreams in business are pointless without delivery, and delivery comes with operations.

Mr Ian Makale is the Strategy Consultant at WYLDE International. You may connect with Ian via email: [email protected]

Also Read: The silent killer: how businesses with high revenue still fail
The silent killer: how businesses with high revenue still fail
Picture this: a manufacturing business celebrating landing its largest contract yet to supply a supermarket chain; a few months later, it enters voluntary administration or lays off employees.

For many other businesses, they often look quite healthy: the numbers on the papers appear healthy, clients are knocking on your door, and sales are increasing.

Such enterprises don’t fail from a lack of demand; their own success crushes them. A KNBS report has shown that a significant number of the 400,000 micro, small and medium enterprises that close annually are those that appear to be thriving and drowning in revenue orders, but are mostly bankrupt.

Two things might be happening in such a situation: a catastrophic cash flow management or unprofitable margins. Often, high revenue masks structural weaknesses, such as poor policies or pricing, inefficient teams, or even weak procurement practices. A very important fact to remember is that every inefficiency scales with revenue.

High revenue with low cash flow management is a recipe for disaster. A key consideration is the inventory illusion. Many businesses, especially those in retail and manufacturing, celebrate ‘selling’ products that move to a distributor’s shelf. Consider this redeployed capital until the final payment is received.

In 2023, a CBK report noted that late payments are the single biggest challenge to growth and survival for 46 percent of micro, small and medium enterprises.

Since high revenues tend to justify business decisions such as executive hires and premium office space, the business is left with creeping fixed costs that persist whether invoices are paid or not.

The default solution often is debt to bridge the working capital, leading the company to fall into the financing fallacy, i.e. using short-term debt to fund long-term growth. With interest rates rising, the cost of servicing this mismatch gradually erodes profit margins, allowing this model to serve only lenders rather than shareholders and employees.

Surprisingly, most businesses leave little to no room for cash flow visibility, as only 38 percent maintain formal financial records. Recognising this gap can inspire you to prioritise accurate record-keeping, fostering a sense of responsibility and control over your financial health.

We can’t fail to mention how tax obligations have become a cash trap for most. Seeing that tax is payable when an invoice is raised, not when cash is collected, can leave the business liquid-poor or sink the company.

Why is this situation so often in the growth markets? Because companies grow sales faster than they can finance, creating liquidity stress that high revenue alone cannot resolve. This gap between profitability and liquidity is where many businesses collapse quietly.

So in 2026, don’t let your business be a statistic of the silent killer. By regularly forecasting cash flow, pricing for risk and timing, and aligning growth with capital capacity, you can feel more in control and prepared. Investing in thorough financial visibility will help you stay confident in your business’s future.

Miss Loise Macharia is the Strategy Lead at WYLDE International. You may connect with Loise via email: [email protected]

Also Read: Why referral marketing is kenya’s next big growth lever

Why referral marketing is kenya’s next big growth lever

When was the last time you tried a new restaurant, mechanic, or hair salon because a friend recommended it? Chances are, it wasn’t a flashy TV advert or a random Instagram post that convinced you; it was someone you trust saying, “You should try this out.” That’s the power of referrals.

In Kenya today, where the cost of acquiring new customers keeps rising, referral marketing is no longer just an optional strategy. It is becoming the most cost-effective, trust-driven, and scalable way to grow. Yet, many businesses, from SMEs in manufacturing to startups in fintech, and creatives in fashion and film, are not taking it seriously enough.

Why Referrals Matter More in Kenya Right Now

Kenyan consumers are savvy. We live in a market flooded with advertising; everyone is vying for attention, spending more, and shouting louder. But people have become skeptical. A billboard can be impressive, and a Facebook ad can be eye-catching, but trust doesn’t come from ads; it comes from people.

We are a relationship-driven society. Whether it’s chamas, church groups, alumni associations, or neighbourhood WhatsApp forums, Kenyans rely on community trust to make decisions. Research supports this: Nielsen found that 92% of consumers globally trust recommendations from friends and family more than any form of advertising.

In Kenya, where community endorsement has always held weight, referral marketing is a perfect fit. It leverages a cultural belief: “If it worked for my people, it will probably work for me.”

Global Lessons, Local Parallels

Globally, companies like Uber, Airbnb, and Tesla have thrived on referrals. Uber grew by rewarding both riders and drivers for bringing others on board. Airbnb turned ordinary users into advocates by offering them travel credits. Tesla built a devoted community by rewarding owners with exclusive perks.

Now, let’s look at Kenya:

Safaricom’s M-Pesa grew partly through organic referrals, with early adopters convincing their friends and family that “sending money through the phone works.” Safaricom later introduced structured incentives for agents and customers.

Local salons and barbershops thrive on word-of-mouth referrals, the most basic form of referral marketing. Some even offer discounts when you bring a friend.

Furthermore, boda-boda mechanics and fundis rely heavily on their reputation: a good experience is shared quickly, while a poor one spreads even faster.

The lesson here? You don’t need Silicon Valley funding to succeed with referrals. You need to understand the mechanics and apply them in ways that resonate with Kenyan customers.

The Mechanics: What Makes Referrals Work

For a referral strategy to be effective, three factors must align:

  1. Great Customer Experience: If your product or service doesn’t delight, no incentive will encourage people to recommend it. Referrals begin with excellence.
  2. The Right Incentives: While some people refer naturally, a little encouragement often helps. Rewards can include discounts, airtime, loyalty points, or even non-monetary perks such as early access or recognition. Incentives must be relevant; a Nairobi millennial might value exclusive experiences, while a rural farmer might prefer cash or airtime.
  3. Seamlessness: The referral process must be simple. A personalised link, a QR code, or a quick SMS option can reduce barriers. The easier it is, the more likely someone is to act.

The Pitfalls to Watch Out For

While referral marketing sounds straightforward, it can backfire if poorly designed. Here are three traps Kenyan businesses should avoid:

  1. Over-commercialisation: If customers feel that you only want them to “sell” to their friends, trust will diminish. The most effective referrals stem from genuine enthusiasm.
  2. Engagement Fatigue: Too many referral prompts can come across as nagging. If customers are bombarded with “invite your friends” messages, they will tune out. Finding a balance is key.
  3. Misaligned Incentives: Rewards should match your audience. A “10% off your next order” might work for an e-commerce site, but may not excite a high-net-worth client buying real estate. Sometimes, non-monetary recognition, like status in a loyalty club, can matter more than cash.

So What Should Kenyan Businesses Do?

Here are three practical steps you can take right now:

  1. Audit Your Customer Experience: Before considering incentives, ask yourself: “Do my customers love this enough to tell others?” If not, fix the basics.
  2. Start Small: Launch a simple, trackable referral program. For example, “Bring a friend and both of you get 200 bob airtime.” Test it and then refine your approach.
  3. Measure and Adapt: Track the number of referrals, the quality of leads, and the conversion rates. Learn what resonates with your audience, and then double down on what works.

Closing Thought

In Kenya, we say “mtu ni watu”; people are the essence of community. Our relationships influence our lives and decisions. Referral marketing aligns business with this cultural reality.

The businesses that will thrive in the next decade won’t necessarily be the ones with the loudest advertisements; they will be those that transform customers into advocates, embedding trust into their growth strategy.

So here’s my challenge to you:

What’s one small step you can take to turn your happy customers into your biggest marketers?


Mr Christopher Odongo is the CEO at WYLDE International. You may connect with Chris via email: [email protected]

Also Read: Sip the secret: 10 Coca-Cola marketing tricks every small business should borrow

Why Nairobi’s Best Events Are All on Myjiji — And How You Can Be Part of Them

0

Nairobi never sleeps. On any given weekend, there’s a rooftop brunch filling up in Westlands, a live music night going down in Kilimani, an art pop-up drawing crowds in Karen, and a comedy show selling out in the CBD. The city’s social calendar is fuller than ever — and Nairobians are showing up.

But here’s the thing: finding out about these events has always been a mess. You hear about something through a WhatsApp forward three days after it happened. You see a flyer on Instagram, but there’s no link to buy tickets. You search online and get results from 2022. Sound familiar?

That’s exactly the problem that Myjiji was built to solve — and it’s doing it brilliantly.

Nairobi’s Events Scene Is Having a Moment

Let’s be honest: Nairobi’s events culture has levelled up. The pandemic years, for all their disruption, sparked something. People came out the other side hungrier for real, in-person experiences. The city’s creatives, promoters, and entrepreneurs responded — and what we’re seeing now is a golden era for live events in Kenya.

Why Myjiji is the Game-Changer the Event Industry Has Been Waiting For

From intimate jazz evenings to massive outdoor festivals, from corporate networking nights to underground DJ sets, there is genuinely something happening every single weekend for every type of Nairobian. The challenge was never the events themselves — it was always discovery. How do you find out what’s on, confirm it’s real, and actually get a ticket without the drama?

Why Nairobi's Best Events Are All on Myjiji —And How You Can Be Part of Them
Why Nairobi’s Best Events Are All on Myjiji —And How You Can Be Part of Them

One App, Every Event in Nairobi

Myjiji Events is Nairobi’s dedicated platform for discovering, listing, and booking live experiences. Think of it as your always-updated city guide — except instead of a blog that’s three months old, every listing is live, verified, and clickable.

Here’s what makes it different from just scrolling Instagram or waiting for a WhatsApp forward:

Everything is in one place. No more jumping between ten different pages trying to figure out if an event is even still happening. Myjiji brings events across Nairobi — music, food, arts, networking, sports, nightlife — into a single, searchable platform.

You can search by what you actually want. Browse by category, date, location, or vibe. Looking for something to do this Saturday in Westlands? There’s a filter for that. Want to find all the live music events in May? Done in seconds.

Tickets are real and verified. One of the biggest frustrations with events in Nairobi is buying a ticket from a random M-Pesa paybill and hoping for the best. On Myjiji, ticket purchases are tied to verified event listings — so you know exactly what you’re buying, who’s behind it, and what to expect when you show up.

Entertainment and Sports – Kenya’s Most Favorite Pastimes

How Myjiji Makes Sure You Never Miss Out

Beyond discovery, Myjiji is built around the idea that showing up should be easy. Once you find an event you love, buying a ticket takes less than a minute. You get confirmation, you have your ticket, and you’re done. No DMs, no waiting, no uncertainty.

For those who like to plan, the platform lets you browse upcoming events weeks in advance — so you can lock in tickets before things sell out. And if you’ve ever arrived somewhere and been told it’s sold out at the door, you’ll know exactly why that matters.

The platform is also a discovery tool in the truest sense. Browsing Myjiji regularly means you find out about events you never would have known were happening — from emerging artists doing their first headline show to established brands throwing massive experiences. It’s how Nairobi’s most culturally connected people stay ahead of the curve.

Why Nairobi's Best Events Are All on Myjiji —And How You Can Be Part of Them
Why Nairobi’s Best Events Are All on Myjiji —And How You Can Be Part of Them

What’s On in Nairobi This May

May is shaping up to be one of the best months on the Nairobi events calendar. Here’s a taste of what’s currently live on Myjiji:

Live Music Nights — Catch some of Nairobi’s best performing artists at intimate and large-scale venues across the city. Check Myjiji for the full lineup and ticket links.

Food & Lifestyle Experiences — From curated dining evenings to food markets celebrating Kenyan cuisine, there’s something for every food lover listed on the platform this month.

Arts & Culture Events — Gallery openings, spoken word nights, and creative pop-ups are happening across Nairobi. Myjiji is where the city’s arts scene lives online.

Networking & Business Events — For professionals looking to connect, May has a strong calendar of industry meetups and networking evenings listed on the platform.

Head to myjijievents.com to see everything that’s on right now — the full listings, dates, venues, and ticket links are all there waiting for you.

How to Buy Tickets on Myjiji (It Takes 60 Seconds)

If you haven’t used Myjiji before, here’s how simple it is:

1. Go to myjijievents.com
2. Browse or search for an event that catches your eye
3. Click on the listing to see full details
4. Hit the ticket button and complete your purchase
5. Done — your ticket is confirmed and ready

That’s it. No account hoops to jump through, no complicated checkout. Just find what you want and go.

Why Nairobi's Best Events Are All on Myjiji — And How You Can Be Part of Them
Why Nairobi’s Best Events Are All on Myjiji — And How You Can Be Part of Them

The City Is Moving — Don’t Get Left Behind

Nairobi’s best events don’t wait. The rooftop parties fill up. The intimate shows sell out. The experiences that everyone’s talking about on Monday morning were booked by the people who knew where to look on Thursday.

Myjiji is where those people look. It’s Nairobi’s most complete, most up-to-date, most reliable events platform — and whether you’re discovering something new or planning your whole social month, it’s the smartest place to start.

Don’t miss what’s happening in your city. Find your next event at myjijievents.com today.

Follow Myjiji on social media for weekly event highlights, venue spotlights, and the latest from Nairobi’s social scene.

  • #MyjijEvents
  • #NairobiEvents
  • #ThingsToDoNairobi
  • #NairobiLife
  • #EventsInNairobi

PSC announces over 700 job vacancies; how to apply

1

The Public Service Commission (PSC) has announced a mass recruitment drive targeting professionals across various fields.

In a notice dated May 5, the commission invited qualified candidates to submit applications to fill 764 vacant positions across various government departments.

“Applications are invited from qualified persons for the positions shown below. The details of the posts and mode of application can be accessed on the Commission’s website www.publicservice.go.ke,” the notice reads in part.

According to the notice, PSC is seeking to recruit individuals to fill both entry-level and senior roles.

In the entry-level, PSC is seeking to recruit Trade Development Officers, Weights and Measures Officers, Co-operative Officers, Communication Assistants, Information Officers, Lecturers II and Instructors II.

Senior positions include directors, deputy directors, assistant directors, and principal lecturers.

Candidates will be deployed to serve in various state departments including the State Departments of Internal Security and National Administration, Correctional Services, National Treasury, Roads, Housing and Urban Development, Agriculture, Livestock, Gender and Affirmative Action, Broadcasting and Telecommunications, Sports and Defence.

Other state departments are: Micro, Small and Medium Enterprises Development, Labour and Skills Development, Social Protection and Senior Citizen Affairs, Irrigation, Public Service and Human Capital Development, Technical, Vocational Education and Training, Foreign Affairs, Diaspora Affairs, Blue Economy and Fisheries, Trade and Co-operatives.

How to apply

Interested and qualified applicants are required to submit their applications online through PSC  official website at www.publicservice.go.ke or via the job portal at www.psckjobs.go.ke.

All applications must reach the commission on or before 26th May 2026 at 5:00 pm East African Time.

“Beware of fraudsters soliciting for bribes from the public while masquerading as Commission staff. Public Service Commission does not charge any fee for job applications, shortlisting, interviews or appointments,” the commission said.

Also Read: Kiambu County announces 60 job vacancies for teachers: how to apply

Kiambu County announces 60 job vacancies for teachers: how to apply

0

The Kiambu County government has announced 60 job vacancies for Early Childhood Development and Education (ECDE) Teachers.

In a notice, the Kiambu County Public Service Board invited qualified candidates to submit applications.

“Section 59 of the County Governments Act 2012 outlines the functions of the CPSB among them being “appoint persons to hold or act in offices of the county public service including in the Boards of cities and urban areas within the County and to confirm appointments,” the notice reads in part.

“Pursuant to the above constitutional and legal provision, the Board invites applications from suitably qualified persons who wish to be considered for the positions listed below in the Department of Education Culture, Gender and Social Services,” it adds.

According to the notice, the county is looking for qualified teaching professionals to assist in various roles, including teaching, facilitating play learning activities, mentoring and counselling learners to support the educational development of young children.

Other roles include preparing reports, ensuring the safety and security of learners, preparing learning materials, developing lesson plans and daily activity programmes, assessing and reporting on learner progress, and maintaining professional records.

Requirements for appointment

Applicants must hold a minimum Kenya Certificate of Secondary Education (KCSE) grade of C (Plain). Those with a D+ grade may also apply if they hold a Certificate in Early Childhood Development and Education (ECDE) or a relevant diploma.

Additionally, candidates must be registered with the Teachers Service Commission (TSC), hold a certificate in computer applications, and have at least two years of relevant work experience.

Successful candidates will be hired on contract and compensated as per the Salaries and Remuneration Commission (SRC) scale under Job Group CPSB 11 (H).

How to apply

Interested and qualified candidates are required to download, fill, and submit the Application for Employment Form 26E that can be downloaded from the County Government website.

“ALL applications should be hand-delivered and dropped in the specific box provided at County Public Service Board offices, Room 103, first floor at Thika Sub-County offices between 8.00 a.m. and 5.00 p.m. on weekdays,” the notice adds.

Applications should reach the Board on or before Friday, 29th May, 2026.

ONLY Shortlisted candidates will be required to produce their original identity card, academic and professional certificates and submit clearance from the Kenya Revenue Authority (KRA), Ethics and Anti-Corruption Commission (EACC), and Directorate of Criminal Investigations (DCI).

Clearance from the Higher Education Loans Board (HELB)and Credit Reference Bureau (CRB) will also be required.

“The Board and the County Government of Kiambu is a corruption-free zone. We caution candidates not to fall victim of fraudsters and impersonators who solicit for money with a promise to secure them jobs in the County. The Board shall bear no responsibility for any personal loss arising from such unlawful dealings. Report any such cases to the Police,” the county warned.

The vacancies are open to all applicants, including women, youth, and people living with disabilities.

Also Read: Inside Safaricom’s Sh95.6 billion record-breaking net profit in 12 months

Why Equiloan is emerging as a preferred credit option for salaried workers

Equity Bank’s Equiloan is increasingly becoming a practical financing solution for formally employed Kenyans seeking medium- to long-term credit.

Designed specifically for customers whose employers have signed a Memorandum of Understanding (MOU) with Equity Bank under a check-off arrangement, the loan product offers structured repayment terms and predictable deductions, making it an attractive option for salaried employees.

At a time when many borrowers are seeking affordable, manageable financing, Equiloan stands out for its relatively flexible loan limits and extended repayment period.

The loan is issued through a check-off arrangement, meaning repayment is deducted directly from the borrower’s salary source or automatically deducted from the customer’s account once the salary is received.

Borrowers can access amounts ranging from Sh30,000 up to Sh5 million, depending on their income profile and repayment ability.

The product features a flexible repayment period of up to six years, offering customers the opportunity to spread payments over a longer timeframe and reduce monthly instalments.

How to apply for Equity Bank Equiloan

Applying for Euity Bank’s Equiloan is simple. All customers are required to do is visit the nearest Equity Bank branch, fill out and submit a loan application form.

The application will be appraised by the bank, after which borrowers receive an offer letter if the loan is approved.

Borrowers are required to accept the loan offer, return the signed offer letter, and meet any sanction conditions. Once all requirements are fulfilled, the funds are disbursed into the borrower’s account.

What you need to qualify

To apply for Equiloan, customers are expected to provide key documentation to confirm employment and income stability. These include a payslip, Valid identification documents, and an employment letter (required for check-off loans and salary advance arrangements).

Equity Bank notes that applicable charges for Equiloan are outlined in its official tariff guide available on the bank’s website.

Customers are encouraged to review the tariff guide for a full breakdown of fees and costs associated with the loan product.

Also Read: Equity Bank retains top spot as Kenya’s most valuable brand in 2026

NCBA unit trust funds offer modern pathway to smarter investing for Kenyans

In an era where financial security is increasingly shaped by deliberate planning and disciplined saving, more Kenyans are turning to structured investment solutions that offer both stability and long-term growth.

Among the options steadily gaining traction in the market are Unit Trust Funds, collective investment schemes that allow individuals to pool resources and invest professionally in diversified assets.

As financial literacy improves and the appetite for wealth-building grows, unit trusts are positioning themselves as a critical tool for personal finance, retirement planning, and even institutional investment strategies.

Understanding unit trust funds

Unit Trust Funds are collective investment schemes constituted under a trust deed for the collective benefit of unit holders.

They are designed to allow multiple investors to contribute money into a common pool, which is then invested in a portfolio of assets based on the objectives of the fund.

The investors, commonly referred to as unit holders, receive units proportional to their contribution. These units represent ownership in the fund and determine the share of returns an investor receives.

The structure ensures that investors, regardless of how much they contribute, can access professional portfolio management that would otherwise be out of reach for many individuals.

The demand for unit trust funds has grown significantly in recent years, largely driven by changing economic realities.

Rising costs of living, uncertain job markets, and fluctuating interest rates have forced many households to rethink traditional saving methods.

Rather than relying solely on conventional savings, investors can potentially earn returns through exposure to a variety of assets such as government securities, corporate bonds, money market instruments, or equities.

In Kenya, Unit trust funds are regulated by the Capital Markets Authority (CMA), which plays a central role in ensuring transparency, investor protection, and compliance with financial market standards.

Why NCBA unit trust funds stands out 

NCBA Unit Trust Funds, in particular, have emerged as an attractive vehicle for both first-time investors and seasoned savers seeking a regulated, transparent and professionally managed investment alternative.

The lender says the facility is designed to offer investors access to disciplined investment strategies through a structured and well-governed framework. Their strength lies not only in the investment potential but also in the clarity of their operational model.

Each fund has a stated purpose and a clear investment philosophy or asset allocation strategy. This means investors can select a fund based on personal goals such as capital preservation, income generation, or long-term wealth accumulation.

Unlike informal savings schemes or unregulated investment arrangements, NCBA Unit Trust Funds are established under a trust deed. Under this structure, the unit holder is the beneficiary of the trust deed, meaning the fund is legally set up for the collective benefit of investors.

This arrangement enhances investor confidence because it creates a formal governance framework that ensures the fund is operated according to agreed rules and in the best interests of the unit holders.

It also reduces exposure to operational uncertainty, a common concern in unstructured investment products.

“NCBA Unit Trust Funds are Sponsored by NCBA Bank Kenya PLC and Managed by NCBA Investment Bank. The Trustee of the Funds is KCB Bank Kenya PLC and the Funds Custodian is NCBA Bank Kenya PLC,” NCBA states.

Another notable feature of NCBA Unit Trust Funds is their income distribution approach. The fund manager passes through all income net of expenses to unit holders.

This means that after necessary fund operating expenses are deducted, the returns generated by the fund are transferred to investors.

Unit trust funds are known for their ability to accommodate different investor needs. While some investors prioritize safety and capital preservation, others are willing to accept higher risk in exchange for stronger returns over time.

Recognizing this diversity, NCBA encourages prospective investors to complete a self-administered risk assessment questionnaire before investing.

The lender has placed strong emphasis on convenience, allowing investors to access its Unit Trust Funds through multiple channels.

Investors can purchase and manage their unit trust investments through the NCB NOW App, offering a digital option suited to today’s fast-moving lifestyle.

For clients who prefer in-person service or require additional guidance, manual applications are also available through the NCBA branch network.

Supporting Financial Discipline and Long-Term Planning

Beyond the investment appeal, Unit trust funds are known to encourage disciplined saving. Many people struggle to set aside money consistently due to competing financial pressures.

A structured investment plan through unit trusts can help individuals build habits that lead to long-term financial stability.

For young professionals, unit trusts can serve as a foundation for future wealth creation. For middle-income earners, they can provide a strategic tool for school fees planning, home ownership goals, and emergency financial cushions.

For retirees or individuals approaching retirement, unit trusts may offer a more sustainable way to grow savings while maintaining access to liquidity when needed.

Kenya’s investment culture has expanded rapidly over the past decade. Increased digital access, better financial awareness, and a growing middle class have created demand for products that go beyond traditional banking.

Also Read: Uhuru’s brother Muhoho owns Sh20 billion stake in NCBA Group

Wangaya secures Shs50,000 prize for April player of the month

0

Some players finish games. Kevin Wangaya starts them.

Time and again in April, the Nairobi United forward needed only a moment to tilt matches in his team’s favour, striking first and forcing opponents to chase.

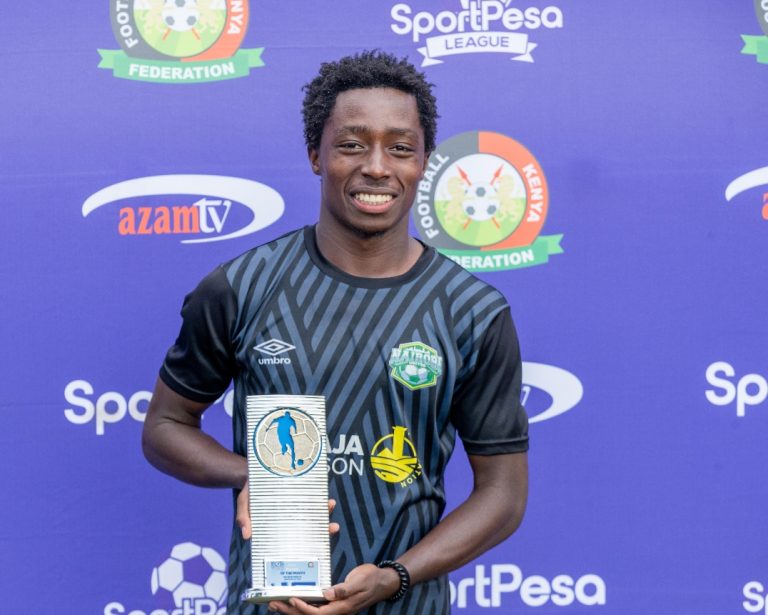
That instinct to land the opening blow earned his side valuable points in April but has also come with individual recognition after he was named the SportPesa Premier League Player of the Month for April.

The Kenya U20 international becomes the second youngest winner of the accolade, following in the footsteps of Kariobangi Sharks’ teenage star Humphrey Aroko, 17, who claimed the award in February.

“I’m really honoured to win this award,” said Wangaya. “Seeing Aroko win it earlier in the season was a big motivation – it showed what’s possible. I’ve just stayed focused, worked hard, and I’m happy to see it paying off,” said the 20-year-old who has represented Harambee Stars at all youth levels.

The 20-year-old, who has featured across all Kenya’s youth national teams and harbours ambitions of representing Harambee Stars at the 2027 Africa Cup of Nations, delivered a standout month, registering three goals and three assists in five matches as Nairobi United went unbeaten.

Waziri 1xCup 2025: The Qualifiers Bring Kenya’s Football Spirit to Life

He opened the scoring in three separate matches – against Mathare United, Posta Rangers, and Mara Sugar – each time giving his side immediate control and a psychological edge. His two assists against Murang’a Seal saw the team rally from a 2-0 deficit to win 4-2 in one of the games of the season.

“I just try to be ready from the first whistle,” added Wangaya. “If we start strong, the whole team grows into the game. But more importantly, we’re fighting for results, and every contribution counts.”

Finishing runners up was Police FC keeper Daniel Ogembo, who recorded four clean sheets, and Naibois teammate Michael Karamor, who netted five goals during the month.

Head coach Godfrey ‘Solo’ Oduor praised Wangaya’s growth and mentality, backing him for bigger stages ahead.

“We challenge our players to push their limits and aim for the highest level, and Wangaya is embracing that,” said Oduor. “He’s been decisive for us, he’s growing in confidence, and this is just the beginning if he stays consistent and hungry.”

Wangaya took home Kes. 50,000 and a customized trophy.

Nairobi United now turn their focus to a highly anticipated clash against Kariobangi Sharks this weekend, a game that sets up a compelling face-off between Wangaya and fellow youngster Aroko.

How to access financing of up to Sh300,000 with Co-op Bank Till number

Till numbers have steadily become a backbone of modern business operations in Kenya, especially among small and medium enterprises (SMEs) that rely on fast, secure and traceable payments.

From retail shops and salons to hardware stores, pharmacies and eateries, the adoption of till numbers has enabled businesses to accept cashless payments conveniently while keeping proper transaction records.

Beyond easing customer payments, till numbers have also become an important financial tool, opening up new opportunities for business owners to access credit based on their daily cash flow.

The Co-operative Bank of Kenya is one of the lenders offering this financing option to businesses using Till Numbers to receive payments.

The product is designed to support biashara operators by offering instant working capital linked directly to their till transactions.

For many SMEs, cash flow remains one of the biggest challenges. Business owners often need quick funds to restock shelves, pay suppliers, cover transport costs or manage urgent operational expenses.

Yet traditional loan processes can sometimes be lengthy, requiring paperwork and waiting periods that do not match the urgency of day-to-day biashara needs.

Co-op Bank’s Till Biashara Loan offers a convenient alternative by enabling eligible traders to borrow instantly based on their till activity.

The facility allows customers to access loan limits ranging from Sh1,000 to Sh300,000, giving entrepreneurs flexible borrowing options depending on the size and performance of their transactions.

The loan is structured for short-term business needs, with repayment periods of 7, 14, or 30 days, allowing traders to match borrowing with business cycles such as weekly or monthly stock turnover.

Co-op Bank customers can access the loan through multiple digital channels. Applications can be made via the Co-op Bank App, the YEA App, or by dialing *667#, making the process accessible even for businesses operating without smartphones.

How to apply for Co-op Bank’s Till Biashara Loan via *667#:

  1. Dial *667# on your phone.
  2. Select E-Loans.
  3. Choose the Till/Biashara Loan option.

Co-operative Bank Group has continued to demonstrate a strong commitment to supporting small and medium-sized enterprises (SMEs), reinforcing its role as a key partner in driving financial inclusion and enterprise growth across the country.

In the Full year ending December 31, 2025, the lender disbursed Sh72.96 billion through its E-Credit platform, a digital credit solution.

Notably, Sh10.43 billion of the total E-Credit disbursements was directed specifically to micro, small and medium-sized enterprises (MSMEs).

This funding provided essential working capital and liquidity support, helping businesses across various sectors to maintain operations, restock, meet obligations, and expand their activities in a challenging economic environment.

Since its inception, the E-credit platform has disbursed more than Sh500 billion. Beyond access to financing, Co-op Bank has also strengthened its MSME value proposition through tailored solutions designed to meet the unique needs of small businesses.

During the year under review, the Bank onboarded more than 259,000 MSMEs onto specialized MSME packages, further expanding its reach within this important segment of the economy.

In addition, the Bank invested in strengthening the capacity of entrepreneurs by supporting over 71,000 MSMEs through training and capacity-building programmes.

Also Read: Inside Safaricom’s Sh95.6 billion record-breaking net profit in 12 months