Home Blog Page 56

Deeping financial inclusion: The Equity Group and MSC partnership in Kenya’s blue economy

0

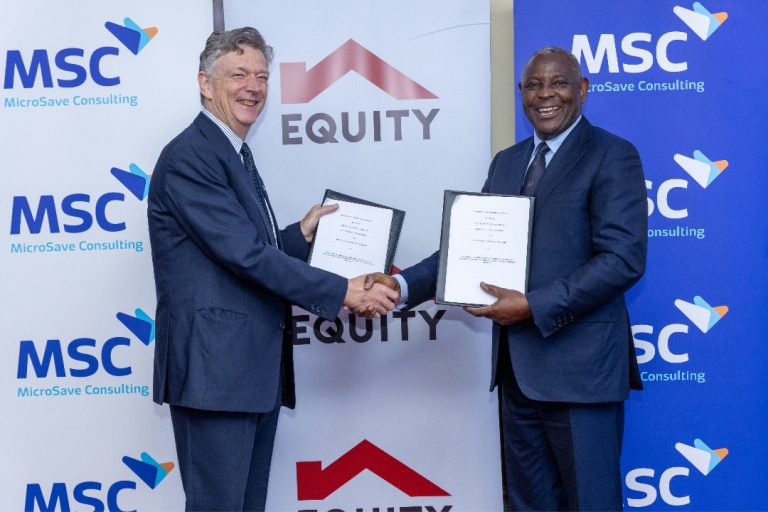
Equity Group and MSC (MicroSave Consulting) have signed a strategic Memorandum of Understanding (MoU) to deepen financial inclusion and advance gender equity within Kenya’s fisheries sector, a partnership that also positions the blue economy as a key driver of sustainable growth.

The collaboration brings together the financial services strength of Equity Bank Kenya, the social impact and capacity-building expertise of Equity Group Foundation, and the global advisory and research capabilities of MSC to address structural gaps in the fisheries value chain. Speaking during the MoU signing in Nairobi, Equity Group Managing Director and CEO Dr. James Mwangi said the partnership aligns with Equity’s long-term vision of transforming livelihoods through inclusive finance, technology, and strategic collaboration.

“This partnership brings together institutions with diverse capabilities, creating a powerful platform to drive impact at scale. The fisheries sector represents a significant but underexploited opportunity. Through this collaboration, we will not only expand financial inclusion but also advance gender equity, strengthen food systems, and support climate resilience,” said Dr. Mwangi.

Dr. Mwangi noted that the initiative will help modernize the fisheries and broader agricultural sectors by integrating digital technologies and data-driven decision-making, positioning them as viable and attractive economic sectors.

“We are transforming agriculture and fisheries from subsistence activities into vibrant economic sectors. By leveraging digital public infrastructure and AI, we aim to elevate these sectors from traditional, informal engagements into modern economic engines that attract capital, improve productivity, and create inclusive opportunities for women to work alongside their sons and daughters while driving food security and economic growth,” he said.

MicroSave Consulting Group Managing Director Graham A.N. Wright said the renewed collaboration comes at a critical time as Africa faces growing challenges around food security, climate change, and inclusion. He added that the partnership will focus on applying data-driven tools and practical digital systems to improve decision-making, strengthen risk management, and support more resilient fisheries livelihoods.

Equity group’s insurance arm emerges as third growth engine

“With climate change and global disruptions threatening food security, I cannot think of a better powerhouse than Equity Bank and the Equity Group Foundation to address these challenges. We aim to create an environment where risks are managed, data is available, and stakeholders, from fishers to traders, can make informed decisions. By linking these communities to tailored financial products and climate-smart solutions, we can address structural barriers and unlock sustainable opportunities for women and youth in the fisheries sector,” Wright said.

The MoU establishes a framework for collaboration focused on fostering a business-oriented mindset in the fisheries sector, promoting financial literacy, and expanding access to tailored financial products for women and youth. Key interventions under the partnership include capacity building through joint training programs, development of climate-smart financial solutions, deployment of technologies such as cold storage infrastructure to reduce post-harvest losses, and the creation of insurance and guarantee mechanisms to de-risk lending.

The program will also support graduation pathways to transition small-scale operators into sustainable commercial enterprises, while expanding market access through partnerships across the value chain. Initial implementation will begin in Kenya, with plans to scale to other markets where Equity operates upon successful execution. The initiative targets a wide range of beneficiaries across the fisheries value chain, including fishers, aquaculture farmers, traders, processors, feed producers, and exporters.

The partnership will also support the design and delivery of high-impact programs across key areas such as financial inclusion, climate resilience, and gender equity. Implementation will be guided by clearly defined project frameworks and coordinated mechanisms to ensure effective execution and measurable impact.

MSC will play a key role in research, baseline assessments, and capacity building, including training both sector players and Equity staff on fisheries dynamics, while Equity Bank will design and deliver tailored financial products aligned to the sector’s unique cycles. Equity Group Foundation will complement these efforts through entrepreneurship training, mentorship, and ecosystem linkages.

This collaboration aligns closely with Kenya’s Vision 2030 by advancing inclusive economic growth, modernizing the fisheries sector, and promoting gender equity, while contributing to the African Union’s Agenda 2063 through sustainable resource management, climate resilience, and the development of integrated value chains.

The partnership also reinforces Equity’s vision of driving private sector–led development financing across Africa, leveraging its Africa Recovery and Resilience Plan (ARRP) to enhance productivity, digital transformation, and financial inclusion while creating sustainable opportunities for women, youth, and communities in the fisheries value chain.
 

NCBA anchors KMRC’s market return with landmark Shs993B sustainability note listing on the NSE

0

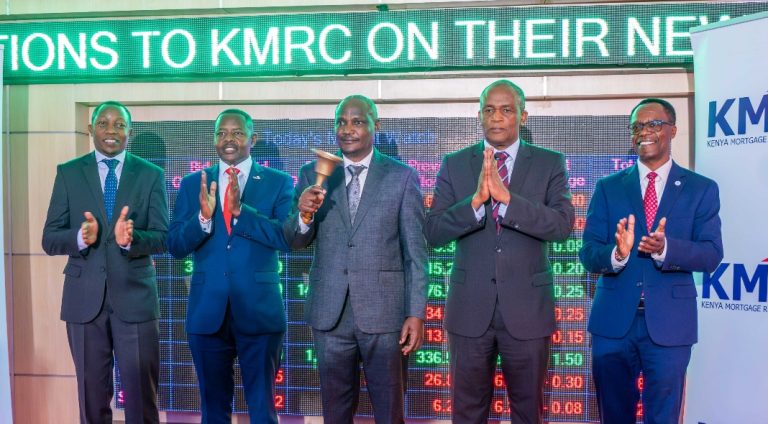
The Kenya Mortgage Refinance Company (KMRC) today listed its shs3 billion Sustainability Bond at the Nairobi Securities Exchange (NSE), after the issuance attracted applications worth shs9.38 billion, an over-subscription rate of 312.8 percent. The listing marks the second successful tranche under the Company’s approved shs10.5 billion Medium-Term Note Programme. It follows the Company’s inaugural Shs1.4 billion issuance in 2022, which attracted applications worth Shs8.5 billion.

Proceeds from the Sustainabil

Refinanced over Shs30 billion in home loans

Supported more than 5,800 homeowners

Expanded its reach across 39 counties

Advanced inclusive homeownership, with nearly half of refinanced loans benefiting women.

By providing long-term liquidity to primary mortgage lenders, KMRC supports fixed-rate, single-digit home loans with longer repayment periods, helping reduce monthly repayment burdens for qualifying borrowers.

KMRC Board Chairman Dr. Haron Sirima said the listing demonstrates the power of capital-market instruments in financing development outcomes.

“This listing reflects growing confidence in KMRC’s mandate, governance, and long-term contribution to Kenya’s housing sector. It demonstrates that affordable housing can be supported through market-based instruments that deliver financial returns alongside measurable social and environmental impact,” said Dr. Sirima.

NCBA personal loans offer borrowers financing of as low as Sh50,000

Hon. John Mbadi, Cabinet Secretary for the National Treasury and Economic Planning, underscored the national significance of the milestone.

“The successful issuance and listing of this Shs3 billion Sustainability Note is a national milestone. It signals a decisive shift in how we mobilize capital to finance development priorities, particularly housing. It also affirms that Kenya’s capital markets are deepening, diversifying, and maturing in line with our long-term economic aspirations,” said Hon. Mbadi.

NCBA Group Managing Director, speaking at the listing said, “The successful listing of KMRC’s Sustainability Bond reflects the strength of long-standing partnerships and the importance of execution expertise in delivering complex capital market transactions. As Lead Arranger, NCBA is proud to have supported KMRC in structuring and bringing this transaction to market, mobilizing long-term funding for Kenya’s affordable housing sector. This builds on our continued collaboration with KMRC across multiple structured finance transactions. Our integrated Corporate and Investment Banking and Investment Bank teams bring strong technical expertise and market insight, reinforcing our role as a trusted advisor in delivering impactful, sustainable financing solutions.”


Allan Kilavuka walks away from KQ with Sh131 million in pocket

0

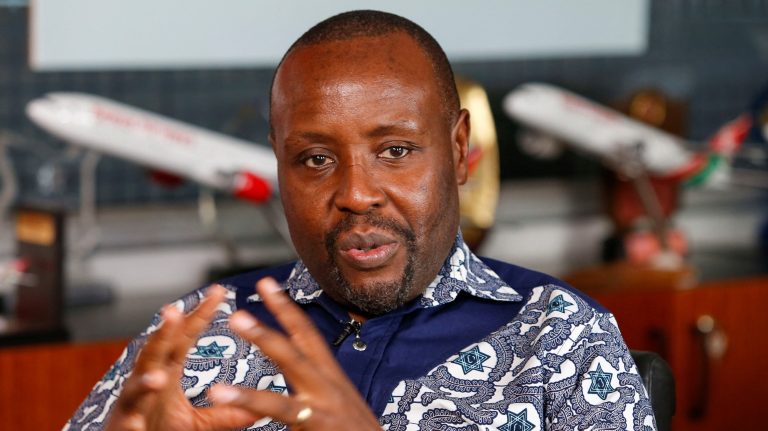
Former Kenya Airways Chief Executive Officer Allan Kilavuka walked away from the national carrier with a pay package of Sh131 million.

This amount is inclusive of his pension and benefits and was revealed by the airline in its latest annual report.

In the report, Kilavuka’s 2025 compensation is seen to have risen by 77 percent from the Sh74 million that he had pocketed in the previous 2024 financial year.

His basic pay was Sh55.6 million while pension and benefits amounted to an extra Sh75.3 million.

“Pensions and other benefits include terminal benefits amounting to Sh15 million and other contractual obligations of Sh48 million that arose in the year 2025,” the national carrier stated in the report.

Kilavuka left Kenya Airways after serving as the Group Managing Director and Chief Executive Officer for a period of six years. His exit was announced by the national carrier on December 16, 2025.

Following his exit, Kenya Airways has appointed Captain George Kamal as the acting Managing Director and chief executive officer. Mr. Kamal has been serving as the company’s Chief Operating Officer (COO).

Kilavuka left the airline as the first CEO in over a decade to see the carrier return a profit, a fete that was achieved in 2024 when Kenya Airways made its first net profit of Sh5.4 billion for the first time in over eleven years.

In that year, KQ also recorded the highest revenue, passenger numbers and freight volumes in its history.

“It has been an extraordinary six-year journey. I am genuinely proud and continually amazed by how much we have accomplished as one team. Together, we have transformed our airline into a resilient, respected and award-winning airline,” he had said.

Kilavuka’s final year, though, was one of the most challenging for the airline, with an annual net loss of Sh17.2 billion.

The national carrier blamed this heavy loss on the grounding of its wide body Dreamliner planes that were due for engine overhauls.

“Overall performance and operations in the year 2025 were severely impacted primarily by the temporary grounding of three of the wide body fleet, Boeing 787-8 Dreamliner aircraft. This was driven by the global supply chain constraints and limited engine availability,” Kenya Airways had said in a statement.

In that full year, total income fell by 14.3 percent to Sh161.5 billion. Total assets increased by 2.3 percent to Sh183.2 billion while non-current assets went up by 3.1 percent to Sh141.8 billion. Total liabilities went up by 6. percent to Sh315.3 billion.

Ruto govt spends Sh1.1 trillion on office supplies like tea, snacks, fuel in 9 months

During the 2025 financial year, Available Seat Kilometres (ASKs) declined by 18 percent to 13,349 million, while passenger numbers dropped by 13 percent.

“While our financial performance reflects a challenging year, it is important to recognize that this was driven primarily by global supply chain disruptions and not a lack of demand,” said Kenya Airways Chairman, Kiprono Kittony.

The national carrier had already issued a profit warning to shareholders following a challenging year in which it recorded a half year net loss of Sh12.15 billion.

Investing in TRIFIC: A guide to Kenya’s new green, Dollar-yielding asset class

0

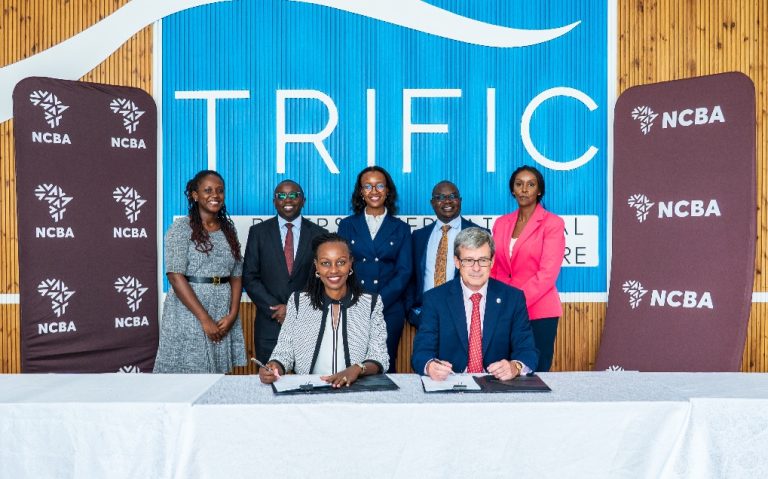
The Two Rivers International Finance and Innovation Centre (TRIFIC) Special Economic Zone has opened a Sh4.8 billion (USD 37.3 million) Green, USD-denominated Income Real Estate Investment Trust (I-REIT) to fund the acquisition of the TRIFIC North Tower and the development of other premium, environmentally sustainable commercial towers within its Special Economic Zone (SEZ).The offer opens from tomorrow, May 13th and closes on June 12,

2026.Present at the launch were the Centum Investment Company PLC Group CEO Dr James Mworia, the TRIFIC CEO Brenda Mbathi, the Managing Director KCB Investment Bank Maurice Opiyoand NCBA Bank Kenya Managing Director, James Gossip.The TRIFIC I-REIT will be one of Kenya’s first USD-denominated Green, income-distributing REIT, creating a new asset class for investors seeking stable dollar yields with measurable impact.

“This offer is unrestricted and therefore open to both institutional and retail investors, the I-REIT investors will effectively earn a stable share of the export revenues of a diversified portfolio of global service firms operating from TRIFIC, making this one of the most future-oriented, realestate income products in the region,” said Ms Mbathi. Allotment to successful investors will be made on June 15 2026, while results of the offer and processing of refunds will be made on the following day.It will be listed on June 23 for trading on the Main Investment Market Segment of the Nairobi Securities Exchange (NSE).

“With the minimum subscription amount set at Sh129,000 ($1,000), this offer is within reach of most investors seeking a stake in Kenya’s real estate sector,” said the KCB Investment Bank Managing Director, Maurice Opiyo. KCB is the transaction advisor, sponsoring broker and lead placing agent for the offer.Proceeds of the I-REIT will be invested exclusively into green-certified commercial towers built to international sustainability standards.

NCBA personal loans offer borrowers financing of as low as Sh50,000

The tenants occupying TRIFIC facilities are mainly global service exporters including Business Process Outsourcing (BPO) firms, tech firms, shared services centres, and professional services companies who serve clients across the world and create high-quality, export-oriented jobs for Kenyan professionals. Ms Mbathi noted that the long-term, dollar-based leases with guaranteed annual escalations, combined with TRIFIC’s embedded service-support model, create a reliable and growing income stream for investors.Income REIT regulations under the Capital Markets Authority require distribution of at least 80% of net profits as tax-exempt dividends, further enhancing investor returns.

The North Tower, offering over 16,000 square metres of lettable area, is already 92% leased to multinational service-exporting firms. Planning for a second tower is underway in response to growing demand.Located within Nairobi’s secure diplomatic blue zone, TRIFIC is the only private services-focused SEZ in Nairobi, offering world-class infrastructure, regulatory facilitation, and integrated businesssupport services.

TRIFIC occupies 64 acres within the 106-acre Two Rivers Development and has operated under its SEZ licence since June 2023.It is designated as a Project of Strategic National Importance (PSNI) and is fully aligned with Kenya’s Vision 2030 Agenda. Its growth supports national priorities including scaling globally traded services, attracting highvalue foreign direct investment (FDI), generating high-quality jobs, and expanding green and sustainable urban development.


Kenya’s digital billions are already here. Who will claim them?

0

Kenya has now concluded public consultations on the Draft Virtual Asset Service Providers (VASP) Regulations, 2026. These rules will operationalise the VASP Act passed last November and, for the first time, bring Kenya’s digital asset economy under the protection of law.

What is often interpreted as regulatory constraint is, in fact, recognition that an emerging market has matured into economic relevance. Digital assets have moved well beyond theory.

They are functioning financial instruments that exist entirely online, recorded on blockchains rather than stored in banks, and range from cryptocurrencies such as Bitcoin to stablecoins like USDC and newer innovations including tokenised bonds and digital property rights.

This journey began in October 2008, when Satoshi Nakamoto introduced Bitcoin, a system of money independent of banks and governments. Since its launch, Bitcoin has evolved from a niche technological experiment into a global market valued at over 2.4 trillion dollars.

Capital Stablecoin transactions alone exceeded $34 trillion in 2025. Ironically, the institutions Bitcoin sought to bypass are now among its most active participants.

Closer to home, the digital asset market has already reached meaningful scale. Chainalysis  data cited in Absa research shows that Kenya accounted for over 18 billion dollars of the more than 205 billion dollars in digital asset value received across Sub‑Saharan Africa in the period from June 2024 to 2025 ranking fourth in the region.

Nearly 13 percent of Kenyans now use digital assets for everyday economic activity. Adoption has been driven by practicality, but until now this 18‑billion‑dollar market has operated without the protections expected of a formal financial system.

The draft regulations are intended to close the trust gap by introducing joint oversight, strong capital requirements, and clear standards for governance, consumer protection, and market integrity.

By embedding safeguards around transparency, security, and financial crime, the framework allows credible institutions to participate with confidence and positions digital assets as bankable forms of collateral.

The next frontier is using regulated digital assets to unlock credit. Imagine a future where businesses can use digital holdings as collateral for loans rather than selling them. This transforms speculative coins into productive capital.

The payments challenge

It is easier today for a Kenyan business to pay a supplier in London than one in Kampala or Lagos. Remittance costs into Africa remain high, averaging 8 percent.

The African Continental Free Trade Area promises scale, but without efficient payments, that promise will remain theoretical. Stablecoins offer a practical solution, allowing for fast, low-cost, instant settlement.

Based on the available data, we estimate the stablecoin inflows into Kenya were roughly $8 billion in 2025. The demand is already here; what has been missing is a safe framework within the financial system.

Global players are moving quickly. M-Pesa Africa is expanding blockchain infrastructure across multiple markets, while JPMorgan processes billions in daily on-chain transactions. The question is not whether this shift is happening, but whether Kenya will capture its share.

Kenya is not late

Kenya has a long track record of leading financial innovation. The Central Bank’s decision to allow M‑Pesa to scale before regulation caught up transformed access to financial services and positioned Kenya as a global reference point.

With peers such as Nigeria and Ghana only recently adopting similar laws, the VASP framework offers a comparable opportunity.

Absa research across five African markets shows strong local demand. In Kenya, 91 percent of respondents believe digital assets can improve cross-border payments, while 67 percent expect to increase usage within three years. Kenyans are not waiting for reasons to adopt; they are waiting for safe, reliable access.

Still, regulation alone is not enough. High capital requirements could unintentionally exclude smaller innovators. Supervising blockchain systems will demand new technical capacity, and regulators must remain agile.

Financial institutions also carry responsibility, not just to offer products, but to educate. Many Kenyans are already in the market without fully understanding the risks. Trust cannot be legislated; it must be built through knowledge and inclusion.

The coming into force of these regulations may not arrive with fanfare, but it will mark a turning point. Kenya will have formally decided that millions of digital asset users deserve the same institutional protection as every other participant in the financial system.

That is the foundation on which a credible, competitive, and inclusive digital asset market can be built.

By Stella Mambo, the Global Markets Director at Absa Bank Kenya

Also Read: Jet A-1 is not Kerosene and other interesting facts 

NCBA personal loans offer borrowers financing of as low as Sh50,000

Access to quick and flexible credit can often be the difference between stalled ambitions and life-changing progress.

Whether it is paying school fees, expanding a small business, acquiring an asset, or handling an unexpected financial emergency, timely financing has increasingly become an essential financial tool for many Kenyan households navigating today’s dynamic economy.

It is through this reality that financial institutions are rolling out tailored products to meet consumer expectations.

NCBA Bank is one of the lenders leading this transformation through its personal loan facilities. Under this financing option, borrowers can access both secured and unsecured financing.

NCBA personal secured loan

This facility is designed for customers seeking accessible financing tailored to their lifestyle and repayment ability.

According to the lender, the facility is designed to help customers acquire assets, meet personal goals, and manage pressing financial obligations through both secured and unsecured lending options.

Among the key features of the facility is flexibility in loan access, with borrowing available in Kenya Shillings, US Dollars, Sterling Pounds, and Euros.

Customers can access loans starting from Sh50,000, while the maximum amount is determined by an individual’s repayment capacity and verified income streams.

NCBA further notes that applicants can qualify using salary income or other reliable income sources, subject to verification through bank statements.

Interest is charged on a reducing balance basis, a structure that allows borrowers to gradually reduce the amount of interest paid as they continue servicing the loan.

For 34-year-old Nairobi entrepreneur Miriam Wanjiku, the loan facility provided critical support at a time when her business needed expansion capital.

“I had been planning to purchase additional salon equipment for months, but cash flow constraints kept delaying the investment. The loan application process was straightforward, and the financing allowed me to expand the business sooner than expected,” she said.

She added that the flexible repayment structure gave her confidence to borrow without disrupting the day-to-day operations of her business.

NCBA personal unsecured loan

NCBA’s unsecured personal loan offering is structured to cater to both employees whose organisations have agreements with the bank and individuals seeking independent financing without employer involvement.

Under the Check-Off Loan arrangement, employees of partner organisations can borrow between Sh50,000 and Sh6 million, with repayment periods of up to 96 months.

Monthly instalments are conveniently deducted directly through employers, easing the repayment process for borrowers.

For individuals seeking greater independence, the Non-Check-Off Loan provides financing of up to Sh5 million without the need for collateral or employer guarantees.

The facility is available to salaried customers who have maintained an active NCBA account for at least six months, with repayment terms extending up to 60 months.

A key attraction of the facility is its flexibility. Customers can borrow in Kenya shillings, US dollars, Sterling pounds or Euros, provided their income matches the chosen currency.

The loans also come with Credit Life and Retrenchment Insurance, offering protection in cases such as retrenchment, accidental permanent disability or accidental death.

The bank also provides a balance transfer option, allowing borrowers to consolidate loans from other financial institutions into a single repayment plan that is easier to manage and potentially more cost-effective.

Requirements to access NCBA unsecured personal loan

NCBA notes that customers interested in the unsecured personal loan facility must provide a valid Kenyan ID or passport, KRA PIN, recent pay slips, and a duly completed application form.

Employees applying for check-off loans are also required to provide an employer introduction letter.

Also Read: Why more employees are turning to NCBA salary account

Jet A-1 is not Kerosene and other interesting facts 

Jet A-1: Petroleum products have dominated headlines in recent weeks, a reminder that modern economies run not merely on confidence and credit, but on hydrocarbons. From matatus to manufacturing plants, and from cargo ships to cabinet meetings, much of economic life remains, quite literally, fuelled by oil from the Middle East.

Aviation, predictably, has not escaped the turbulence. Yet while other sectors have protested soaring fuel prices with strikes and indignation, airlines have carried on with the stoicism of long-suffering aristocrats, quietly absorbing eye-watering increases in the cost of Jet A-1. Here, then, are five curious facts about the fuel that keeps humanity improbably aloft.

1. Jet A-1 is Kerosene’s far more accomplished cousin

To the untrained eye, Jet A-1 may resemble the ordinary kerosene still used in parts or rural Kenya for cooking and lighting. This is rather like mistaking a neurosurgeon for a village barber because both own sharp instruments. Jet A-1 does indeed belong to the broader family but it is a highly specialised aviation fuel engineered exclusively for turbine-powered aircraft.

Subjected to rigorous refining and filtration, it is designed to remain relatively stable under conditions that would make lesser fuel lose composure entirely. At cruising altitude, where temperatures plunge to arctic extremes, Jet A-1 resists freezing. Near roaring turbines generating extraordinary heat, it avoids combustion instability. In aviation, where reliability is prized only slightly less than gravity, such properties are not luxuries but necessities.

Seven golden rules of air travel

2. Jet A-1 may be the world’s fussiest liquid

Few substances endure scrutiny like Jet A-1, the kerosene cocktail upon which modern aviation precariously relies. Commercial airlines operate under a remarkably uniform global standard, meaning that whether fuel is loaded in Nairobi, Nagoya or New York, the rules governing it are largely the same.

From refinery to wing tank, every transfer is monitored with almost clerical devotion. Such paranoia is justified. Jet fuel possesses an inconvenient fondness for water, which, if allowed to linger, can invite corrosion, contamination and the sort of engineering surprises best avoided at 35,000 feet.

3. Jet Fuel enjoys a tax status most citizens can only dream of

Unlike the kerosene used in households, Jet A-1 enters the country largely unmolested by ad valorem taxes and sundry levies. The logic is less generous than survival. Taxing aviation fuel too heavily would amount to charging international airlines twice over, while simultaneously making air travel so ruinously expensive that only oligarchs and conference panellists could afford it.

These exemptions are not, therefore, acts of charity towards airlines but lubricants for global commerce itself. They help keep airfares, cargo costs and the delicate choreography of international logistics within the realm of the economically tolerable.

Recent tax reliefs on kerosene, despite predictable public suspicions, were not designed to pamper Jet A-1. Aviation fuel already bears little beyond shipping costs and an administrative fee imposed by importers. In the curious hierarchy of modern taxation, the fuel that powers a grandmother’s stove is treated more sternly than the fuel that powers a Boeing at 35,000 feet.

Things to know about cheap flight tickets, lost luggage, and overbooked flights

4. The tyranny of Jet Fuel

Even after generous tax exemptions, Jet A-1 fuel remains punishingly expensive. For some airlines, it devours as much as 60 per cent of operating costs, a finance cost more suited to a hedge fund than a hydrocarbon. Meanwhile, carriers in the Middle East, perched conveniently atop roughly a fifth of the world’s oil reserves, feast in heavily subsidized fuel. The result is a competitive advantage so vast that rivals elsewhere may as well be attempting flight with the parking brake engaged.

5.⁠ ⁠Safety first, suitcases second, maybe third

Aircraft rarely leave the tarmac with merely enough fuel to reach their destination. Airlines and pilots must account for the whims of weather, stubborn headwinds and the occasional diversion to an alternate airport. Prudence in aviation is measured in kilograms of Jet A-1. Sometimes forecasts suggest that a journey may prove longer or less straightforward than planned.

In such cases, a pilot may elect to carry additional fuel. Yet fuel is heavy, and aircraft are creatures of unforgiving arithmetic: more fuel means more weight. To remain within safe operating limits, passengers and cargo may therefore need to be offloaded.

Such decisions are not acts of commercial convenience, let alone airline caprice. They are made for one reason alone: safety, the industry’s most expensive and least negotiable obsession.

Co-op Bank Call Deposit Account is the solution you need for wealth creation

As more Kenyans seek safe and flexible ways to grow their money amid changing economic conditions, demand is rising for investment products that combine accessibility with competitive returns.

One such option gaining attention among individuals and businesses is the Co-operative Bank of Kenya’s Call Deposit Account.

The account is designed for customers looking to invest surplus funds for an indefinite period while still retaining the flexibility to access their money when needed.

Unlike fixed-term investments that may tie up money for months, the account allows withdrawals after a minimum holding period of 7 days, provided 24 hours’ notice is given to the bank.

This arrangement makes it suitable for individuals, businesses, chamas and institutions managing short-term liquidity needs.

For many customers, the account offers a balance between accessibility and financial growth.

Nairobi-based entrepreneur Grace Wanjiku says the account has helped her better manage business cash flows while still earning returns on idle funds.

“Previously, money would remain in the current account earning nothing as we waited for supplier payments or upcoming expenses. With the call deposit account, the funds continue to work for us while remaining accessible when needed,” she said.

The flexibility attached to the account has also made it appealing to small and medium-sized enterprises that often require quick access to operating capital.

David Mwangi, who runs a logistics company in Nakuru, says the account has enabled him to plan more efficiently during periods of fluctuating business activity.

“One can ‘call’ or withdraw the funds any time, subject to a minimum period of 7 days and prior notice of 24 hours,” Co-op Bank states.

Beyond financial management, the Co-op Bank call deposit account has been hailed for its ability to instill financial discipline among savers.

With withdrawals requiring a prior notice, customers are encouraged to plan ahead while avoiding impulsive spending of funds meant for investment or operational stability.

The product also provides an alternative for customers seeking better returns than ordinary savings accounts without committing to long-term fixed deposits.

This flexibility is particularly beneficial in an environment where businesses and households are increasingly prioritising liquidity alongside financial growth.

“The Bank reserves the right to adjust the applicable interest rates at its sole discretion, providing a 7-day notice before any change to the rate or rates of interest payable,” Co-op Bank adds.

To get started, customers can do so via the Co-op Bank mobile app available on Google and App Stores, or visit the nearest Co-op Bank branch countrywide.

Also Read: The key in your Inbox: Why protecting your email is the secret to keeping your bank account safe

Most lucrative careers in Kenya in 2026 and their salaries

Kenya’s job market is changing rapidly. While unemployment remains high, professionals with specialized skills in technology, healthcare, finance, engineering, aviation, and international development continue to command high salaries and strong career growth.

Today, the most lucrative careers in Kenya are no longer determined only by academic qualifications. Employers are increasingly rewarding:

  • Technical expertise
  • Digital skills
  • Global competitiveness
  • Leadership ability
  • Problem-solving capacity

According to the latest Kenya National Bureau of Statistics (KNBS) labour data, sectors such as electricity and energy, financial services, aviation, technology, and international organizations remain among the highest-paying industries in the country.

Below is a list of the most lucrative careers in Kenya in 2026, the average salaries professionals earn, and why these professions continue to dominate the labor market.

Top 20 Highest Paying Jobs in Kenya and Monthly Salaries (2026 Update)

What are the most lucrative careers in Kenya?

The most lucrative careers in Kenya are mainly concentrated in:

  • Medicine and surgery
  • Banking and finance
  • Software engineering and AI
  • Aviation
  • Energy and engineering
  • Corporate leadership
  • International NGOs and diplomacy
  • Law and corporate consulting

Senior professionals in these sectors can earn between KSh 300,000 and KSh 10 million per month, depending on experience, employer, and regional responsibility.

1. Medicine and specialized surgery

Average monthly salary: KSh 150,000 – KSh 2 million+

Medicine remains one of the most lucrative and respected careers in Kenya.

Medical specialists such as:

  • Neurosurgeons
  • Cardiologists
  • Anesthesiologists
  • Radiologists
  • Orthopedic surgeons

Earn exceptionally high incomes due to skill scarcity and the long training period required.

Doctors working in:

  • Private hospitals
  • International NGOs
  • Overseas contracts
  • Specialized clinics

Often earn significantly above the national average.

Top-paying medical fields include:

  • Surgery
  • Radiology
  • Cardiology
  • Dentistry
  • Anesthesiology
  • Neurosurgery

Lucrative Careers in Kenya with Salaries Exceeding Ksh 500,000

2. Software Engineering and Artificial Intelligence

Average monthly salary: KSh 120,000 – KSh 800,000+

Technology careers are now among the fastest-growing and highest-paying professions in Kenya.

The rapid expansion of:

  • Fintech
  • AI
  • Cloud computing
  • Cybersecurity
  • E-commerce
  • Digital banking

hHas created massive demand for skilled tech professionals.

Top-paying tech careers include:

  • Software Engineers
  • AI Engineers
  • Data Scientists
  • Cloud Architects
  • Cybersecurity Specialists
  • DevOps Engineers

Some Kenyan software engineers working for regional and international firms now earn salaries exceeding KSh 350,000 per month.

Many remote developers are also increasingly earning dollar-based salaries.

6 high-paying jobs and careers in Kenya

3. Aviation and Piloting

Average monthly salary: KSh 250,000 – KSh 2.5 million

Pilots remain among the highest-paid professionals in Kenya because of:

  • Expensive training
  • Licensing requirements
  • High responsibility
  • Skill scarcity

Senior airline captains and aviation executives working for international carriers can earn multi-million-shilling annual packages.

Top aviation careers include:

  • Commercial Pilots
  • Airline Captains
  • Aviation Engineers
  • Air Traffic Controllers
  • Flight Operations Managers

4. Banking and Financial Services

Average monthly salary: KSh 200,000+

Kenya’s banking sector remains one of the most lucrative employment industries.

According to the KNBS labour reports, employees in financial and insurance services are among the country’s top earners.

Top-paying careers in finance include:

  • Investment Banking
  • Treasury Management
  • Risk Management
  • Financial Analysis
  • Corporate Finance
  • Actuarial Science

Senior executives in banks often earn millions annually through:

  • Salaries
  • Bonuses
  • Shares
  • Allowances

Most marketable courses in Kenya today (2026 Guide)

5. Corporate Executives and CEOs

Average monthly salary: KSh 500,000 – KSh 30 million+

Chief executives of banks, listed firms, telecommunications companies, and multinationals are among the highest-paid individuals in Kenya.

According to online discussions and executive compensation reports, some Kenyan CEOs earn over KSh 30 million monthly.

Top executive positions include:

  • CEO
  • CFO
  • Managing Director
  • Chief Technology Officer
  • Regional Director

Executive compensation is often tied to:

  • Company performance
  • Regional oversight
  • Profitability
  • Stock ownership

6. Engineering and Energy

Average monthly salary: KSh 180,000 – KSh 1 million+

Employees in:

  • Electricity
  • Petroleum
  • Infrastructure
  • Geothermal energy
  • Engineering consulting

Remain among Kenya’s top earners.

KNBS data shows workers in the electricity and gas sector earn average monthly salaries above KSh 218,000.

Top engineering careers include:

  • Petroleum Engineering
  • Electrical Engineering
  • Civil Engineering
  • Geothermal Engineering
  • Mechatronics Engineering

Kenya’s growing infrastructure and energy investments continue to support strong demand.

How to apply for cruise ship jobs in Kenya

7. International NGOs and Diplomacy

Average monthly salary: KSh 250,000 – KSh 1.5 million+

Professionals working for:

  • United Nations agencies
  • Embassies
  • Development agencies
  • Global NGOs

Remain among Kenya’s highest earners.

According to KNBS data, workers in extraterritorial organizations are the highest-paid employees in Kenya.

Top NGO careers include:

  • Program Directors
  • Economists
  • Policy Advisors
  • Public Health Experts
  • Monitoring & Evaluation Specialists

These jobs are attractive because they often pay in foreign-funded salary structures.

8. Law and Corporate Legal Practice

Average monthly salary: KSh 150,000 – KSh 1.5 million

Corporate lawyers and legal consultants continue to earn high salaries in Kenya, especially in:

  • Commercial law
  • Tax law
  • Constitutional law
  • International arbitration
  • Intellectual property law

Senior partners in elite law firms can earn millions annually.

Top legal employers include:

  • Multinational corporations
  • Top law firms
  • Banks
  • Government agencies
  • International organizations

The Captain’s Club: Where visionaries meet, unite and succeed

9. Actuarial Science

Average monthly salary: KSh 150,000 – KSh 600,000+

Actuarial Science remains one of the most marketable and lucrative careers in Kenya.

Actuaries are highly valued because they help companies:

  • Assess risk
  • Model financial uncertainty
  • Manage investments
  • Design insurance products

They mainly work in:

  • Insurance
  • Banking
  • Pensions
  • Investment firms

The profession has relatively few qualified experts, increasing salaries significantly.

10. Digital Marketing and Content Economy

Average monthly salary: KSh 80,000 – KSh 500,000+

The rise of:

  • Social media
  • Influencer marketing
  • E-commerce
  • YouTube
  • AI marketing
  • Digital publishing

Has created a fast-growing digital economy in Kenya.

Professionals with skills in:

  • SEO
  • Performance advertising
  • Social media strategy
  • Content marketing
  • AI-assisted marketing

Are increasingly attracting strong salaries and consulting opportunities.

Some top creators and digital consultants now earn more than traditional corporate employees.

How 28-year-old lady moved from Sh. 858k salary to Sh. 2.2mn salary within 5yrs

Most Lucrative Careers in Kenya — Salary Comparison Table

Career Average Monthly Salary KSh
Specialized Doctors 150K – 2M+
Software Engineering & AI 120K – 800K+
Piloting & Aviation 250K – 2.5M
Banking & Finance  200K+
CEOs & Executives  500K – 30M+
Engineering & Energy  180K – 1M+
International NGOs  250K – 1.5M+
Corporate Law  150K – 1.5M
Actuarial Science  150K – 600K
Digital Marketing  80K – 500K+

Why These Careers Pay Highly

The most lucrative careers in Kenya usually have several things in common:

  • Long training periods
  • Technical specialization
  • High responsibility
  • Global relevance
  • Talent scarcity
  • Direct impact on revenue generation

Employers pay premium salaries where replacing skilled professionals is difficult and expensive.

Maina Kageni: I got my first Sh42,000 salary job after high school. I don’t have a degree

Careers Expected to Grow Fastest in Kenya

The careers likely to experience the strongest growth over the next decade include:

  • Artificial Intelligence
  • Cybersecurity
  • Cloud Computing
  • Data Science
  • Renewable Energy
  • Digital Finance
  • Healthcare
  • Agritech

Global digital transformation is increasingly influencing Kenya’s labor market and salary structure.

Important Reality About Lucrative Careers

One major trend in Kenya today is that degrees alone are no longer enough.

Many employers increasingly prioritize:

  • Practical skills
  • Certifications
  • Experience
  • Communication ability
  • Adaptability
  • Digital literacy

Online discussions among Kenyan professionals also show growing frustration among graduates who expect high salaries immediately without building experience first.

The professionals earning the highest incomes today are usually those who continuously:

  • Upgrade skills
  • Build networks
  • Solve complex problems
  • Adapt to market changes

How do I survive on Sh12,000 salary and two baby mamas?

FAQs About Lucrative Careers in Kenya

Which career pays the highest salary in Kenya?

Corporate executives, specialized surgeons, airline captains, and senior banking executives are among the highest-paid professionals in Kenya.

Which course leads to the most lucrative career in Kenya?

Medicine, software engineering, actuarial science, aviation, engineering, and finance are among the best-paying career paths.

Are tech careers lucrative in Kenya?

Yes. Careers in software engineering, AI, cybersecurity, and cloud computing are increasingly among the highest-paying professions.

Which industries pay the best in Kenya?

Energy, banking, aviation, international NGOs, and technology remain among Kenya’s top-paying sectors.

Conclusion

Kenya’s labour market is becoming increasingly skills-driven and globally competitive. The most lucrative careers today are concentrated in industries that combine technical expertise, innovation, leadership, and global demand.

For students and young professionals, the long-term opportunity is no longer simply obtaining a degree. It is developing rare, adaptable, and commercially valuable skills that can compete both locally and internationally.

The key in your Inbox: Why protecting your email is the secret to keeping your bank account safe

0

When we think about bank security, we usually picture heavy vault doors, complex PINs, and secure mobile banking apps. Rarely do we think about our personal email addresses.

Yet to a cybercriminal, access to your email inbox can be the ultimate gateway to your finances.

Today, scammers are increasingly targeting customer email accounts as a backdoor to their bank accounts.

Let’s look at how this happens, how to spot the warning signs, and the simple steps you can take today to lock your digital front door.

How to keep your bank account safe from fraudsters

How a Hacked Email Leads to a Swiped Bank Account

You might wonder, ”How can someone access my bank account just by getting into my email?” Here are the common tactics scammers use once they gain access to your inbox:

  1. The Forgot Password Trick: If a scammer knows your email address and has hacked into it, they can go to your online banking portal, click “Forgot Password,” and have the reset link sent straight to your email. Since they are already logged into your inbox, they reset your password, log into your bank account, and transfer funds.
  2. The Paper Trail Hunt: Scammers search your inbox and “Sent” folder for keywords like “statement,” “OTP,” “PIN,” “ID copy,” or “bank.” Armed with this personal information, they can easily impersonate you or trick customer service into giving them access to your accounts.
  3. Deleting the Evidence: Once they perform a transaction, they delete the bank notification emails from your inbox and “Trash”folder so you don’t notice anything iswrong until it’s too late.

Kaa Chonjo: Equity continues to sensitize customers on secure banking

Red Flags: How to Tell if Your Email is Hacked

  • The Sudden Silent Inbox: You notice you aren’t receiving any new emails, or you miss important notifications.
  • Unusual Password Reset Emails: You receive emails asking you to reset passwords for accounts you didn’t request.
  • The Device Alert Notification: Your email provider sends a notification that a new device (e.g., from a different city or country) has logged into your account.
  • Sent Folder Surprises: There are emails in your Sent folder that you never wrote.

Avoid Financial Fraud: Joseph’s Story and Essential Safety Tips

Kaa Chonjo! 4 Easy Steps to Protect Your Email and Your Money.

Protecting your bank account starts with securing your email. Here is your checklist to stay safe today:

Step 1

Set Up 2-Factor Authentication (2FA) on Your Email: This is your strongest shield. When enabled, anyone trying to log into your email from a new device will need a code sent to your phone. Even if a scammer guesses your password, they can’t get in without your phone.

Step 2

Create a Strong, Unique Password: Never use the same password for your email that you use for your bank account or social media. Make it a phrase that is easy for you to remember but hard for a computer to guess.

Step 3:

Clean Out Your Inbox: Delete old emails that contain sensitive documents like bank statements, photos of your ID, or utility bills. If scammers do get in, don’t leave them a treasure map.

Step 4:

Keep an Eye Out for 0763 000 000: Remember, Equity will only call you from 0763 000 000. If anyone calls claiming to be from Equity asking for your email, password, OTP, or PIN—even if they claim your account is blocked—hang up immediately.

Your security is a partnership. By keeping your email locked, you keep your hard-earned money safe.

Stay Alert. Kaa Chonjo!